Updated on October 7th, 2026 by Nikolaos Sismanis
Real estate investment trusts – or REITs, for short – are compelling investment vehicles.
That’s because:
- They provide diversified real estate exposure
- Without the high up-front cost of traditional real estate
- They often have high dividend yields well in excess of the S&P 500
- U.S. REITs must distribute at least 90% of taxable income, excluding net capital gains, to investors
Bonus: You can download your free 200+ REIT list spreadsheet, complete with metrics that matter, by clicking on the link below:
In addition to the downloadable Excel sheet of all REITs, this article discusses why income investors should pay particularly close attention to this asset class.
And, we also include our top 7 REITs today based on expected total returns.
Table Of Contents
In addition to the full downloadable Excel spreadsheet, this article covers our top 7 REITs today, as ranked using expected total returns from The Sure Analysis Research Database.
The table of contents below allows for easy navigation.
- Why Invest In REITs?
- REIT Financial Metrics
- The Top 7 REITs Today
- #7: Rexford Industrial Realty (REXR)
- #6: Gaming and Leisure Properties (GLPI)
- #5: American Tower (AMT)
- #4: Essential Properties Realty Trust (EPRT)
- #3: Innovative Industrial Properties (IIPR)
- #2: VICI Properties (VICI)
- #1: NexPoint Residential Trust (NXRT)
Why Invest in REITs?
REITs are, by design, a fantastic asset class for investors looking to generate income.
Thus, one of the primary benefits of investing in these securities is their high dividend yields.
The currently high dividend yields of REITs are not an isolated occurrence.
In fact, this asset class has traded at a higher dividend yield than the S&P 500 for decades.
The high dividend yields of REITs are due to the regulatory implications of doing business as a real estate investment trust.
To qualify for U.S. REIT tax treatment, a company generally must distribute at least 90% of its taxable income, excluding net capital gains, as dividends.
Many publicly traded REITs issue common shares, while some trusts issue units.
A REIT can have a payout ratio below 90% when the denominator is funds from operations rather than taxable income (more on that later).
REIT Financial Metrics
REITs run unique business models.
More than the vast majority of other business types, they are primarily involved in the ownership of long-lived assets.
From an accounting perspective, this means that REITs incur significant non-cash depreciation and amortization expenses.
How does this affect the bottom line of REITs?
Depreciation and amortization expenses reduce a company’s net income, so a REIT’s dividend can exceed its reported net income while remaining covered by cash flow.
To give a better sense of financial performance and dividend safety, REITs developed the financial metric funds from operations, or FFO.
Just like earnings, FFO can be reported per share or per unit, providing a more useful measure of operating performance for many REITs.
FFO generally starts with net income, adds back real estate depreciation, amortization, and qualifying impairment charges, and excludes gains or losses on property sales, with adjustments for joint ventures and other specified items.
Adjusted FFO, or AFFO, makes further company-specific adjustments, often including recurring capital expenditures and non-cash rent items, so investors should examine each REIT’s reconciliation when assessing dividend coverage.
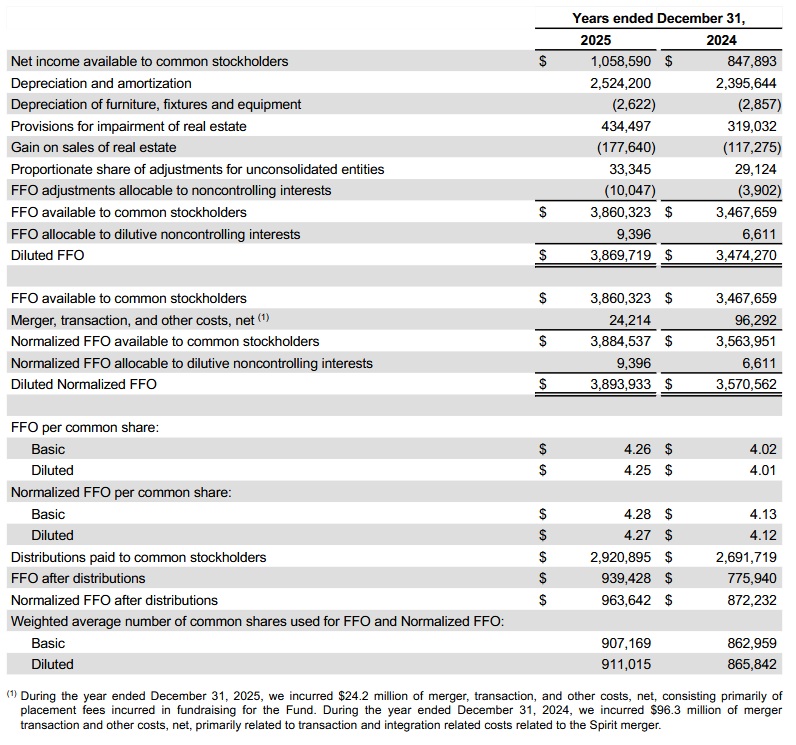
For an example of how FFO is calculated, consider the following net income-to-FFO reconciliation from Realty Income (O), one of the largest and most popular REIT securities.
Source: Realty Income 2025 Annual Report
In 2025, net income available to common stockholders was approximately $1.06 billion, while FFO available to common stockholders was $3.86 billion, a sizable difference between the two metrics.
This shows the profound effect that depreciation and amortization can have on the GAAP financial performance of real estate investment trusts.
The Top 7 REITs Today
Below we have ranked our top 7 REITs today based on expected annualized total returns over the next five years.
Expected total returns are in turn made up from dividend yield, expected growth on a per-share or per-unit basis, and valuation multiple changes.
Expected total return investing takes into account income (dividend yield), growth, and value.
Note: The REITs below have not been vetted for safety.
These are high expected total return securities, but they may come with elevated risks.
We encourage investors to fully consider the risk/reward profile of these investments.
For the Top 10 REITs each month, based on expected total returns and safety, see our Top 10 REITs service.
Top REIT #7: Rexford Industrial Realty (REXR)
- Expected Total Return: 16.0%
- Dividend Yield: 4.7%
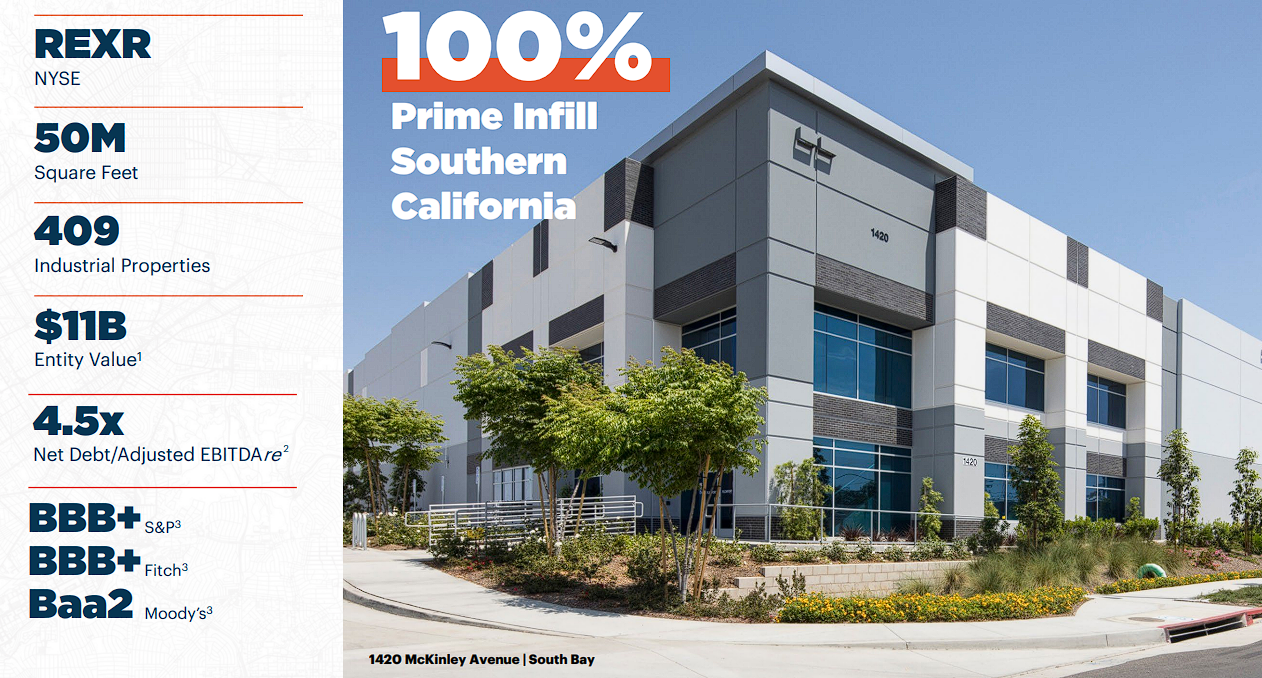
Rexford Industrial Realty owns, operates, and redevelops industrial properties in infill Southern California, where limited land supports long-term demand.
At June 30th, 2026, its portfolio contained 409 properties and approximately 50 million square feet.
Second-quarter Core FFO increased 1.2% to $141.4 million, or $0.63 per share, up 6.8%.
Same-property cash NOI grew 1.5%, but comparable leasing rents declined 2.8% on a net-effective basis and 11.3% on a cash basis.
The portfolio realignment also prompted $624.8 million of non-cash impairments during the quarter.
On September 17th, Rexford completed its $1.2 billion sale of 22 properties, bringing completed year-to-date dispositions to $1.5 billion.
Through that announcement, third-quarter proceeds had funded $485 million of debt repayments and $205 million of share repurchases.
Management estimated year-end net debt to adjusted EBITDAre of 3.5 times and reaffirmed 2026 Core FFO guidance of $2.38 to $2.43 per share.
The quarterly dividend is $0.435 per share, or $1.74 annualized, following 12 years of annual growth.
That payout represents approximately 72% of projected Core FFO.
The sale strengthens financial flexibility, but stabilizing rents and reinvesting proceeds effectively remain essential to the expected-return case.
Deep Dive: Click here to download (for free) our most recent 3-Page Sure Analysis PDF report on REXR.
Top REIT #6: Gaming and Leisure Properties (GLPI)
- Expected Total Return: 16.2%
- Dividend Yield: 8.6%
Gaming and Leisure Properties had interests in 71 gaming and related facilities across 21 states at June 30th, 2026, and leases them to casino operators under long-term triple-net agreements.

This structure places property-level expenses with tenants and gives the REIT contractual rent streams, although operator concentration remains an important risk.
Second-quarter revenue increased 9.0% to $430.5 million, while adjusted FFO rose to $304.0 million from $276.1 million.
Adjusted FFO per share advanced 7.3% to $1.03, and management raised full-year guidance to $4.10 to $4.12 per share.
Growth is coming from sale-leaseback transactions and development funding for tenants.
GLPI invested $191 million in tenant projects during the quarter and completed its $225 million commitment for PENN Entertainment’s Hollywood Casino Aurora conversion.
Management expects another $400 million to $450 million of development funding in the second half of 2026.
The quarterly dividend was raised 5.1% in May to $0.82 per share and was maintained at that rate in September, equaling $3.28 annualized.
The dividend consumes roughly 80% of projected adjusted FFO, although GLPI reduced its cash dividend during the 2020 pandemic.
The high yield is supported by long leases and current coverage, but investors should monitor tenant health, the cost of financing the development pipeline, and leverage of approximately 4.8 times net debt to adjusted EBITDA.
Deep Dive: Click here to download (for free) our most recent 3-Page Sure Analysis PDF report on GLPI.
Top REIT #5: American Tower (AMT)
- Expected Total Return: 16.2%
- Dividend Yield: 4.3%
American Tower is one of the world’s largest communications-infrastructure REITs, leasing space on towers and other sites to wireless carriers while also owning the CoreSite data-center platform.
The model benefits from recurring contractual revenue and long-term demand for mobile data, cloud connectivity, and low-latency computing.
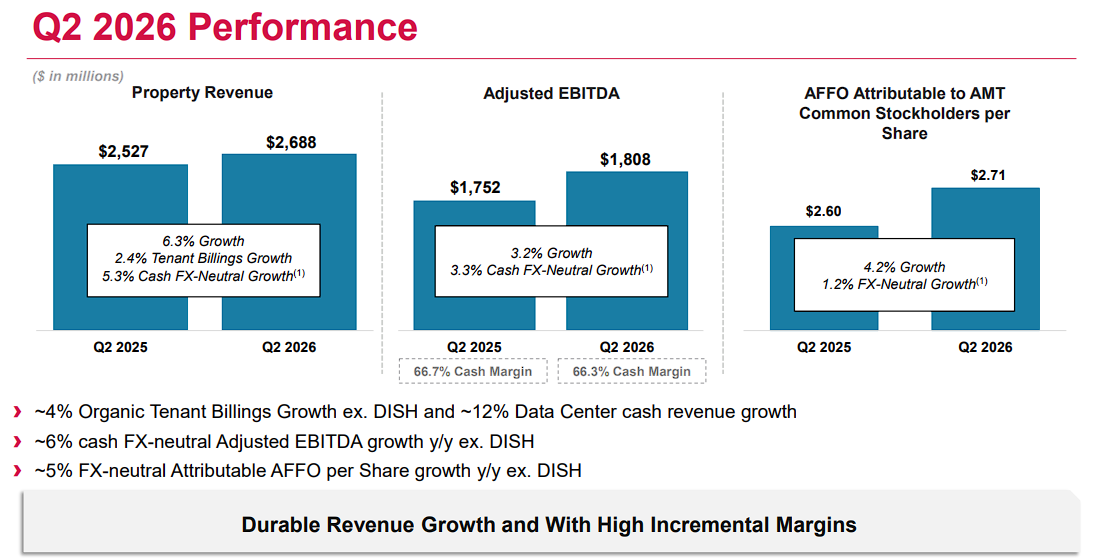
Second-quarter revenue increased 4.7% to $2.75 billion, while property revenue grew 6.3% to $2.69 billion.
AFFO attributable to common shareholders rose 3.8% to $1.26 billion, and AFFO per share increased 4.2% to $2.71.
June 30th net leverage was 4.9 times annualized adjusted EBITDA.
CoreSite posted record leasing activity as hybrid-cloud and artificial-intelligence workloads supported data-center demand.
American Tower raised its 2026 outlook again and now expects AFFO per share of $11.00 to $11.17.
The September declaration maintained the quarterly dividend at $1.79 per share, or $7.16 annualized, following 15 years of annual dividend growth.
That payout represents roughly 65% of expected AFFO, providing more coverage than many high-yield REITs.
In September, American Tower priced $1.6 billion of notes at coupons of 5.3% to 5.75%, partly to refinance $600 million of 1.45% notes due in 2026.
Higher refinancing costs, carrier consolidation, and currency exposure remain risks.
Deep Dive: Click here to download (for free) our most recent 3-Page Sure Analysis PDF report on AMT.
Top REIT #4: Essential Properties Realty Trust (EPRT)
- Expected Total Return: 16.6%
- Dividend Yield: 5.0%
Essential Properties Realty Trust owns single-tenant properties leased to middle-market service and experience-based businesses, including restaurants, car washes, automotive services, and medical providers.
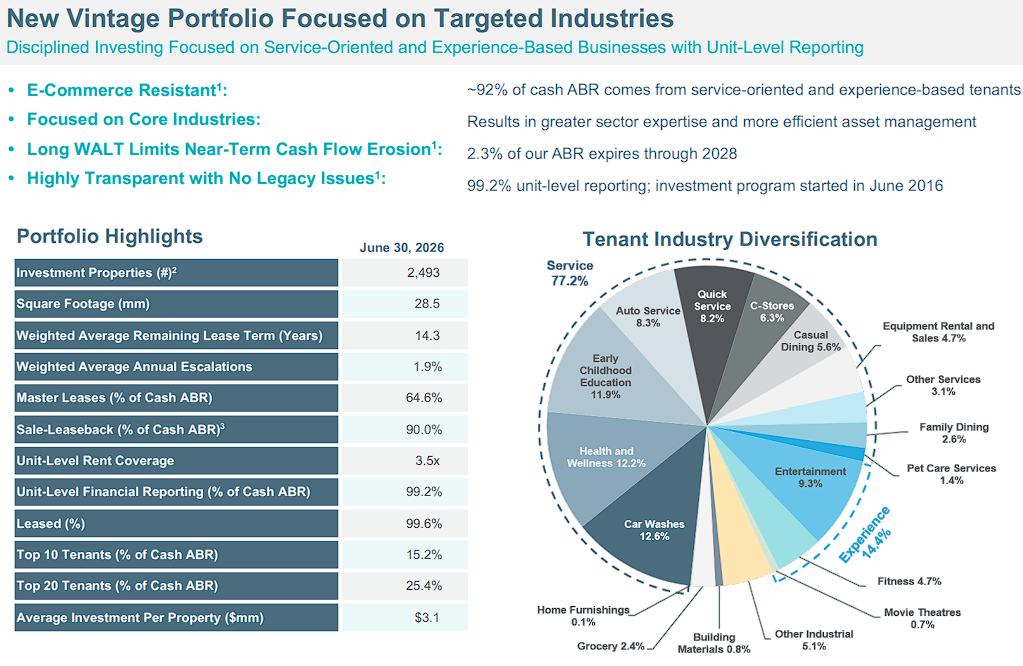
Its long-term net leases generally place property expenses with tenants, while industry diversification limits reliance on any one operator.
At June 30th, 2026, the portfolio comprised 2,493 properties, with 99.6% occupancy, a 14.3-year weighted-average remaining lease term, and tenant rent coverage of 3.5 times.
Second-quarter FFO per share grew 6% to $0.53, while AFFO per share increased 9% to $0.50.
EPRT invested $332.4 million across 103 properties at a 7.8% weighted-average cash capitalization rate.
Management raised 2026 AFFO guidance to $2.01 to $2.05 per share and expects $1.2 billion to $1.5 billion of investments.
Actual net debt to annualized adjusted EBITDAre was 4.5 times; the 3.5-times pro forma figure assumes settlement of outstanding forward equity sales.
In September, EPRT appointed Craig Vachris as chief investment officer following AJ Peil’s departure.
The September dividend declaration maintained $0.32 quarterly, or $1.28 annualized, following seven years of annual dividend growth.
The payout consumes roughly 63% of projected AFFO, but middle-market tenant credit, acquisition discipline, and financing costs remain important risks.
Deep Dive: Click here to download (for free) our most recent 3-Page Sure Analysis PDF report on EPRT.
Top REIT #3: Innovative Industrial Properties (IIPR)
- Expected Total Return: 17.3%
- Dividend Yield: 15.1%
Innovative Industrial Properties is an internally managed specialty REIT that owns regulated-cannabis cultivation and processing facilities, alongside selected life-science investments.
At June 30th, 2026, it owned 108 properties totaling 8.4 million rentable square feet across 19 states and had invested $2.4 billion in the portfolio.

Second-quarter revenue increased 0.7% to $63.3 million, while adjusted FFO per share rose 7.0% to $1.83.
Portfolio stabilization remains critical because several cannabis tenants have experienced financial distress.
IIPR applied $1.2 million of tenant security deposits to rent during the quarter.
During the quarter, IIPR executed a new Curaleaf lease at a former PharmaCann property and continued working toward replacement tenants for four former 4Front properties.
It also sold a New York property for $88.5 million, including seller financing, and fully funded its $270 million strategic life-science investment with IQHQ.
IQHQ generated $8.5 million of interest and dividend income during the quarter.
Liquidity was $299.7 million, while net debt equaled 14.2% of gross assets.
The September dividend declaration maintained $1.90 per share, or $7.60 annualized, with the quarterly rate unchanged since 2024.
However, the dividend exceeded second-quarter adjusted FFO and the SARD payout ratio is approximately 109%.
The exceptionally high yield carries substantial tenant-credit, collection, re-leasing, and dividend-cut risks.
Deep Dive: Click here to download (for free) our most recent 3-Page Sure Analysis PDF report on IIPR.
Top REIT #2: VICI Properties (VICI)
- Expected Total Return: 20.3%
- Dividend Yield: 8.1%
VICI Properties is an experiential net-lease REIT whose portfolio includes major gaming, hospitality, wellness, entertainment, and leisure destinations.
Its long-term triple-net leases shift property expenses to tenants and generally include contractual rent escalators, creating a predictable base of rental income.
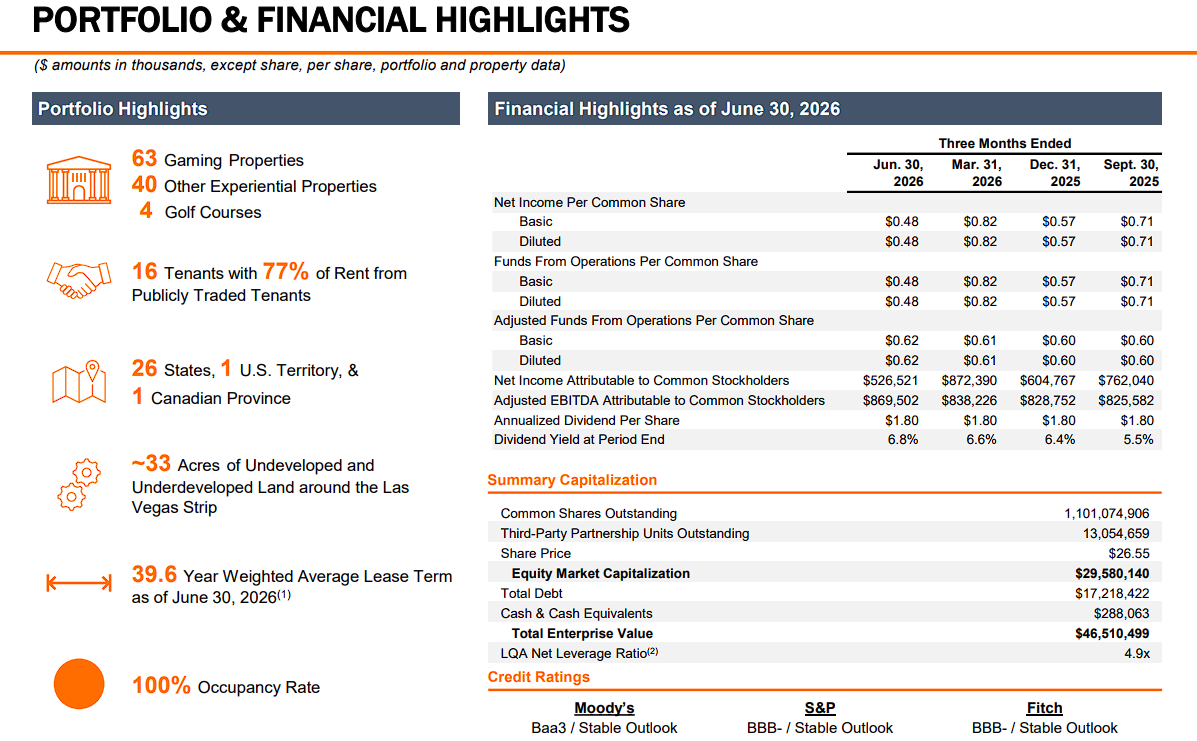
Second-quarter revenue increased 5.7% to $1.1 billion, while AFFO attributable to common shareholders grew 7.8% to $679.6 million.
AFFO per share rose 4.6% to $0.62, and management updated full-year guidance to $2.45 to $2.47 per share.
VICI continued expanding and diversifying its tenant roster.
It closed the $1.16 billion acquisition of seven Nevada casino properties, added gaming assets in Alberta, and began a build-to-suit relationship with Club Med in St. Croix.
These investments broaden exposure beyond the largest legacy operators, although Caesars Entertainment and MGM Resorts still represent important tenant concentrations.
On September 3rd, VICI raised its quarterly dividend 2.2% to $0.46 per share, or $1.84 annualized, extending its annual dividend-growth record to nine years.
The new payout remains comfortably covered by projected AFFO.
VICI also completed a $1.75 billion notes offering in August to refinance 2026 maturities, with coupons of 5.4% and 5.75%.
Tenant concentration, acquisition underwriting, and higher borrowing costs remain risks.
Deep Dive: Click here to download (for free) our most recent 3-Page Sure Analysis PDF report on VICI.
Top REIT #1: NexPoint Residential Trust (NXRT)
- Expected Total Return: 24.6%
- Dividend Yield: 10.5%
NexPoint Residential Trust owns middle-income apartment communities with value-add potential in large Sun Belt markets across the Southeastern and Southwestern United States.
Its strategy centers on renovating units and improving amenities.
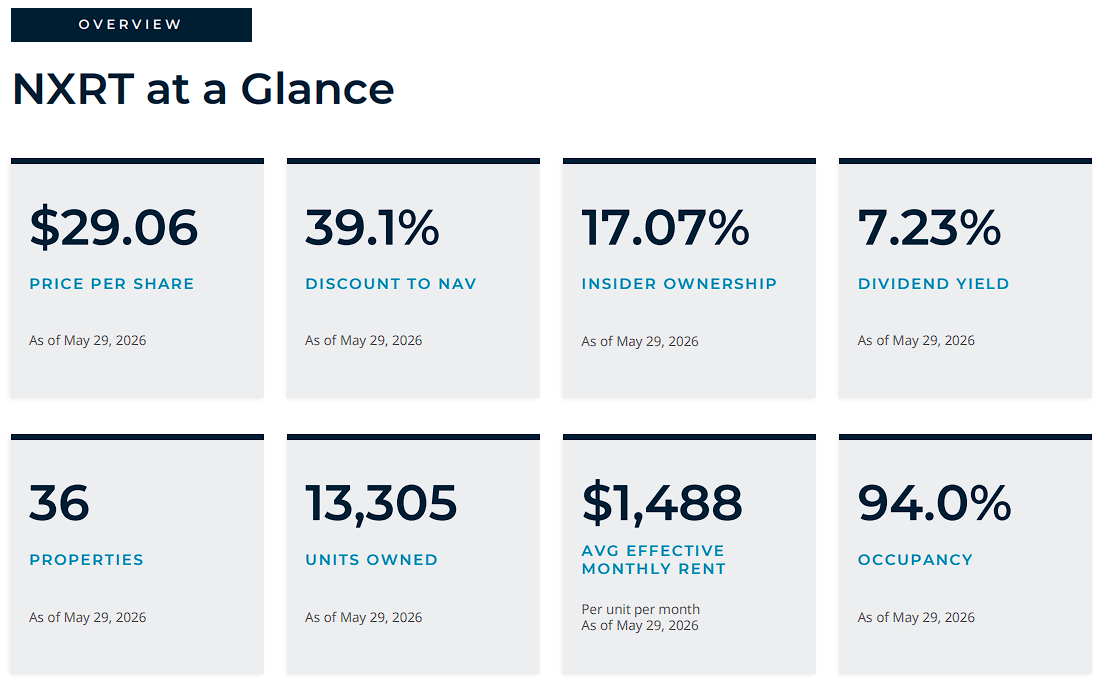
Second-quarter revenue increased to $64.6 million from $63.1 million, but same-store revenue declined 0.6%, and same-store NOI fell 2.9%.
Core FFO decreased to $0.66 per share from $0.71, while AFFO slipped to $0.77 from $0.80.
The 36-property portfolio contained 13,305 units, with 93.5% physical occupancy and a $1,490 weighted-average monthly rent.
NXRT completed 459 upgrades during the quarter at a 23% return on investment.
It also deployed $22.1 million into a 10% fixed-rate loan for a North Carolina apartment property, launching its Delaware statutory trust bridge-lending program using revolving-credit funding.
However, management lowered its 2026 AFFO-per-share outlook to a midpoint of $2.86 as supply and operating pressure weighed on same-store performance.
The quarterly dividend is $0.53 per share, or $2.12 annualized, after 10 consecutive years of increases.
That payout represents roughly 74% of expected AFFO.
The high projected return depends on stabilizing rents and NOI while managing leverage, refinancing costs, and Sun Belt apartment supply.
Deep Dive: Click here to download (for free) our most recent 3-Page Sure Analysis PDF report on NXRT.
Final Thoughts
Our REITs Spreadsheet provides a broad starting point for researching publicly traded real estate investment trusts, while the seven names above represent the highest expected returns in the current Sure Analysis universe.
The opportunities span several property types.
For example, NexPoint offers Sun Belt apartments, while VICI and Gaming and Leisure Properties provide gaming-related net leases.
Rexford focuses on Southern California industrial real estate, American Tower owns digital infrastructure, Innovative Industrial Properties serves regulated cannabis operators, and Essential Properties provides net leases to service and experience-based businesses.
These high projected returns should not be confused with uniformly low risk.
Several companies face meaningful tenant, leverage, refinancing, occupancy, or payout challenges, and the estimates rely partly on valuation recovery that may not occur on schedule.
Investors should therefore examine AFFO coverage, balance-sheet strength, tenant quality, and property-level fundamentals alongside the headline yield and expected-return estimate.
Other Sure Dividend Resources
- Dividend Kings: 50+ years of rising dividends
- Dividend Champions: 25+ years of rising dividends
- Dividend Aristocrats: 25+ years of rising dividends and in the S&P 500
- High Dividend Stocks: 4%+ dividend yields
- Monthly Dividend Stocks: Individual securities that pay out every month
- Royalty Stocks: Detailed royalty stocks list
- MLPs: Detailed MLP list
- BDCs: Detailed BDC list