Article updated on November 2nd, 2026 by Nikolaos Sismanis
Spreadsheet data updated daily
The Dividend Aristocrats are an elite group of S&P 500 stocks with 25+ years of consecutive dividend increases.
Index membership note: The 68-company list below reflects S&P Dow Jones Indices’ announced removal of Kenvue (KVUE) from the S&P 500 before trading opens on November 4th, 2026, in connection with Kimberly-Clark’s acquisition of the company.
The requirements to be a Dividend Aristocrat are:
- Be in the S&P 500
- Have 25+ consecutive years of dividend increases
- Meet certain minimum size & liquidity requirements
This research report includes the following valuable free Dividend Aristocrats resources.
Resource #1: The Dividend Aristocrats Spreadsheet List
This spreadsheet contains important metrics, including: years of dividend growth, dividend yields, payout ratios, buy/hold/sell ratings, fair value prices, expected total returns, and much more.
Disclaimer: Sure Dividend is not affiliated with S&P Global in any way. S&P Global owns and maintains The Dividend Aristocrats Index. The information in this article and downloadable spreadsheet is based on Sure Dividend’s own review, summary, and analysis of the S&P 500 Dividend Aristocrats ETF (NOBL) and other sources, and is meant to help individual investors better understand this ETF and the index upon which it is based. None of the information in this article or spreadsheet is official data from S&P Global. Consult S&P Global for official information.
Resource #2: The 10 Best Dividend Aristocrats Today
This research report analyzes the 10 best Dividend Aristocrats now as ranked by expected total return. Expected total returns include estimated earnings-per-share growth, dividends, and the impact of any valuation multiple changes.
This ranking is best used as a research shortlist rather than an automatic buy list. Click on the links below to jump to analysis for any of the Top 10.
- #10: PPG Industries (PPG)
- #9: Hormel Foods (HRL)
- #8: Automatic Data Processing (ADP)
- #7: PepsiCo (PEP)
- #6: Amcor (AMCR)
- #5: Brown & Brown (BRO)
- #4: Clorox (CLX)
- #3: Caterpillar (CAT)
- #2: FactSet Research Systems (FDS)
- #1: Albemarle (ALB)
Resource #3: Sure Analysis Reports On All Dividend Aristocrats
We cover all 68 Dividend Aristocrats in the Sure Analysis Research Database. All are updated quarterly. This resource has links to our most recent stand-alone analysis on each of the Dividend Aristocrats.
Click here to jump to this resource now.
Resource #4: Historical Dividend Aristocrats List
We have compiled a comprehensive image of Dividend Aristocrats dating back to 1989.
Click here to jump to this resource now.
Please keep reading for our Dividend Aristocrats analysis.
Dividend Aristocrat #10: PPG Industries (PPG)
- 5-Year Expected Total Return: 13.8%
PPG Industries is one of the world’s largest coatings companies.
It supplies paints, coatings, and specialty materials to aerospace, automotive, industrial, packaging, and architectural customers.
Its technology, customer relationships, and global manufacturing footprint provide competitive advantages, although results remain exposed to industrial activity and raw-material inflation.
PPG recently raised its quarterly dividend from $0.71 to $0.74, extending its dividend-growth streak to 55 years.
It has also paid dividends for 512 consecutive quarters.
Third-quarter 2026 net sales increased 7% to $4.35 billion, while organic sales rose 5%, reflecting 3% higher pricing and 2% volume growth.
Adjusted earnings per share increased 6% to $2.25, and year-to-date operating cash flow reached approximately $1.2 billion.
Management raised the midpoint of full-year adjusted earnings-per-share guidance and narrowed the range to $7.90 to $8.10.
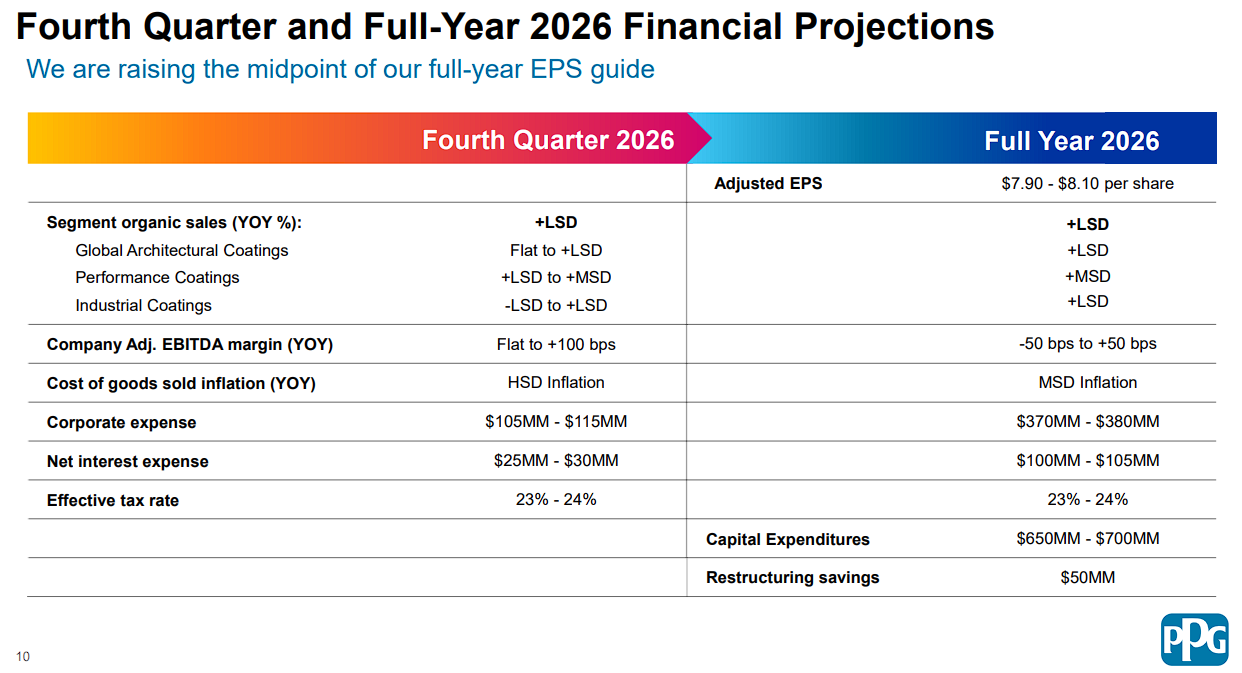
Aerospace and architectural coatings in Latin America led growth, while Performance Coatings delivered 8% organic growth.
Pricing actions fully offset cost inflation during the quarter, improving on the partial recovery achieved in the second quarter.
Industrial Coatings margins remained pressured by higher input costs, making continued pricing discipline and productivity gains important.
PPG’s moderate payout ratio leaves room for further dividend increases as earnings, margins, and cash flow improve.
Deep Dive: Click here to download (for free) our most recent 3-Page Sure Analysis PDF report on PPG Industries (PPG).
Dividend Aristocrat #9: Hormel Foods (HRL)
- 5-Year Expected Total Return: 13.9%
Hormel Foods produces branded packaged foods and meat products, including SPAM, Skippy, Applegate, and Planters.
Its established brands, distribution network, and Foodservice relationships support cash generation, although commodity costs and consumer demand can make results uneven.
Hormel has raised its dividend for 60 consecutive years. Its annualized dividend of $1.17 per share represents approximately 78% of our projected earnings, leaving less room for weak operating performance.
Third-quarter fiscal 2026 net sales declined 2.3% to $2.96 billion, and organic sales fell 2%.
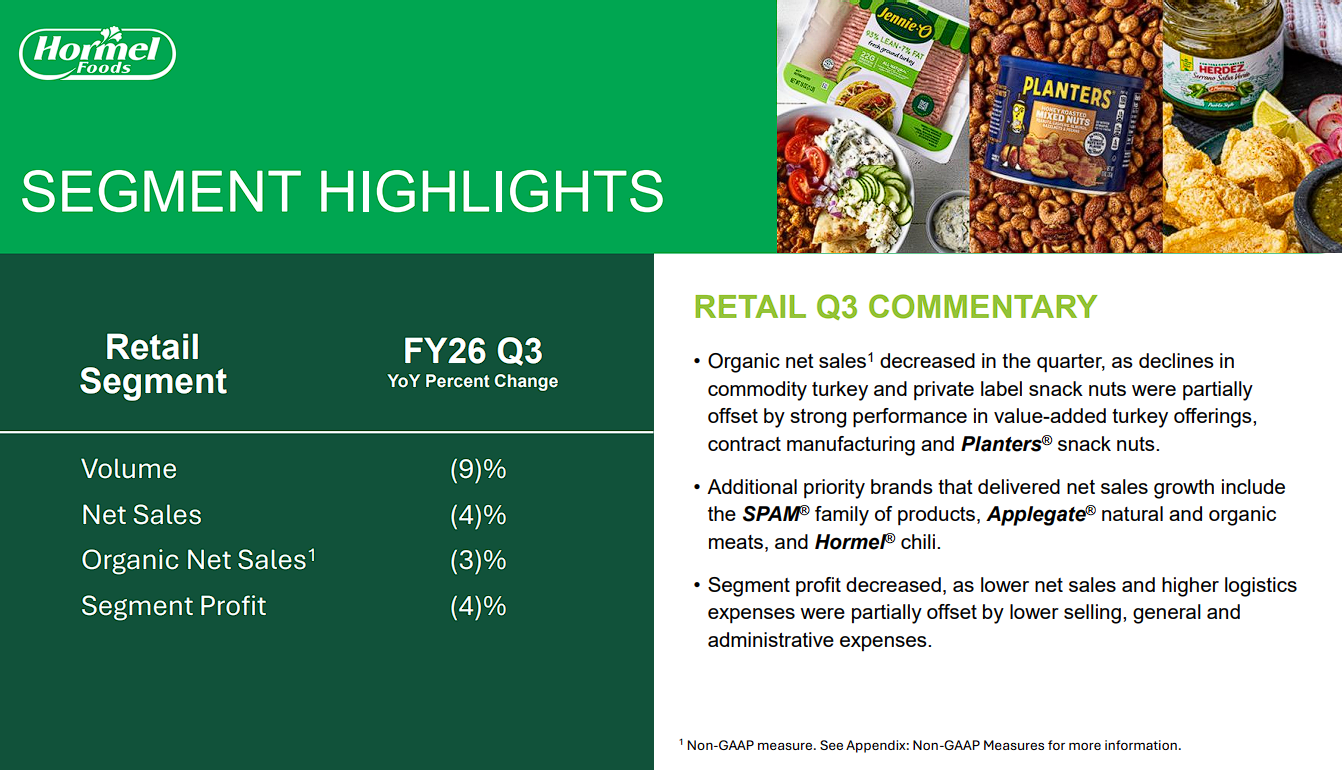
Adjusted earnings per share were $0.37, while adjusted operating margin improved to 9.0% and operating cash flow reached $241 million.
Management raised the lower end of its full-year adjusted earnings-per-share outlook to $1.45 to $1.51. The company also completed the sale of its Ceratti business in Brazil as it simplified its international portfolio.
On September 30th, Hormel agreed to acquire value-added chicken producer Brakebush for approximately $1.055 billion.
The transaction is expected to close in the first quarter of fiscal 2027 and become accretive to adjusted earnings per share in fiscal 2028, subject to the usual closing conditions.
John Ghingo became president and chief executive officer on October 26th, taking over from interim CEO Jeff Ettinger.
The return outlook combines a high starting yield with our 5% annual earnings-growth assumption and potential valuation recovery. Improving volumes, sustaining margins, and integrating Brakebush will be important to that outcome.
Deep Dive: Click here to download (for free) our most recent 3-Page Sure Analysis PDF report on Hormel Foods (HRL).
Dividend Aristocrat #8: Automatic Data Processing (ADP)
- 5-Year Expected Total Return: 14.3%
Automatic Data Processing is a leading provider of payroll, human-capital management, benefits, and compliance solutions.
Its services are deeply embedded in customers’ daily operations, supporting high retention, recurring revenue, and attractive margins.
ADP serves more than 1.1 million clients across over 140 countries.
The company has also increased its dividend for 51 consecutive years, including a 10% increase to $1.70 per quarter, or $6.80 annualized.
Fiscal first-quarter 2027 revenue increased 6% to approximately $5.5 billion.
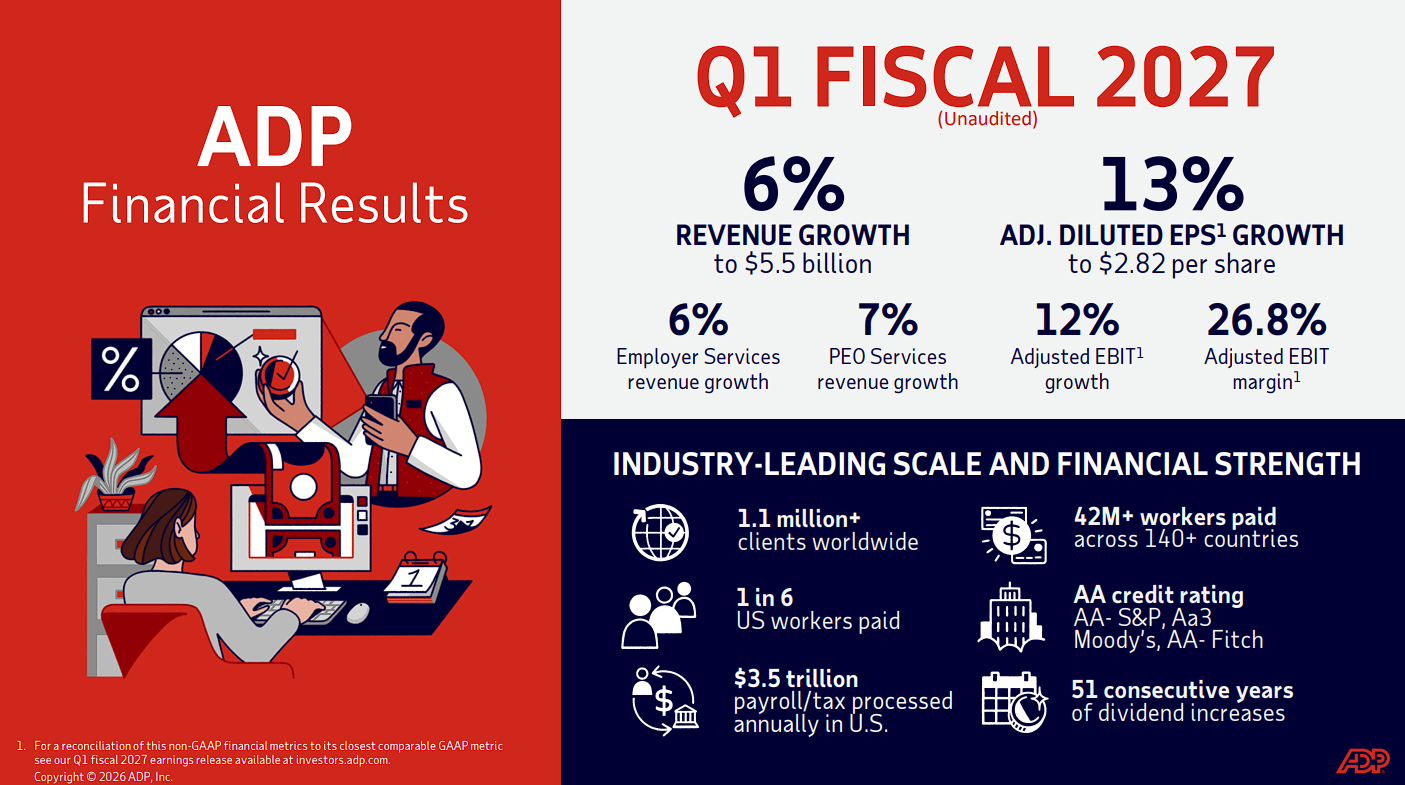
Adjusted earnings per share rose 13% to $2.82, while adjusted EBIT margin expanded 130 basis points to 26.8%.
Interest earned on client funds increased 15% to $329 million, benefiting from higher balances and investment yields.
Management raised its fiscal 2027 outlook to approximately 6% revenue growth and 10% to 12% adjusted earnings-per-share growth, with adjusted EBIT margin expansion of 70 to 90 basis points.
ADP’s growth strategy increasingly combines its large proprietary data set with artificial intelligence and next-generation platforms such as ADP Lyric.
The company is also integrating WorkForce Software to strengthen its global workforce-management capabilities.
Employment levels and client hiring activity can influence results, but recurring revenue and strong free cash flow limit volatility.
ADP’s moderate yield is balanced by its earnings growth, dividend growth, and durable competitive position.
Dividend Aristocrat #7: PepsiCo (PEP)
- 5-Year Expected Total Return: 15.4%
PepsiCo owns a diversified portfolio of global snack and beverage brands, including Pepsi, Gatorade, Doritos, Lay’s, Quaker, and Cheetos.
Its scale, distribution network, and brand strength have produced durable cash flow across economic cycles.
PepsiCo has paid quarterly dividends since 1965 and has raised its annual payout for 54 consecutive years.
The quarterly dividend is now $1.48, or $5.92 annualized, following a 4% increase.
Third-quarter 2026 net revenue rose 5.6% to $25.27 billion, while organic revenue increased 3.1%.
Core earnings per share increased 2% to $2.34, although core operating margin declined 35 basis points as cost pressure and investment spending weighed on profitability.
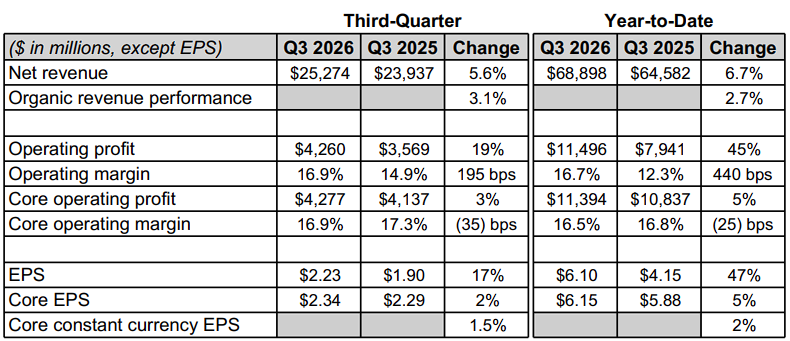
Management now expects approximately 3% organic revenue growth and 1% to 2% core constant-currency earnings-per-share growth in 2026, below its previous earnings-growth outlook.
Reported-currency core earnings per share are expected to grow 2.5% to 3.5%, and planned shareholder cash returns remain $8.9 billion.
The company is using automation, artificial intelligence, and a broad productivity program to simplify operations and improve margins.
These initiatives matter because North American consumers remain value-conscious, and restoring volume growth without excessive discounting is a key challenge.
PepsiCo offers one of the higher yields in this ranking, providing meaningful income while management works to improve execution.
Deep Dive: Click here to download (for free) our most recent 3-Page Sure Analysis PDF report on PepsiCo (PEP).
Dividend Aristocrat #6: Amcor (AMCR)
- 5-Year Expected Total Return: 16.0%
Amcor is a global packaging company serving food, beverage, healthcare, personal-care, and other consumer markets.
Demand for packaging tends to be relatively defensive, while the company’s scale and customer relationships support recurring volumes.
Fourth-quarter fiscal 2026 net sales were $6.4 billion, adjusted EBITDA reached $1.05 billion, and adjusted earnings per share increased 23% to $1.23.
For the full year, net sales totaled $23.5 billion, adjusted earnings per share rose 13% to $4.02, and free cash flow was $1.3 billion.
Amcor delivered $285 million of Berry Global synergies during fiscal 2026, about 10% above its original first-year expectation, while reaffirming the three-year target of $650 million.
Net leverage ended the year at 3.5 times, making further cash generation and debt reduction important.
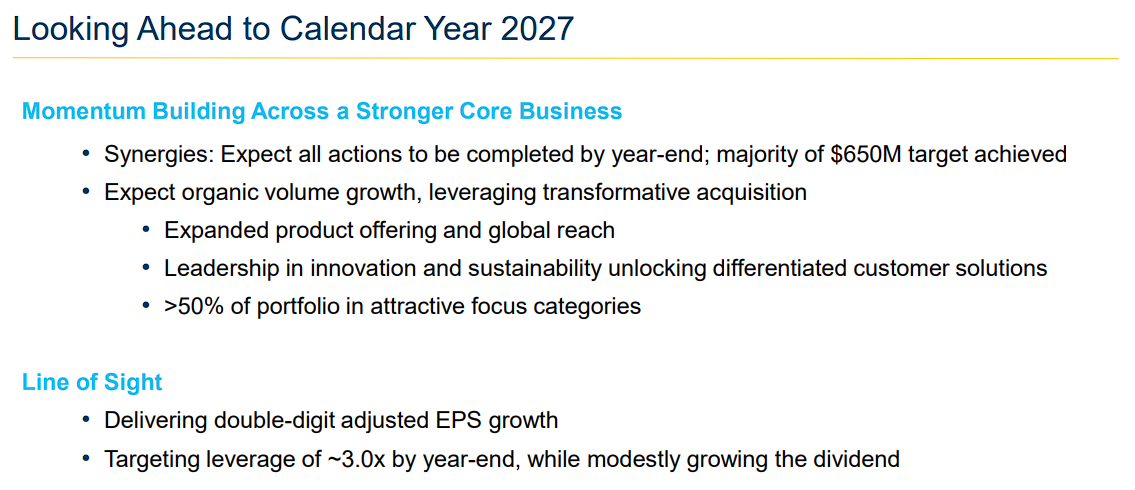
The company declared a quarterly dividend of $0.65 per share, 2% above the prior-year rate, extending the dividend-growth record to 42 years, including predecessor history.
Amcor is shifting to a calendar-year reporting schedule and expects adjusted earnings per share of $1.80 to $1.90 for the six-month transition period ending December 2026.
The high yield offers substantial income, but the investment case depends on integration, synergy realization, and disciplined deleveraging.
Deep Dive: Click here to download (for free) our most recent 3-Page Sure Analysis PDF report on Amcor (AMCR).
Dividend Aristocrat #5: Brown & Brown (BRO)
- 5-Year Expected Total Return: 17.6%
Brown & Brown is one of the largest U.S. insurance brokerages.
The company earns commissions and fees by connecting customers with insurers, creating a capital-light business with recurring revenue and strong cash generation.
Acquisitions have supplemented steady organic expansion for decades.
On October 21st, Brown & Brown raised its quarterly dividend 9% to $0.18 per share, extending its dividend-growth streak to 33 years.
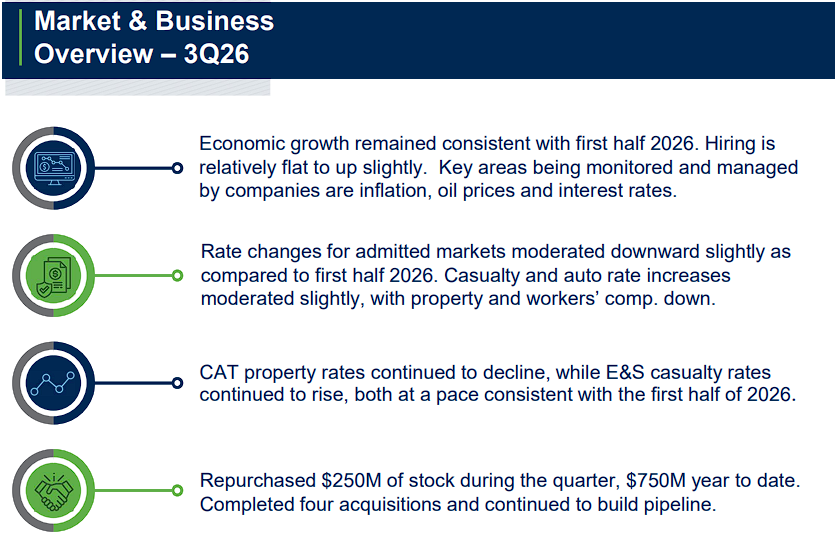
Third-quarter 2026 revenue increased 7.4% to approximately $1.7 billion.
Organic revenue grew 1.2%, or 1.5% including contingent commissions, indicating modest underlying expansion.
Adjusted earnings per share increased 1.9% to $1.07, while GAAP earnings per share declined 1.5% to $0.67.
Adjusted EBITDAC rose 1.7% to $597 million, but its margin declined to 34.6% from 36.6%.
The major development remains the integration of Accession Risk Management, which significantly expanded Brown & Brown’s scale and capabilities.
The transaction has expanded the business, but slower organic growth and margin compression highlight the need to deliver integration benefits and control expenses.
The dividend yield is low, yet the conservative payout ratio leaves considerable capacity for further dividend growth, acquisitions, and internal investment.
Deep Dive: Click here to download (for free) our most recent 3-Page Sure Analysis PDF report on Brown & Brown (BRO).
Dividend Aristocrat #4: Clorox (CLX)
- 5-Year Expected Total Return: 18.6%
Clorox owns a portfolio of household and consumer brands, including its namesake bleach products, Pine-Sol, Glad, Brita, Burt’s Bees, Fresh Step, Kingsford, and Hidden Valley.

Many of these products benefit from habitual purchases and strong category positions, although private-label competition and input costs remain important risks.
Fourth-quarter fiscal 2026 net sales declined 2% to $1.95 billion, while organic sales fell 13% because the company lapped shipments made ahead of its ERP transition.
The GOJO acquisition added approximately 10 percentage points to reported sales growth.
Gross margin contracted 520 basis points to 41.3%, and adjusted earnings per share declined 42% to $1.66.
For the full year, sales fell 5% to $6.72 billion and adjusted earnings per share decreased 28% to $5.53.
Management expects fiscal 2027 sales growth of 13% to 14%, including a 9.5-point contribution from GOJO.
Adjusted earnings per share are expected to reach $5.70 to $6.00, compared with GAAP earnings-per-share guidance of $5.41 to $5.71.
Clorox raised its quarterly dividend from $1.24 to $1.25 in July, extending its dividend-growth streak to 49 years.
The annualized payout is $5.00 per share, representing approximately 86% of projected earnings.
The high yield and expected rebound are appealing, but successful GOJO integration and margin recovery are essential to the return case.
Deep Dive: Click here to download (for free) our most recent 3-Page Sure Analysis PDF report on Clorox (CLX).
Dividend Aristocrat #3: Caterpillar (CAT)
- 5-Year Expected Total Return: 19.4%
Caterpillar manufactures construction and mining equipment, engines, turbines, and locomotives, with financing and services supporting its equipment businesses.
Its global dealer network, installed equipment base, and aftermarket services provide competitive advantages across cyclical end markets.
The quarterly dividend is $1.63 per share, or $6.52 annualized, following an approximately 8% increase in June. Caterpillar has paid higher annual dividends for 33 consecutive years.
Third-quarter 2026 sales and revenues increased 17% to $20.7 billion, driven by higher equipment volumes and favorable pricing.
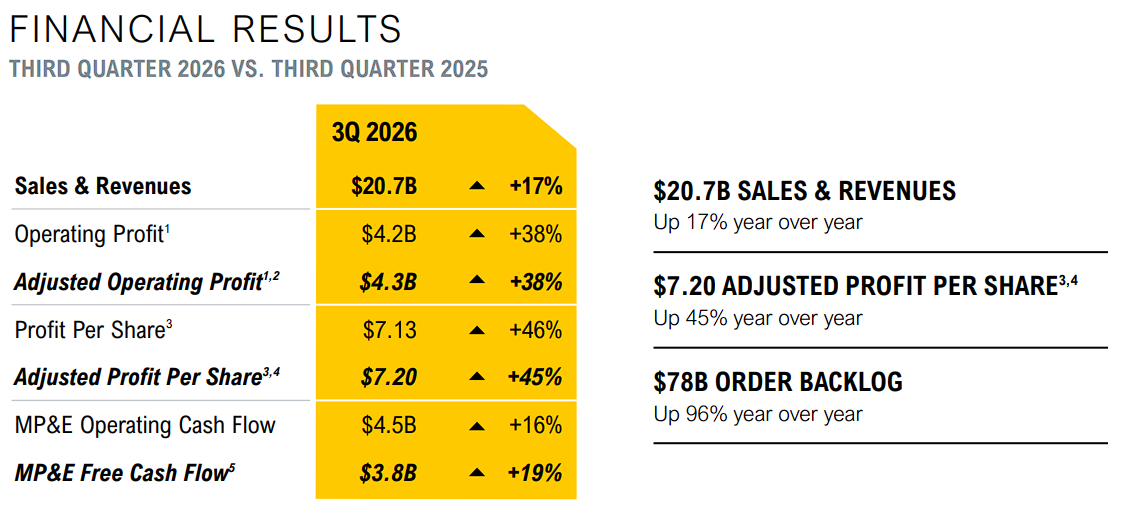
Adjusted earnings per share rose to $7.20 from $4.95, while adjusted operating margin expanded to 20.6% from 17.5%.
Power & Energy sales increased 18%, reflecting strong demand for power-generation equipment. Construction Industries sales also grew 18%, and Resource Industries sales increased 15%.
The company generated $4.4 billion of operating cash flow during the quarter and ended the period with $7.9 billion of cash.
Demand for data-center power, infrastructure investment, and equipment replacement provides growth opportunities, while tariffs, manufacturing capacity, and freight costs remain important constraints.
Our forecast assumes 17% annual earnings growth over five years, making sustained operating momentum particularly important to the projected return.
The dividend consumes approximately 24% of our earnings estimate, supporting further increases, but Caterpillar remains exposed to changes in construction spending, mining investment, and the broader economic cycle.
Deep Dive: Click here to download (for free) our most recent 3-Page Sure Analysis PDF report on Caterpillar (CAT).
Dividend Aristocrat #2: FactSet Research Systems (FDS)
- 5-Year Expected Total Return: 21.4%
FactSet Research Systems provides financial data, analytics, workflow tools, and enterprise solutions to investment managers, banks, wealth managers, and corporations.
Its products are embedded in customers’ daily processes, producing recurring subscription revenue and retention above 95%.
FactSet increased its quarterly dividend 5.5% to $1.16 in May, marking its 27th consecutive year of dividend growth.
Fiscal fourth-quarter 2026 revenue increased 6.3% to $634.7 million, while organic revenue grew 7.1%.
Adjusted earnings per share rose 11.6% to $4.52, and organic annual subscription value increased 7.0% to $2.57 billion.
For the full year, revenue grew 6.7% to $2.48 billion, adjusted earnings per share increased 6.1% to $18.01, and free cash flow rose 14.6% to $707.5 million.
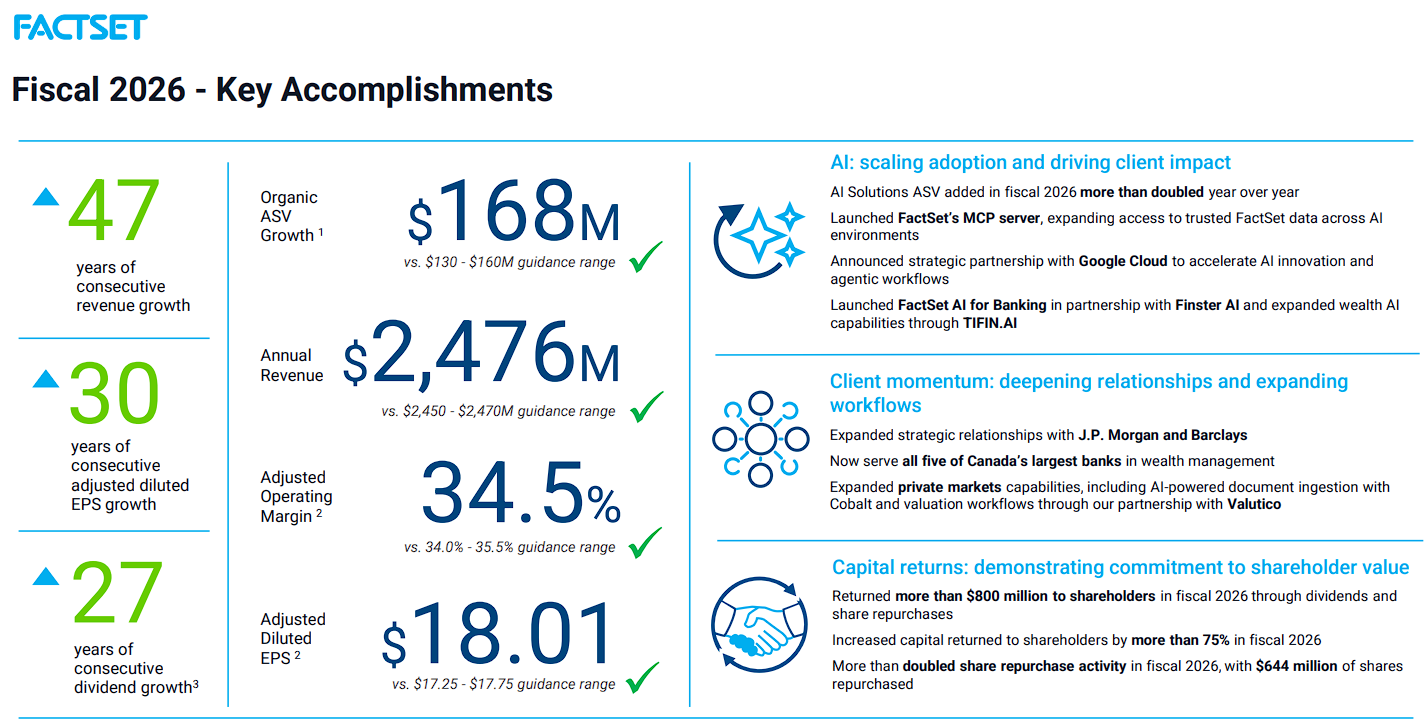
FactSet expects fiscal 2027 revenue of $2.60 billion to $2.63 billion and adjusted earnings per share of $19.25 to $19.65, with organic annual subscription value growth of 5.0% to 6.5%.
AI solutions annual subscription value added during fiscal 2026 more than doubled, and the acquisition of BCC Group International expands FactSet’s enterprise real-time market-data capabilities.
An October partnership with Nasdaq Private Market adds private-company ownership data, broadening FactSet’s private-markets offering.
The adjusted operating margin declined to 33.0% from 33.8%, reflecting compensation and technology spending.
The capital-light model supports dividends, buybacks, and product development, while the valuation provides substantial recovery potential.
Dividend Aristocrat #1: Albemarle (ALB)
- 5-Year Expected Total Return: 27.7%
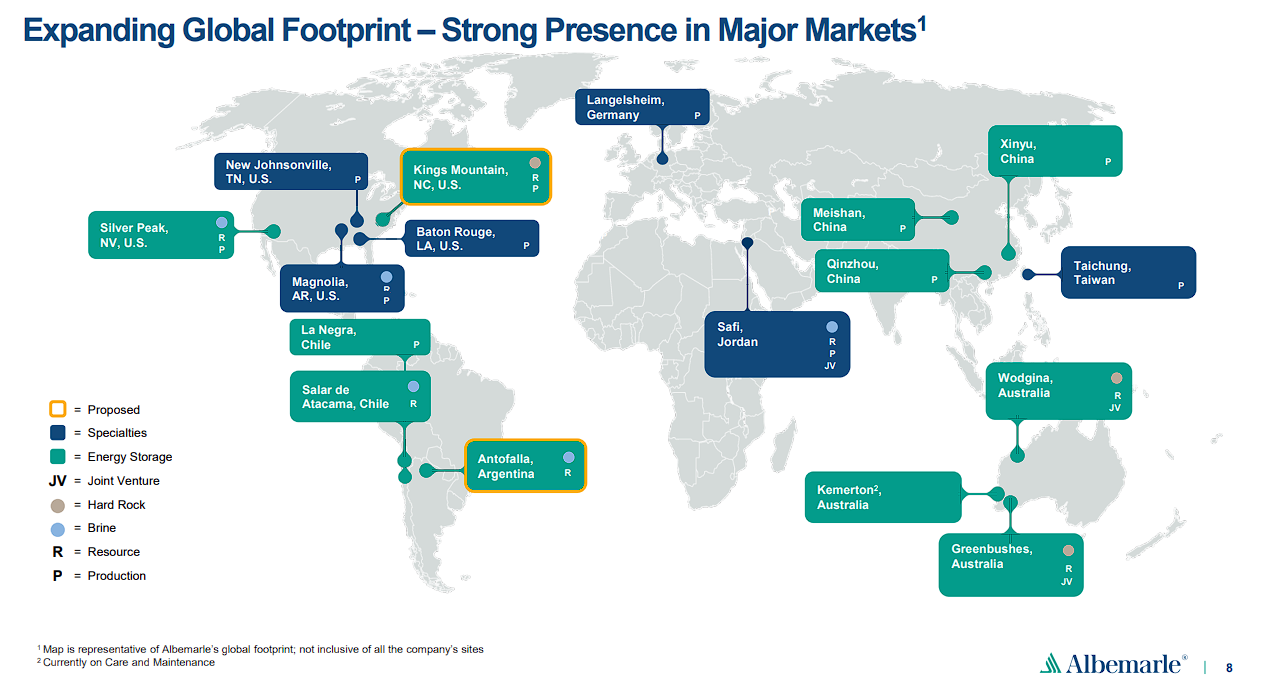
Albemarle is a leading producer of lithium and specialty chemicals used in electric vehicles, energy storage, semiconductors, flame retardants, and pharmaceuticals.
Its large resource base provides substantial long-term growth potential, but earnings can fluctuate sharply with lithium prices.
Albemarle has increased its dividend for 30 consecutive years, and the quarterly payout is $0.41 per share, or $1.64 annualized.
Second-quarter 2026 sales increased 31% to $1.74 billion as higher prices benefited Energy Storage and higher prices and volumes supported Specialties.
Net income was $480 million, or $3.52 per share, while adjusted EBITDA surged 155% to $858 million.
Cash from operations totaled $710 million, and free cash flow reached $638 million.
Energy Storage sales rose 78%, with adjusted EBITDA up 229%, reflecting a sharp recovery in lithium pricing.
The company delivered $100 million of year-to-date run-rate cost and productivity improvements and reduced its full-year capital-spending forecast to approximately $500 million.
Management expects minimal sales-volume impact from the June fire at Talison because better output from the Wodgina mine should offset the disruption.
Albemarle also named Ragnar Udd to succeed J. Kent Masters as president and chief executive officer, effective February 1st, 2027, with Masters moving to executive chair.
The low payout ratio supports the dividend, but commodity-price volatility and leadership execution remain central risks behind the elevated expected return.
Deep Dive: Click here to download (for free) our most recent 3-Page Sure Analysis PDF report on Albemarle (ALB).
Sure Analysis Reports On All Dividend Aristocrats
You can download (for free) the most recent 3-page PDF Sure Analysis Research Database report for every Dividend Aristocrat at the links below. The Dividend Aristocrats are organized by sector for easy access.
Consumer Staples
- Archer-Daniels-Midland (ADM)
- Brown-Forman (BF-B)
- Colgate-Palmolive (CL)
- Church & Dwight (CHD)
- Clorox (CLX)
- Coca-Cola (KO)
- Hormel Foods (HRL)
- J.M. Smucker (SJM)
- Kimberly-Clark (KMB)
- McCormick & Company (MKC)
- PepsiCo (PEP)
- Procter & Gamble (PG)
- Sysco Corporation (SYY)
- Target (TGT)
- Walmart (WMT)
Industrials
- Automatic Data Processing (ADP)
- A.O. Smith (AOS)
- C.H. Robinson Worldwide (CHRW)
- Cintas (CTAS)
- Dover (DOV)
- Emerson Electric (EMR)
- Expeditors International (EXPD)
- Fastenal Co. (FAST)
- Illinois Tool Works (ITW)
- Nordson Corporation (NDSN)
- Pentair (PNR)
- Stanley Black & Decker (SWK)
- W.W. Grainger (GWW)
- General Dynamics (GD)
- Caterpillar (CAT)
Financials
- Aflac (AFL)
- Brown & Brown (BRO)
- Cincinnati Financial (CINF)
- Erie Indemnity (ERIE)
- FactSet Research Systems (FDS)
- Franklin Resources (BEN)
- S&P Global (SPGI)
- T. Rowe Price Group (TROW)
- Chubb (CB)
Health Care
- Abbott Laboratories (ABT)
- AbbVie (ABBV)
- Becton, Dickinson & Company (BDX)
- Cardinal Health (CAH)
- Johnson & Johnson (JNJ)
- Medtronic (MDT)
- West Pharmaceutical Services (WST)
Materials
- Amcor (AMCR)
- Air Products and Chemicals (APD)
- Albemarle (ALB)
- Ecolab (ECL)
- PPG Industries (PPG)
- Sherwin-Williams (SHW)
- Nucor (NUE)
- Linde (LIN)
Consumer Discretionary
Energy
Real Estate
Utilities
Information Technology
Historical Dividend Aristocrats List
(1989 – 2026)
The image below shows the history of the Dividend Aristocrats Index from 1989 through 2026.
Note: CL, GPC, and NUE were all removed and re-added to the Dividend Aristocrats Index through the historical period analyzed above. We are unsure as to why. Companies created via a spin-off (like AbbVie) can be Dividend Aristocrats with less than 25 years of rising dividends if the parent company was a Dividend Aristocrat.
Disclaimer: Sure Dividend is not affiliated with S&P Global in any way. S&P Global owns and maintains The Dividend Aristocrats Index. The information in this article and downloadable spreadsheet and image below is based on Sure Dividend’s own review, summary, and analysis of the S&P 500 Dividend Aristocrats ETF (NOBL) and other sources, and is meant to help individual investors better understand this ETF and the index upon which it is based. None of the information in this article or spreadsheet is official data from S&P Global. Consult S&P Global for official information.
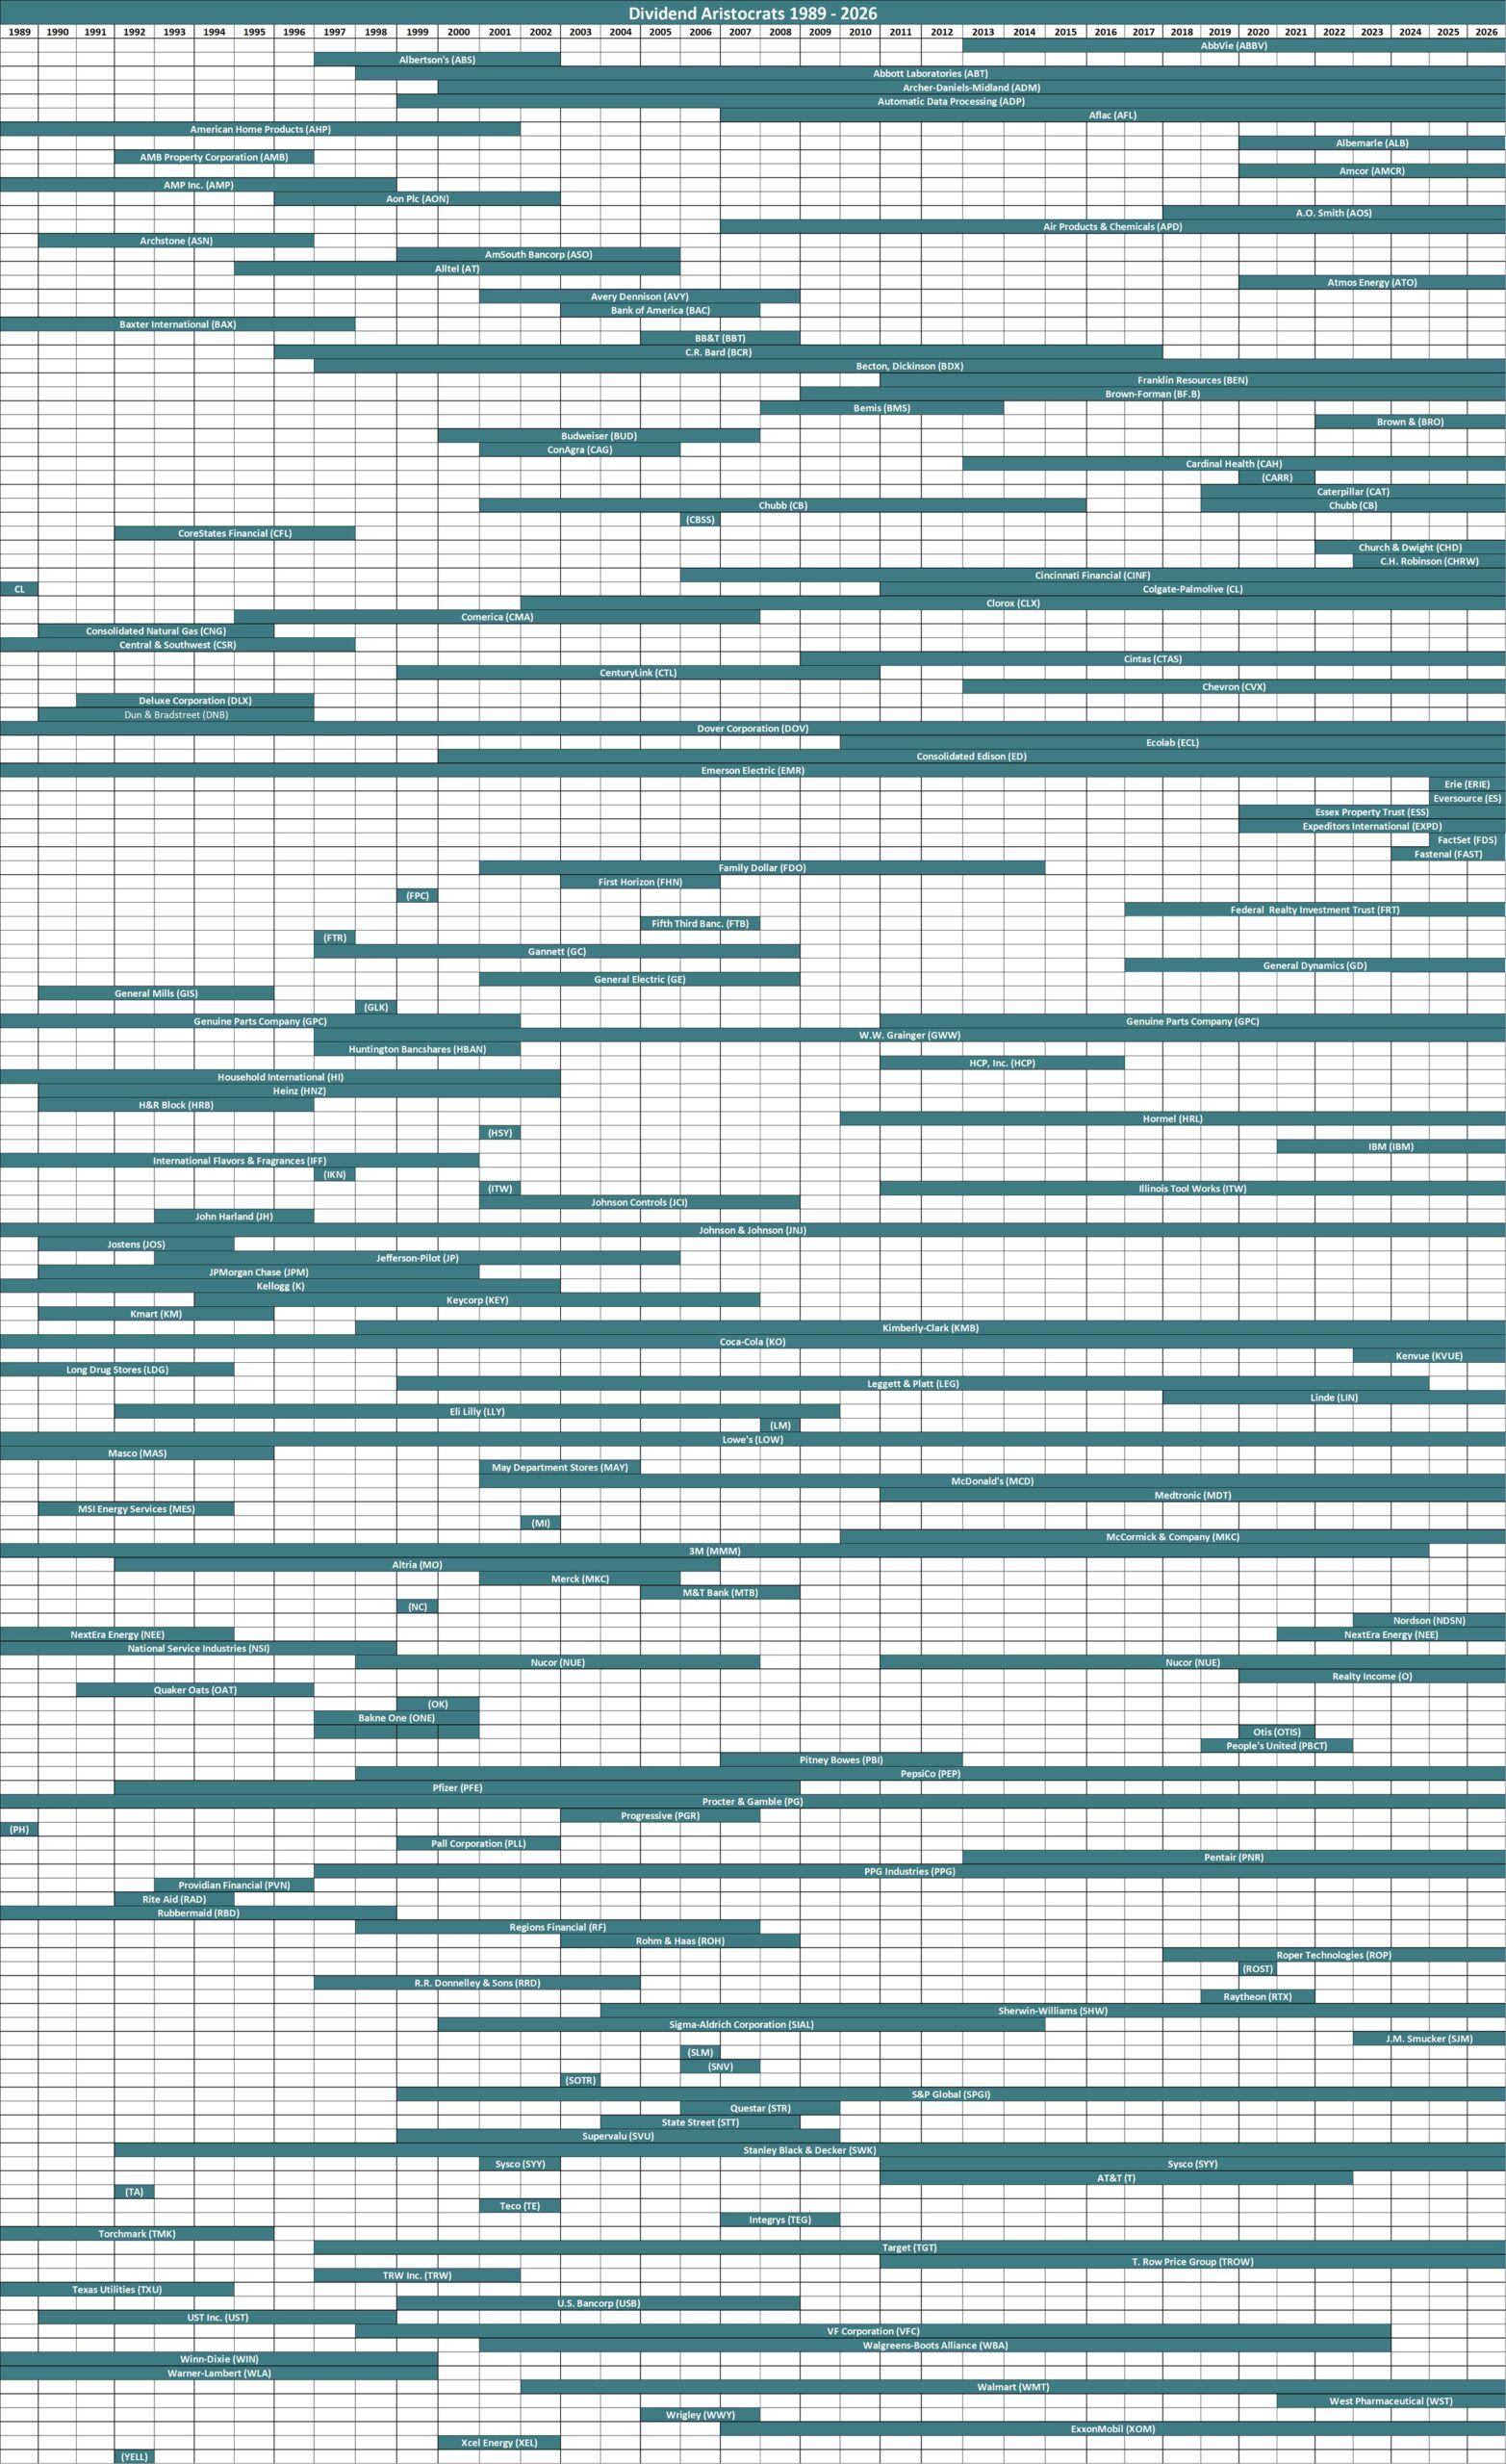
This information was compiled from the following sources:
- 1989 – 1991: Dividend Growth Investor
- 1992 – 2015: NOBL Index Historical Constituents
- 2016: Sure Dividend update
- 2017 – 2026: Data from S&P press releases and tracking dividends
Final Thoughts
The Dividend Aristocrats remain an unusually selective group of S&P 500 companies, each with at least 25 consecutive years of dividend growth.
Their records span recessions, inflationary periods, market declines, and major industry changes, providing meaningful evidence of durable business models and shareholder-friendly capital allocation.
The 10 Aristocrats highlighted above offer several distinct return profiles.
FactSet and Automatic Data Processing pair recurring revenue with long-term growth, while Brown & Brown adds an asset-light insurance brokerage model.
PepsiCo, Clorox, Amcor, and Hormel provide higher starting income and relatively defensive demand, although margin recovery and execution will be important.
PPG Industries, Albemarle, and Caterpillar offer more cyclical growth and recovery potential, with their results more sensitive to industrial activity, commodity conditions, and end-market demand.
Several of these stocks appear undervalued based on our five-year estimates, but projected returns depend on earnings growth, dividend sustainability, and eventual valuation changes.
A long dividend-growth streak is a valuable sign of resilience, but it does not eliminate company-specific risk or make every Aristocrat attractive at every price.
Other Sure Dividend Resources
- Dividend Kings: 50+ years of rising dividends
- Dividend Champions: 25+ years of rising dividends
- High Dividend Stocks: 4%+ dividend yields
- Monthly Dividend Stocks: Individual securities that pay out every month
- Royalty Stocks: Detailed royalty stocks list
- MLPs: Detailed MLP list
- REITs: Detailed REIT list
- BDCs: Detailed BDC list