Updated on October 13th, 2026 by Nikolaos Sismanis
Blue-chip stocks are:
- Established
- Financially strong
- Consistently profitable
Their strength makes them appealing investments for comparatively safe, reliable dividends and capital appreciation versus less established stocks.
Many stocks with 25+ years of rising dividends are blue-chip stocks.
That’s because they’ve demonstrated their ability to pay rising dividends over the long run.
But not all stocks with 25+ years of rising dividends (referred to as “Dividend Champions“) make equally good investments today…
That’s why this research report identifies and analyzes the top 10 best blue-chip stock buys now using expected total returns from the Sure Analysis Research Database.
We use the following criteria for our rankings:
- At least 25 consecutive years of dividend increases
- Dividend Risk Score of “A”
- Rank highest to lowest by expected total returns
The table of contents below allows for easy navigation.
- Blue-Chip Stock #10: PPG Industries (PPG)
- Blue-Chip Stock #9: H2O America (HTO)
- Blue-Chip Stock #8: PepsiCo (PEP)
- Blue-Chip Stock #7: Thomson Reuters (TRI)
- Blue-Chip Stock #6: Stepan Company (SCL)
- Blue-Chip Stock #5: Brown & Brown (BRO)
- Blue-Chip Stock #4: Badger Meter (BMI)
- Blue-Chip Stock #3: Stryker Corporation (SYK)
- Blue-Chip Stock #2: FactSet Research Systems (FDS)
- Blue-Chip Stock #1: Albemarle (ALB)
Blue-Chip Stock #10: PPG Industries (PPG)
- Dividend History: 55 years of consecutive increases
- Expected Total Return: 17.1%
PPG Industries is one of the world’s largest paints, coatings, and specialty-materials manufacturers, serving automotive, aerospace, industrial, packaging, and architectural markets.
Its technology portfolio, customer relationships, and global manufacturing footprint provide competitive advantages, although results remain exposed to industrial activity and raw-material inflation.
Second-quarter 2026 net sales increased 7% to $4.50 billion.
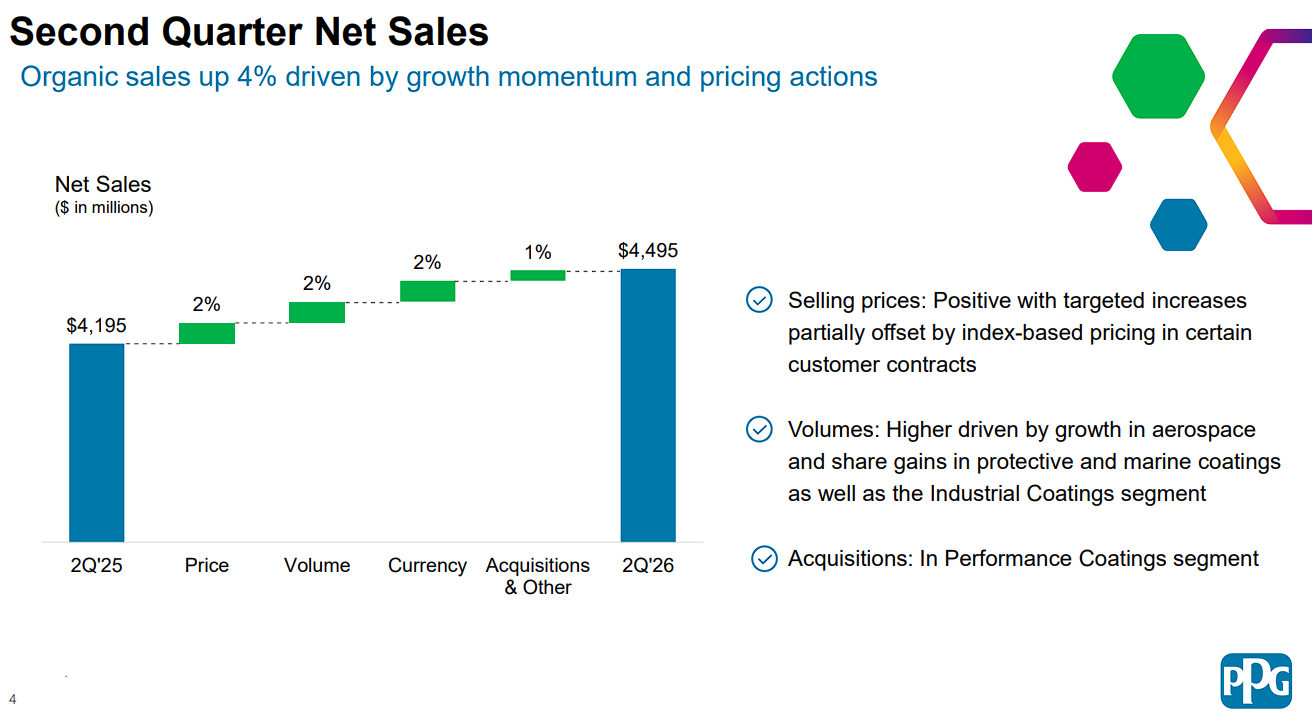
Organic sales rose 4%, driven by about 2% volume growth and 2% higher pricing.
Adjusted earnings per share edged up to $2.23 from $2.22, while year-to-date operating cash flow improved by roughly $220 million to nearly $600 million.
Global Architectural Coatings delivered higher margins, Industrial Coatings posted 5% organic growth, and Aerospace maintained a backlog near $300 million.
Management reaffirmed full-year adjusted earnings guidance of $7.70 to $8.10 per share and expects pricing and savings to fully cover inflation by the fourth quarter.
PPG raised its quarterly dividend to $0.74 in July, extending its dividend-growth streak to 55 years.
The company has also paid uninterrupted dividends since 1899, an unusually durable record even among blue-chip stocks.
Cash generation is improving, and continued execution on restructuring and cost reductions could help earnings recover as end markets normalize.
The moderate payout ratio leaves room for further dividend increases alongside investment in innovation, acquisitions, and share repurchases.
Deep Dive: Click here to download (for free) our most recent 3-Page Sure Analysis PDF report on PPG.
Blue-Chip Stock #9: H2O America (HTO)
- Dividend History: 58 years of consecutive increases
- Expected Total Return: 17.2%
H2O America, formerly SJW Group, operates regulated water and wastewater utilities in California, Connecticut, Maine, and Texas.
Essential services and regulated service territories support durable demand, while infrastructure investment expands the assets on which utilities can earn approved returns.
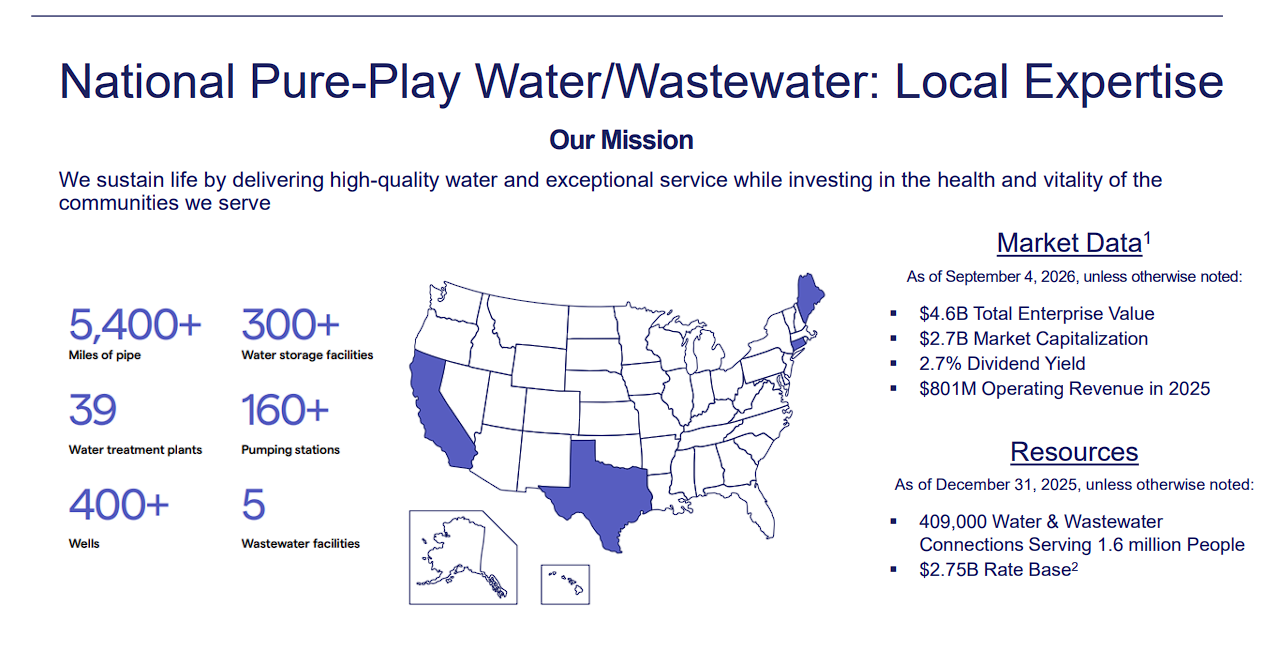
On October 1st, its Texas subsidiaries completed the $540 million Quadvest acquisition, more than doubling the company’s Texas water and wastewater connections.
Management expects Texas to represent 26% of its customer base by 2029, compared with 8% before the transaction.
The expansion adds a Houston-area development pipeline and reduces geographic concentration, although integration and financing remain important risks.
Second-quarter revenue increased 6% to $210.5 million, primarily reflecting rate increases.
Adjusted diluted earnings per share declined to $0.72 from $0.75 as additional shares more than offset higher adjusted net income.
At its July update, management reaffirmed standalone 2026 adjusted earnings guidance of $3.08 to $3.18 per share, excluding Quadvest and its financing.
The company plans $483 million of standalone capital investment in 2026 and $2.7 billion across 2026 through 2030, including acquisition-related expansion.
Its quarterly dividend is $0.44 per share, or $1.76 annualized, following a 4.8% increase and 58 consecutive years of dividend growth.
The payout represents approximately 56% of our earnings estimate, leaving room for reinvestment and further increases.
Deep Dive: Click here to download (for free) our most recent 3-Page Sure Analysis PDF report on HTO.
Blue-Chip Stock #8: PepsiCo (PEP)
- Dividend History: 54 years of consecutive increases
- Expected Total Return: 17.9%
PepsiCo owns global snack and beverage brands including Pepsi, Gatorade, Doritos, Lay’s, Quaker, and Cheetos.
Its brands, distribution network, and scale support recurring demand and cash generation across economic cycles.
The quarterly dividend is $1.48 per share, or $5.92 annualized, following a 4% increase that extended its dividend-growth record to 54 years.
On October 8th, PepsiCo reported third-quarter revenue of $25.27 billion, up 5.6%, with organic growth of 3.1%.
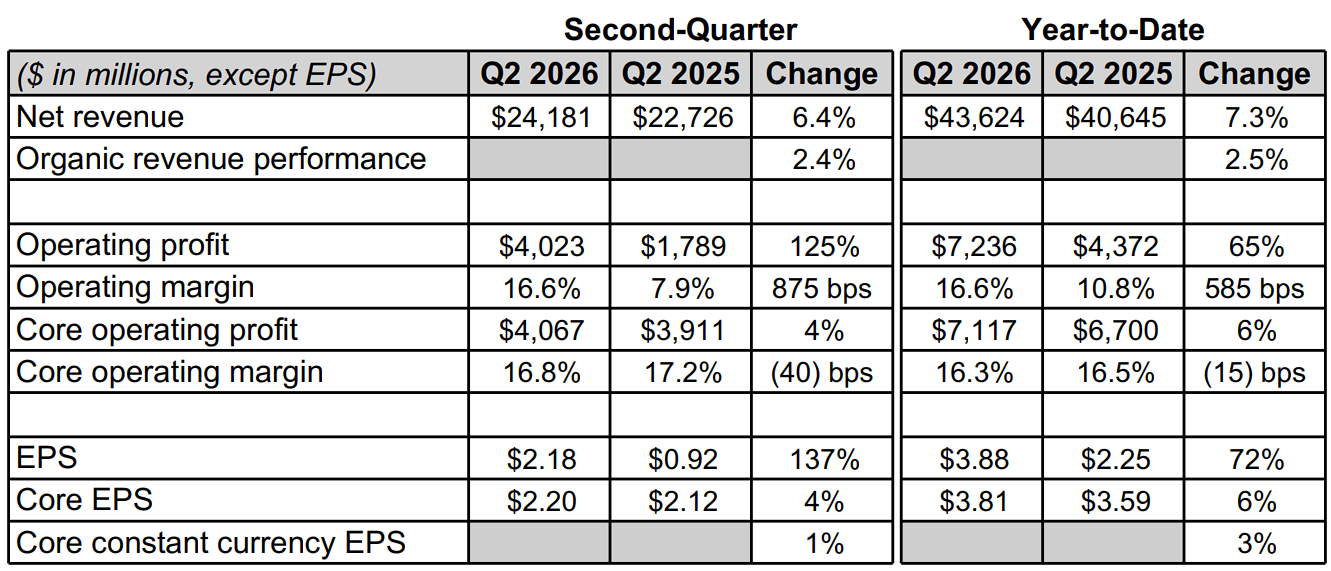
Core earnings per share increased 2% to $2.34, while core constant-currency growth was 1.5%.
International operations remained strong, and North American snack volumes improved, but higher costs and additional marketing investment pressured margins.
Core operating margin fell 35 basis points to 16.9%, despite productivity savings and a benefit from tariff refunds.
Management cut its 2026 core constant-currency earnings-growth outlook to 1% to 2%, from the low end of its previous 4% to 6% range.
It now expects approximately 3% organic revenue growth and 2.5% to 3.5% core earnings-per-share growth.
PepsiCo plans further structural cost reductions to fund innovation, brand investment, and stronger North American execution.
Its approximately 4.7% yield remains the highest in this ranking, but the return case requires improved execution alongside dividend income and valuation recovery.
Deep Dive: Click here to download (for free) our most recent 3-Page Sure Analysis PDF report on PEP.
Blue-Chip Stock #7: Thomson Reuters (TRI)
- Dividend History: 33 years of consecutive increases
- Expected Total Return: 19.4%
Thomson Reuters provides information, software, and workflow tools to legal, tax, accounting, corporate, and news professionals.
Its subscription-heavy model generates recurring revenue, while trusted proprietary content is especially valuable as customers adopt artificial intelligence.
The company has increased its dividend for 33 consecutive years.
A 10% increase for 2026 brought the quarterly dividend to $0.655 per share, or $2.62 annualized.
Second-quarter revenue grew 9% to $1.95 billion, with organic revenue up 8%.
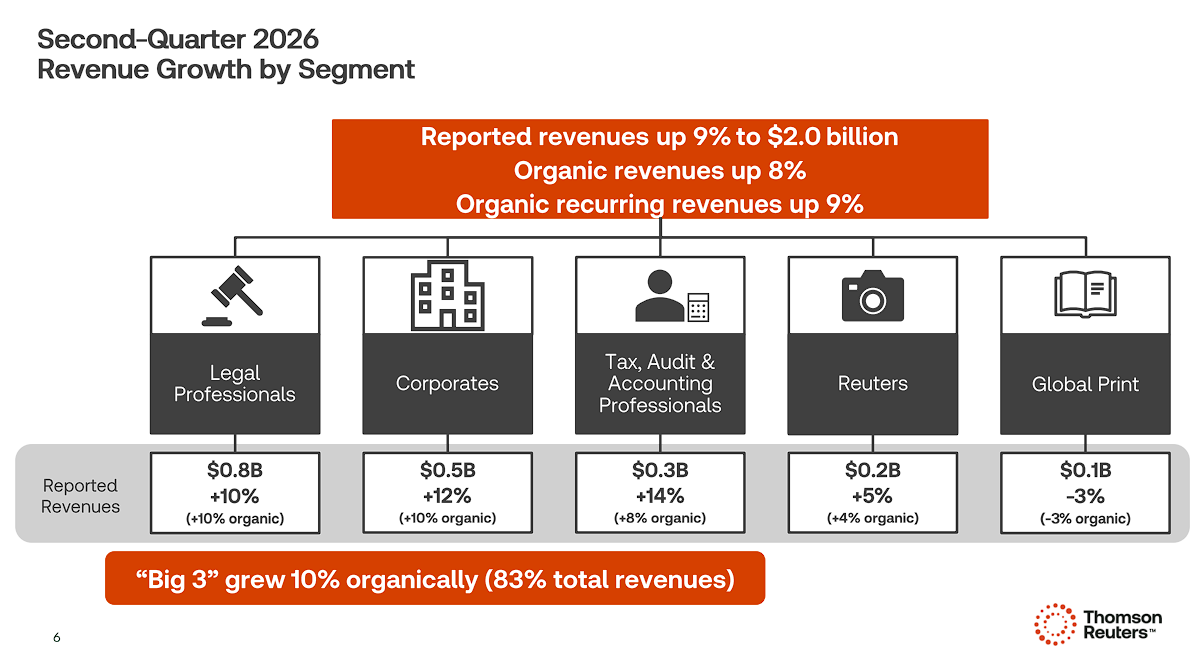
The three largest business segments produced 10% organic growth.
Operating profit increased 28% to $558 million, adjusted EBITDA rose 10% to $745 million, and adjusted earnings per share advanced 14% to $0.99.
Free cash flow increased 29% to $727 million.
The strong quarter prompted management to raise its 2026 organic-revenue-growth outlook to approximately 8%, with 9.5% to 10% growth expected from the Big 3 segments.
Thomson Reuters continues to invest in professional workflow software and fiduciary-grade artificial intelligence, including CoCounsel Legal and its proprietary large language model.
On October 1st, Thomson Reuters completed the sale of a 51% interest in Global Print to KKR, forming the independent Westbridge Print business.
The transaction reduces exposure to structurally slower print operations while preserving a 49% equity interest.
The company also completed a $600 million share-repurchase program, adding another use for its strong cash generation.
Deep Dive: Click here to download (for free) our most recent 3-Page Sure Analysis PDF report on TRI.
Blue-Chip Stock #6: Stepan Company (SCL)
- Dividend History: 59 years of consecutive increases
- Expected Total Return: 19.9%
Stepan Company manufactures specialty and intermediate chemicals for cleaning, personal care, agriculture, construction, and industrial applications.
Its Surfactants, Polymers, and Specialty Products businesses provide essential ingredients, although demand and margins remain sensitive to manufacturing activity and raw-material costs.
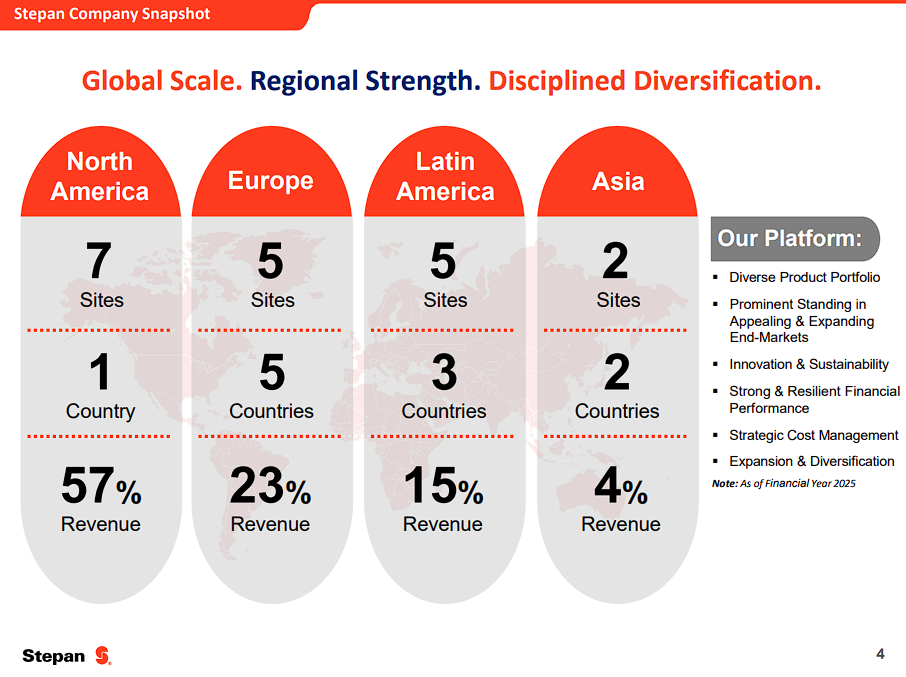
Second-quarter sales rose 15% to $684.1 million, supported by 6% organic volume growth.
Adjusted earnings per share more than doubled to $1.18, while adjusted EBITDA increased 45% to $74.4 million.
Some customers purchased ahead of announced price increases, so the quarter’s volume recovery needs confirmation in subsequent results.
Project Catalyst is reducing the cost base, but Stepan recorded $5.1 million of quarterly restructuring charges and expects $75 million to $80 million of charges during 2026.
Quarterly free cash flow remained negative at approximately $15 million, despite stronger earnings.
Management nevertheless expects full-year adjusted EBITDA growth, positive free cash flow, and further debt reduction.
In September, Stepan replaced its credit agreement with $500 million of committed facilities maturing in 2031, extending funding flexibility.
The quarterly dividend is $0.395 per share, or $1.58 annualized, and Sure Analysis records 59 consecutive years of dividend growth.
The return case depends on recovery from a depressed earnings base, continued cost savings, and improved cash conversion, making operating execution more important than the dividend record alone.
Deep Dive: Click here to download (for free) our most recent 3-Page Sure Analysis PDF report on SCL.
Blue-Chip Stock #5: Brown & Brown (BRO)
- Dividend History: 32 years of consecutive increases
- Expected Total Return: 20.1%
Brown & Brown is a diversified insurance broker offering property-and-casualty, employee-benefits, risk-management, and specialty insurance solutions.
Because brokers generally do not assume underwriting risk, the company can produce attractive cash flow while benefiting from insurance pricing and acquisition-led expansion.
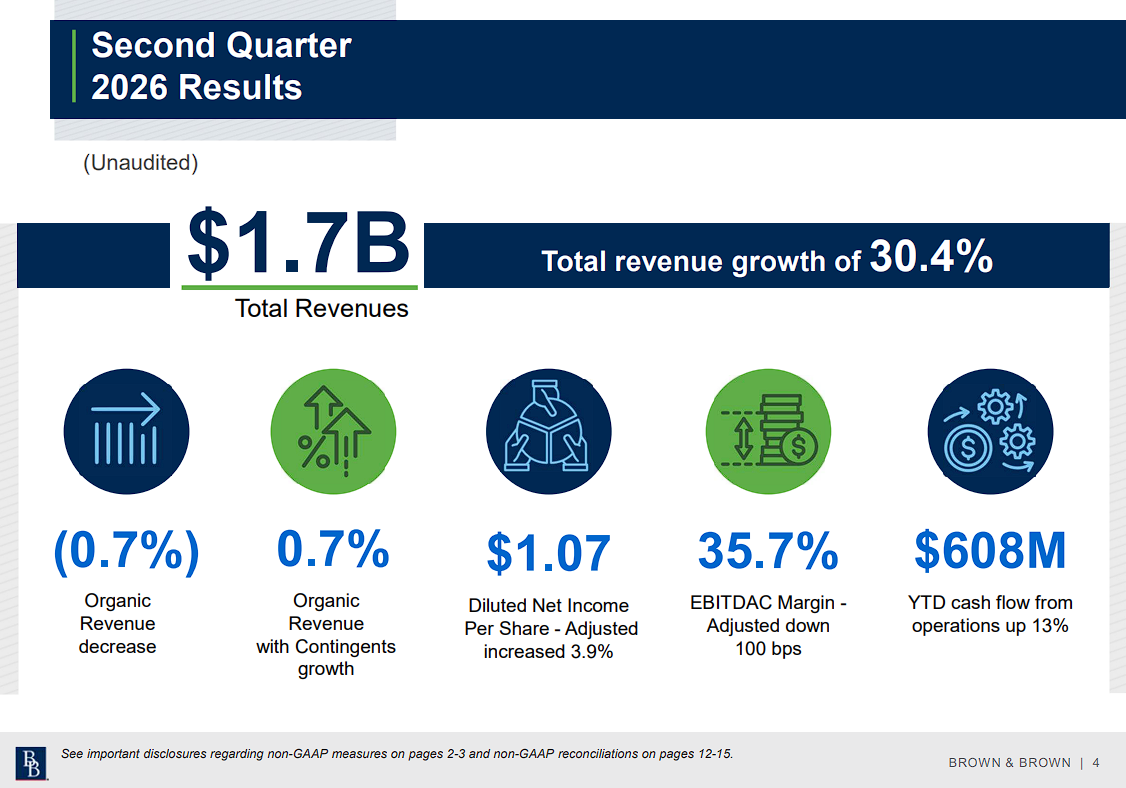
Second-quarter revenue rose 30.4% to $1.68 billion, driven primarily by acquisitions.
Net income increased 24.7% to $288 million, adjusted earnings per share rose 3.9% to $1.07, and adjusted EBITDAC advanced 27% to $598 million.
Organic revenue declined 0.7%, although it increased 0.7% when contingent commissions were included, showing softer underlying growth than the headline revenue figure.
The acquisition of Accession Risk Management and its Risk Strategies and One80 Intermediaries businesses has materially enlarged Brown & Brown.
The combined organization now has more than 23,000 professionals across over 700 locations.
Integration costs and purchase-accounting effects will influence near-term comparisons, but the transaction expands the company’s specialty capabilities and distribution reach.
Brown & Brown has also begun an artificial-intelligence-focused transformation to improve workflows and client service across the enlarged organization.
The quarterly dividend is $0.165 per share, and the company has raised its annual dividend for 32 consecutive years.
Its low payout ratio leaves substantial room to reinvest while continuing that dividend-growth record.
Deep Dive: Click here to download (for free) our most recent 3-Page Sure Analysis PDF report on BRO.
Blue-Chip Stock #4: Badger Meter (BMI)
- Dividend History: 34 years of consecutive increases
- Expected Total Return: 20.3%
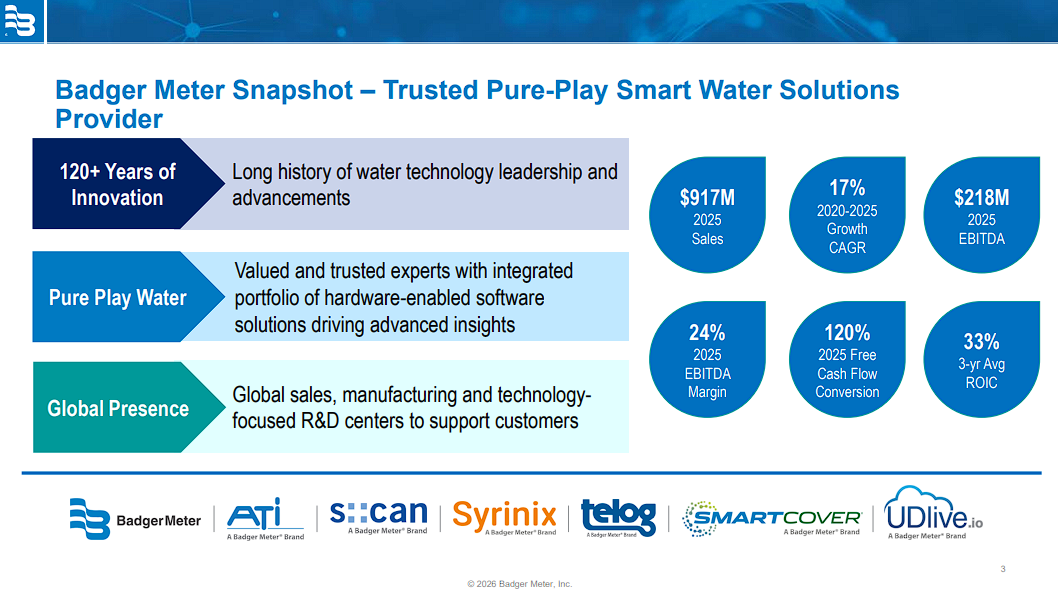
Badger Meter provides smart water meters, flow-measurement equipment, software, and related communication technologies to utilities and industrial customers.
Its expanding installed base and recurring software and service revenue support attractive long-term economics, while municipal water infrastructure provides durable demand.
Second-quarter 2026 sales totaled $222.3 million, up 10% sequentially but down 7% from a particularly strong prior-year quarter.
Utility water revenue declined 8%, while flow-instrumentation revenue increased 6%.
Operating earnings fell 12% to $39.4 million, operating margin was 17.7%, and earnings per share declined to $1.02 from $1.17.
Management expects project deployments to strengthen in the second half and continues to anticipate roughly flat full-year base-business revenue.
Badger Meter acquired UDlive in May, adding remote sewer-network monitoring technology and expanding its addressable market beyond clean-water metering.
In September, Badger Meter introduced OneNetwork, a software platform that combines water, wastewater, and stormwater data to help utilities monitor networks and prioritize investment.
In August, Badger Meter raised its quarterly dividend 10% to $0.44, marking 34 consecutive years of dividend growth.
The yield remains low, but the debt-free balance sheet, conservative payout, and recurring revenue provide substantial protection for future increases.
We expect long-term returns to be driven primarily by earnings growth and valuation recovery, while the timing of utility projects may continue to create uneven quarterly comparisons.
Deep Dive: Click here to download (for free) our most recent 3-Page Sure Analysis PDF report on BMI.
Blue-Chip Stock #3: Stryker Corporation (SYK)
- Dividend History: 32 years of consecutive increases
- Expected Total Return: 20.7%
Stryker is a leading medical-technology company with products spanning MedSurg, Neurotechnology, and Orthopaedics.
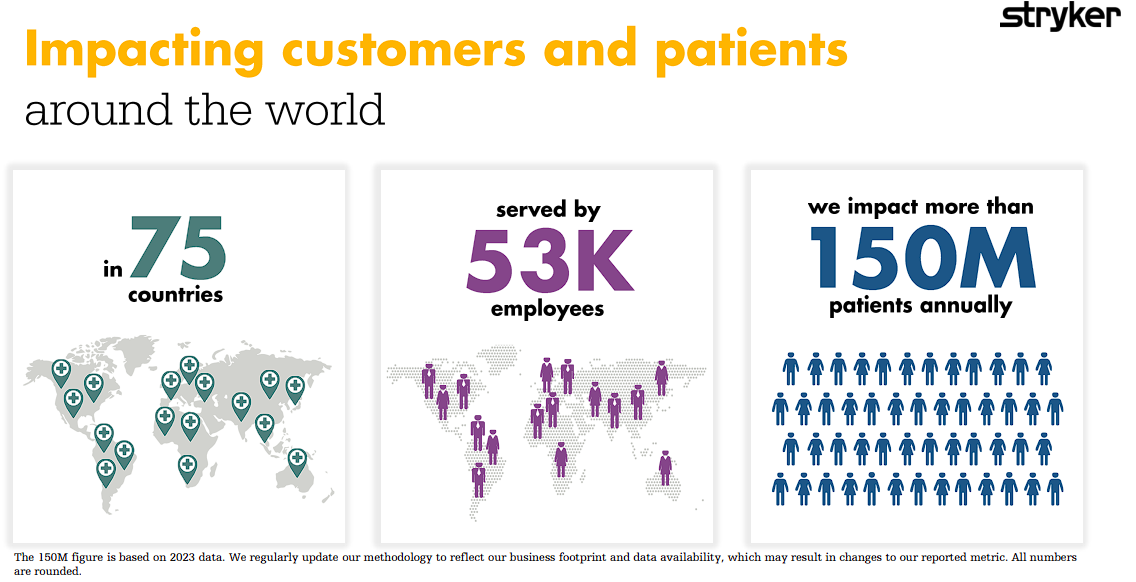
Its installed base of surgical equipment, implants, instruments, and robotic systems creates recurring demand as procedure volumes grow.
Second-quarter 2026 sales increased 9.4% to $6.59 billion, including 9.0% organic growth.
Organic sales rose 9.2% in MedSurg and Neurotechnology and 8.6% in Orthopaedics, showing broad momentum across the portfolio.
Adjusted operating margin expanded 170 basis points to 27.4%, while adjusted earnings per share climbed 17.9% to $3.69.
These results represented a strong recovery from the cyber incident that disrupted the first quarter and temporarily raised expenses.
In August, Stryker agreed to acquire ZuriMED, developer of the FiberLocker rotator-cuff augmentation system, extending its shoulder-care portfolio.
Management narrowed its full-year outlook to organic sales growth of 8.3% to 9.3% and adjusted earnings of $14.95 to $15.10 per share.
Stryker declared a quarterly dividend of $0.88 in August, 4.8% above the prior-year payment, and has increased its dividend for 32 consecutive years.
The yield is modest, but the conservative payout ratio leaves ample capacity for continued dividend growth.
Procedure demand, margin expansion, and valuation recovery support our return estimate, while cybersecurity, acquisition integration, and hospital spending remain risks.
Deep Dive: Click here to download (for free) our most recent 3-Page Sure Analysis PDF report on SYK.
Blue-Chip Stock #2: FactSet Research Systems (FDS)
- Dividend History: 27 years of consecutive increases
- Expected Total Return: 22.1%
FactSet Research Systems supplies financial data, analytics, and workflow tools to investment managers, banks, wealth managers, and other financial professionals.
Embedded workflows, proprietary data, and recurring subscriptions support customer retention and pricing power.
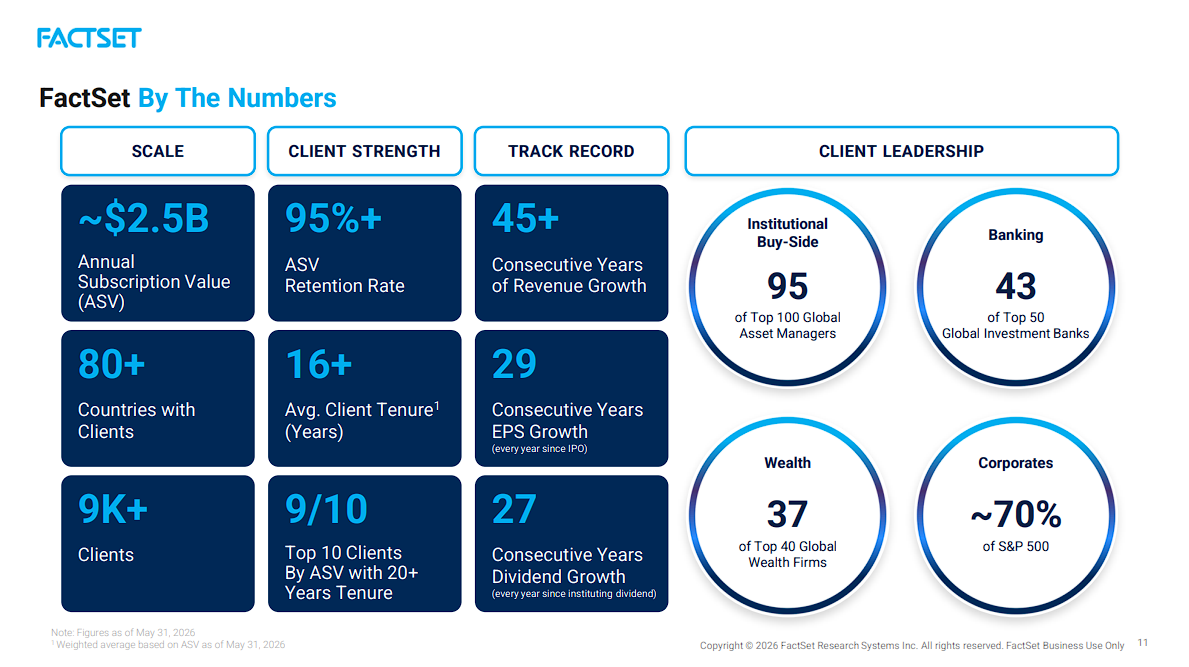
On September 30th, FactSet reported fiscal fourth-quarter revenue of $634.7 million, up 6.3%, with organic revenue growth of 7.1%.
Organic annual subscription value increased 7.0% to $2.57 billion, and annual subscription-value retention remained above 95%.
Adjusted earnings per share rose 11.6% to $4.52, although adjusted operating margin slipped to 33.0% from 33.8% as compensation and technology spending increased.
Full-year adjusted earnings reached $18.01 per share, while free cash flow grew 14.6% to $707.5 million.
For fiscal 2027, management expects organic subscription-value growth of 5% to 6.5%, adjusted operating margins of 34.75% to 35.25%, and adjusted earnings of $19.25 to $19.65 per share.
FactSet also acquired BCC Group International in September, expanding its cloud and hybrid real-time market-data capabilities.
On October 8th, it expanded its Scotia Wealth Management partnership.
AI-related subscription additions more than doubled during fiscal 2026, supporting the opportunity to deepen client relationships.
The quarterly dividend is $1.16 per share, or $4.64 annualized, and FactSet has increased its dividend for 27 consecutive years.
Strong cash generation supports capital returns, but achieving margin recovery while maintaining subscription growth remains central to the investment case.
Deep Dive: Click here to download (for free) our most recent 3-Page Sure Analysis PDF report on FDS.
Blue-Chip Stock #1: Albemarle (ALB)
- Dividend History: 30 years of consecutive increases
- Expected Total Return: 24.9%
Albemarle is a global specialty-chemicals company and one of the world’s largest lithium producers.
Energy Storage supplies battery-grade lithium, while Specialties provides bromine-based and other products for industrial and consumer markets.
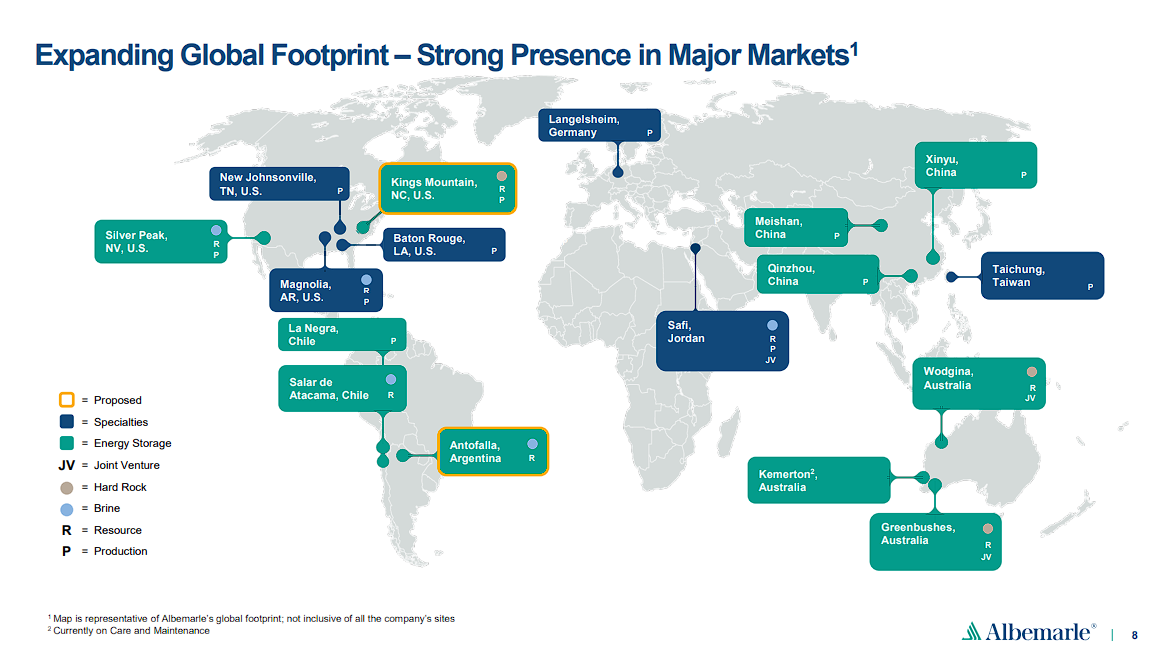
Second-quarter sales increased 31.1% to $1.74 billion, and adjusted earnings reached $3.75 per share versus $0.11 a year earlier.
Adjusted EBITDA rose 155% to $858 million as lithium pricing recovered and Specialties benefited from higher prices and volumes.
Energy Storage revenue increased 77.9%, while Specialties sales rose 20.5%.
First-half operating cash flow was approximately $1.1 billion, but cash generation benefited from the timing of Talison dividends and nonrecurring working-capital improvements.
Management reduced its 2026 capital-spending outlook to approximately $500 million and expects limited full-year volume impact from the Talison CGP3 fire because Wodgina output can help offset the disruption.
The sale of a 51% stake in Ketjen’s refining-catalyst business further simplified the portfolio.
In September, Albemarle named Ragnar Udd its next chief executive, effective February 1st, 2027, with Kent Masters becoming executive chairman.
The quarterly dividend increased 1.2% to $0.41 in July, or $1.64 annualized.
Albemarle has increased its annual dividend for 30 consecutive years and has a modest projected payout ratio.
However, lithium-price volatility and the substantial valuation-recovery assumption make its leading expected return especially sensitive to the commodity cycle.
Deep Dive: Click here to download (for free) our most recent 3-Page Sure Analysis PDF report on ALB.
Final Thoughts
These 10 companies combine at least a quarter-century of dividend growth with the highest Dividend Risk Score in our Sure Analysis Research Database.
Their records span very different economic environments, which is meaningful evidence of durable business models and shareholder-friendly capital allocation.
The return cases vary.
FactSet and Thomson Reuters provide recurring data and business-services revenue, while Stryker and Badger Meter offer exposure to medical technology and water infrastructure.
PepsiCo adds defensive consumer-staples income and H2O America provides regulated water-utility exposure, while PPG and Stepan provide industrial and materials exposure.
Brown & Brown offers an asset-light insurance model, and Albemarle supplies more cyclical lithium-recovery potential.
We estimate that Albemarle has the highest five-year annual return potential, followed by FactSet and Stryker.
Those estimates should not be treated as guarantees, particularly where valuation recovery or commodity pricing contributes meaningfully to the outlook.
We also recommend you distinguish dividend safety from current yield, as several of the strongest businesses in this group offer modest starting income.
The best choice will therefore depend on whether you prioritize present income, dividend growth, business stability, or greater upside with more operating cyclicality.
Other Sure Dividend Resources
- Dividend Kings: 50+ years of rising dividends
- Dividend Champions: 25+ years of rising dividends
- Dividend Aristocrats: 25+ years of rising dividends and in the S&P 500
- High Dividend Stocks: 4%+ dividend yields
- Monthly Dividend Stocks: Individual securities that pay out every month
- Royalty Stocks: Detailed royalty stocks list
- MLPs: Detailed MLP list
- REITs: Detailed REIT list
- BDCs: Detailed BDC list