Updated on September 18th, 2026 by Nikolaos Sismanis
High dividend stocks are attractive for income investors. With the S&P 500 average yield at just ~1.0%, it has gotten harder to find suitable yields in the stock market.
Fortunately, there are still plenty of quality high dividend stocks to choose from. With that in mind, we have created a free list of over 100 high dividend stocks with dividend yields above 4% that we cover in the Sure Analysis Research Database, along with metrics that matter like:
- % Fair Value
- Dividend Yield
- Dividend Risk Score
- Buy/Hold/Sell Recommendation
- And many more
You can download your copy of the high dividend stocks list below:
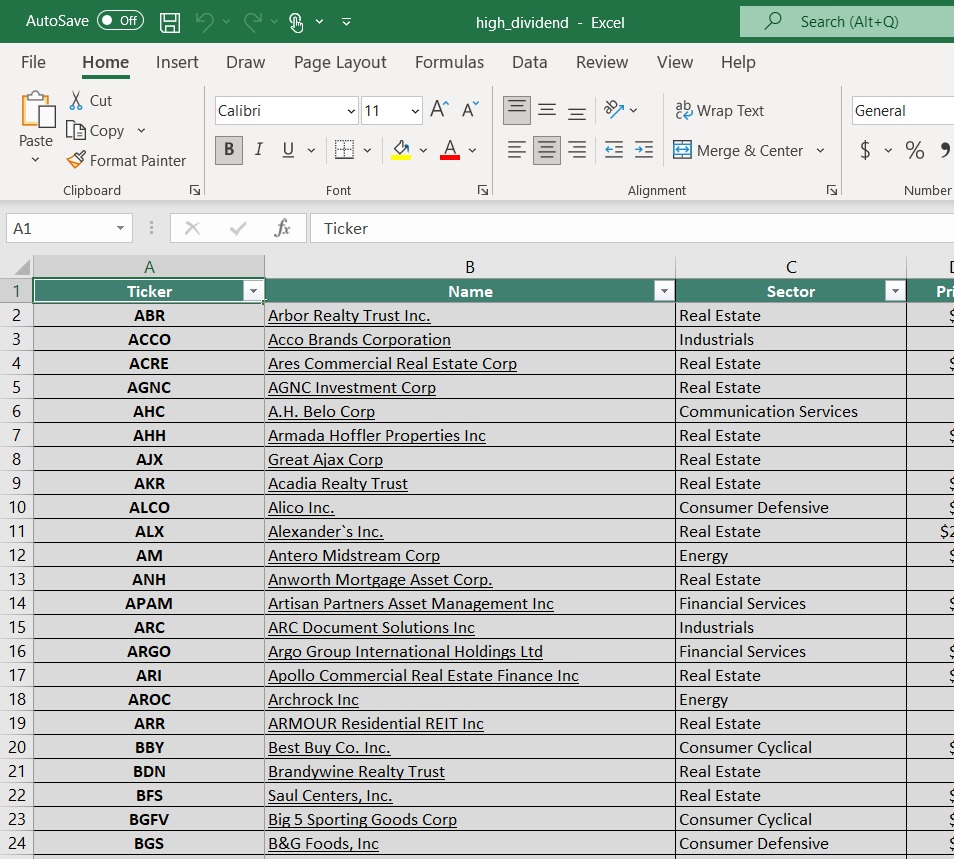
However, investors should remember that extremely high yields can be deceiving. There are many examples of high dividend stocks reducing or eliminating their dividends.
As a result, investors should look for high dividend stocks that also have sustainable payouts. This means investors will receive the benefits of high income for many years.
The 10 high dividend stocks below were found based on a qualitative assessment of their individual business models and future growth prospects.
Table of Contents
- High Dividend Stock For The Long Run: Kimberly-Clark Corporation (KMB)
- High Dividend Stock For The Long Run: T. Rowe Price Group, Inc. (TROW)
- High Dividend Stock For The Long Run: Hormel Foods Corporation (HRL)
- High Dividend Stock For The Long Run: Fidelity National Financial, Inc. (FNF)
- High Dividend Stock For The Long Run: PepsiCo, Inc. (PEP)
- High Dividend Stock For The Long Run: Sonoco Products Company (SON)
- High Dividend Stock For The Long Run: Portland General Electric Company (POR)
- High Dividend Stock For The Long Run: Comcast Corporation (CMCSA)
- High Dividend Stock For The Long Run: Eversource Energy (ES)
- High Dividend Stock For The Long Run: The Clorox Company (CLX)
- Final Thoughts
High Dividend Stock For The Long Run: Kimberly-Clark Corporation (KMB)
- Dividend Yield: 5.2%
Kimberly-Clark Corporation sells essential personal-care and tissue products under brands including Huggies, Kleenex, Scott, Cottonelle, and Kotex, creating repeat demand across economic cycles.
Second-quarter 2026 continuing-operations sales increased 0.6% to $4.2 billion, while organic sales were approximately flat as a social-media disruption involving Huggies in China reduced companywide organic growth by about 50 basis points.
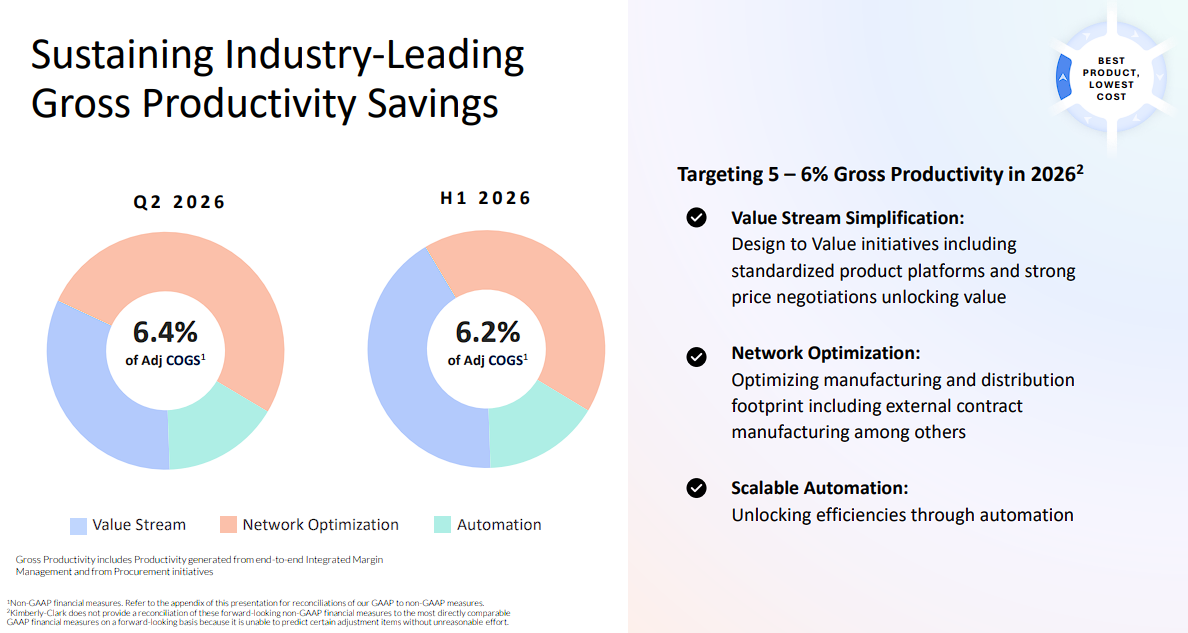
Adjusted operating profit rose 6.2% to $757 million, and adjusted earnings per share from continuing operations advanced 10.4% to $1.80 as productivity and cost savings offset muted volume.
Management still expects adjusted operating profit to grow at a mid-single-digit rate in constant currency for 2026, despite incorporating the disruption in China into its outlook.
The most important development remains the pending Kenvue acquisition, which would add Tylenol, Listerine, and Neutrogena and materially expand Kimberly-Clark’s consumer-health exposure, but would also introduce substantial integration and financing risk.
Kimberly-Clark has increased its dividend for 54 consecutive years, placing it among the Dividend Kings, and its annualized payout of $5.12 per share now produces a 5.2% yield.
Defensive brands, improving profitability, and a historically elevated yield support the long-term income case, while the Kenvue transaction and the recovery of organic growth are the central issues for investors to monitor.
High Dividend Stock For The Long Run: T. Rowe Price Group, Inc. (TROW)
- Dividend Yield: 5.1%
T. Rowe Price Group, Inc. is a global asset manager offering mutual funds, exchange-traded funds, subadvisory services, separate accounts, and retirement solutions to individuals and institutions.
Second-quarter 2026 revenue increased 10.7% to $1.91 billion, while adjusted earnings per share rose 14.7% to $2.57 and adjusted operating income advanced 15.4% to $709.1 million.
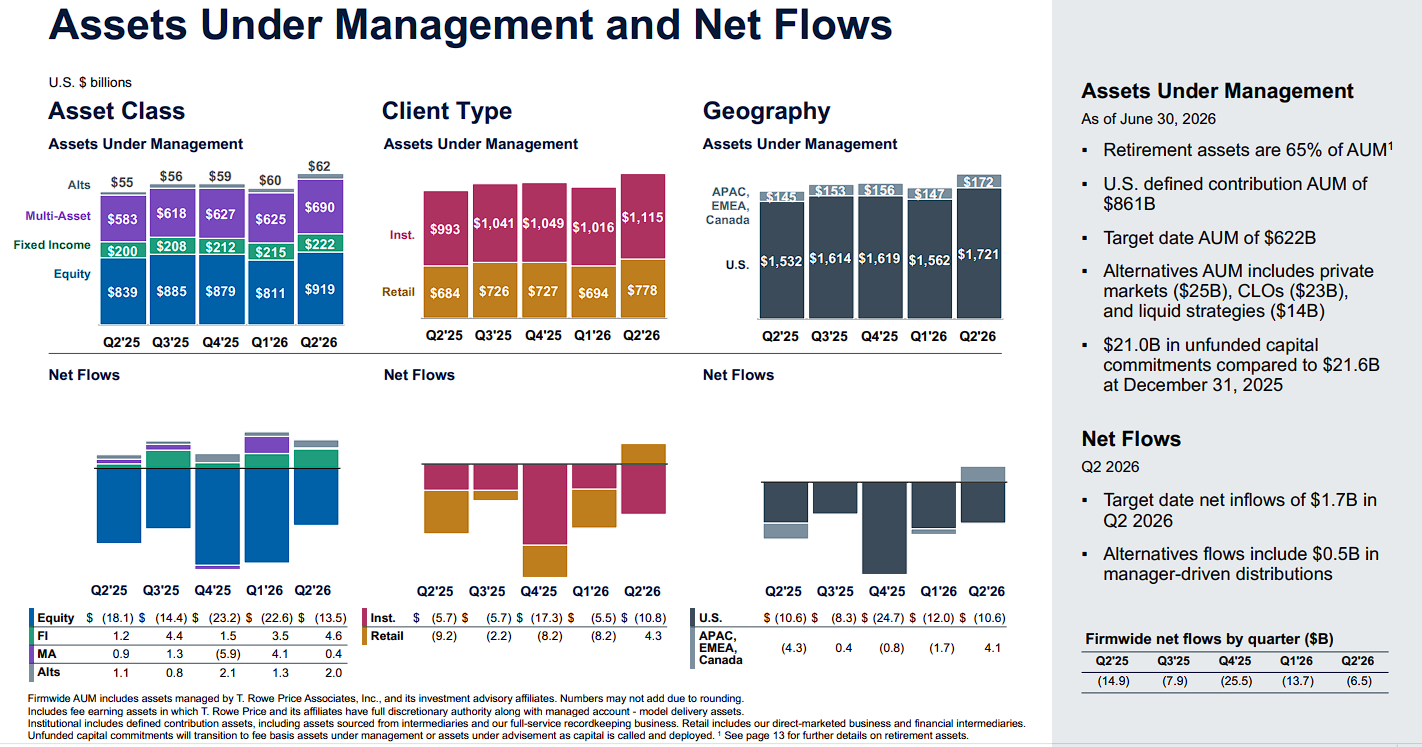
Assets under management ended June at $1.89 trillion, up 12.9% year over year, as market appreciation more than offset $6.5 billion of net client outflows during the quarter.
T. Rowe Price continues to broaden its lineup, including the September launch of three additional actively managed equity ETFs, as it adapts to investors’ shift toward lower-cost and exchange-traded products.
The company raised its quarterly dividend 2.4% to $1.30 in February, extending its dividend-growth streak to 40 consecutive years, and the $5.20 annualized payout now yields 5.1%.
The dividend consumes approximately half of our 2026 earnings estimate, and the company’s debt-free balance sheet provides additional protection during weaker markets.
Long-term results will remain sensitive to market values, investment performance, fee pressure, and persistent industry outflows, but the sizable asset base, strong finances, and four-decade dividend record make T. Rowe Price a compelling high-income candidate.
High Dividend Stock For The Long Run: Hormel Foods Corporation (HRL)
- Dividend Yield: 5.6%
Hormel Foods Corporation owns a broad portfolio of branded foods, including SPAM, Skippy, Applegate, Jennie-O, Planters, and numerous refrigerated and foodservice products sold in the United States and abroad.
Fiscal third-quarter 2026 sales declined 2.3% to $2.96 billion, while adjusted earnings per share reached $0.37 as cautious consumers and recent portfolio changes weighed on the top line.
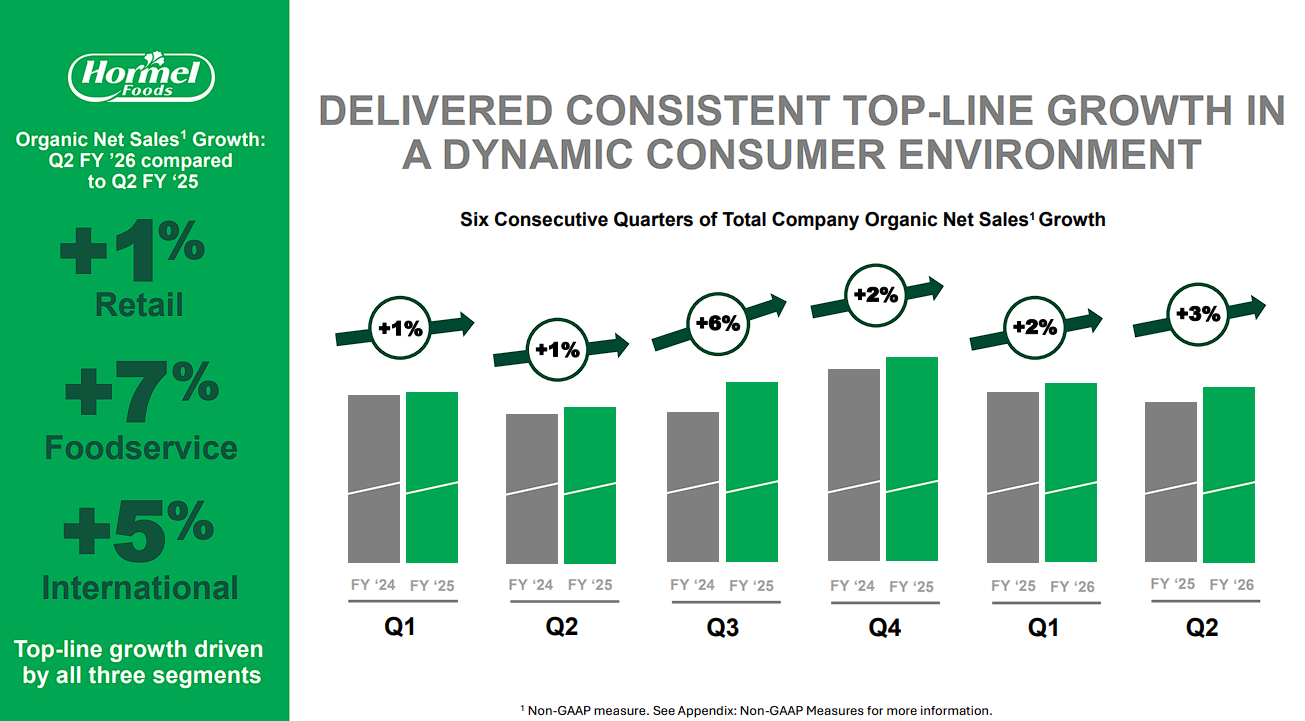
Adjusted operating margin improved 60 basis points to 9.0%, providing evidence that productivity efforts and a more favorable cost environment are helping offset weaker volumes.
Operating cash flow increased 54% to $241 million, and Hormel returned $161 million to shareholders through dividends during the quarter.
The company has simplified its portfolio through the sale of its Ceratti business in Brazil and the exits from whole-bird turkey and private-label snack nuts, allowing greater focus on branded, value-added categories.
Hormel has increased its dividend for 60 consecutive years, one of the longest records in the market, and its annualized payout of $1.17 per share now yields 5.6%.
The starting income and brand portfolio are attractive, but a relatively high payout ratio means that sustained margin recovery, renewed organic growth, and disciplined capital allocation will be important to future dividend increases.
High Dividend Stock For The Long Run: Fidelity National Financial, Inc. (FNF)
- Dividend Yield: 4.8%
Fidelity National Financial, Inc. is the largest U.S. title insurer and owns a controlling interest in F&G Annuities & Life, providing exposure to housing transactions, annuities, and investment income.
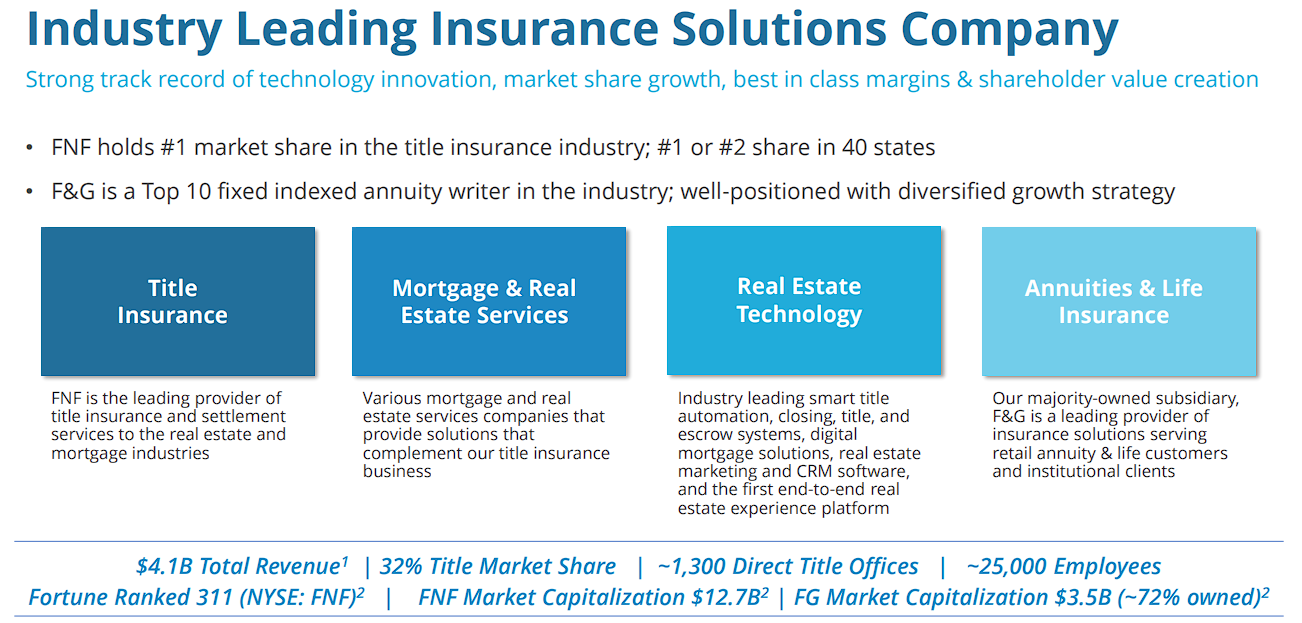
Second-quarter 2026 net earnings were $288 million, or $1.08 per share, compared with $278 million, or $1.02 per share, in the prior-year period.
Adjusted net earnings improved to $370 million, or $1.39 per share, from $318 million, or $1.16 per share.
Title-segment revenue excluding recognized gains and losses rose 16% to $2.5 billion, while the adjusted pretax title margin expanded to 17.8% from 15.5% as commercial, purchase, and refinance activity all improved.
F&G ended the quarter with $74.7 billion of assets under management before reinsurance and generated $2.7 billion of gross sales, adding an earnings stream that is not perfectly correlated with title volumes.
Management is also embedding automation and artificial intelligence into title workflows to improve efficiency and strengthen fraud prevention.
Fidelity National returned $195 million to shareholders through dividends and repurchases during the quarter.
Its $2.08 annualized dividend now yields 4.8%, and the company has raised its regular payout for 14 consecutive years.
Housing activity remains cyclical, but market leadership, strong title margins, conservative dividend coverage, and F&G diversification support the longer-term income case.
High Dividend Stock For The Long Run: PepsiCo, Inc. (PEP)
- Dividend Yield: 4.4%
PepsiCo, Inc. is a global food-and-beverage leader whose portfolio includes Pepsi, Gatorade, Mountain Dew, Lay’s, Doritos, Quaker, and many other billion-dollar brands.
Its combination of convenient foods and beverages, extensive distribution, and international scale has historically produced resilient cash flow across economic cycles.
Second-quarter 2026 net revenue rose 6.4% to $24.18 billion, while organic revenue increased 2.4% and core earnings per share advanced 4% to $2.20.
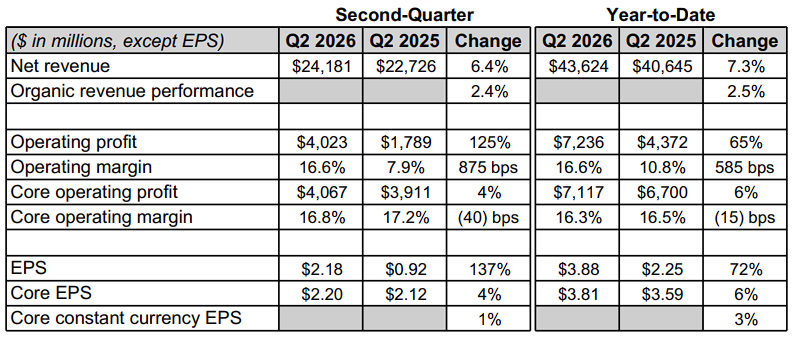
Performance was strongest internationally, whereas PepsiCo Foods North America revenue declined 2% and North American beverage volumes remained under pressure, showing that domestic affordability and consumer demand are still meaningful challenges.
Management reaffirmed its 2026 outlook, implying 4% to 6% net-revenue growth and 5% to 7% core earnings-per-share growth.
The company is supporting that outlook by restaging major brands, expanding functional and better-for-you products, sharpening value propositions, and pursuing productivity savings.
PepsiCo raised its annualized dividend 4% to $5.92 per share in 2026, extending its dividend-growth streak to 54 consecutive years and retaining its Dividend King status.
The shares now yield 4.4%, well above PepsiCo’s historical norm, which improves the starting income proposition.
Long-term results should depend on renewed North American volume growth and continued international expansion, while the company’s brands and distribution network remain major competitive strengths.
Deep Dive: Click here to download (for free) our most recent 3-Page Sure Analysis PDF report on PepsiCo, Inc. (PEP).
High Dividend Stock For The Long Run: Sonoco Products Company (SON)
- Dividend Yield: 4.4%
Sonoco Products Company supplies consumer and industrial packaging across food, beverage, household, construction, and other end markets, creating a diversified base of demand.
Second-quarter 2026 sales were $1.89 billion, down approximately 1%, while adjusted earnings per share increased 10.2% to $1.51 and exceeded the prior-year result of $1.37.
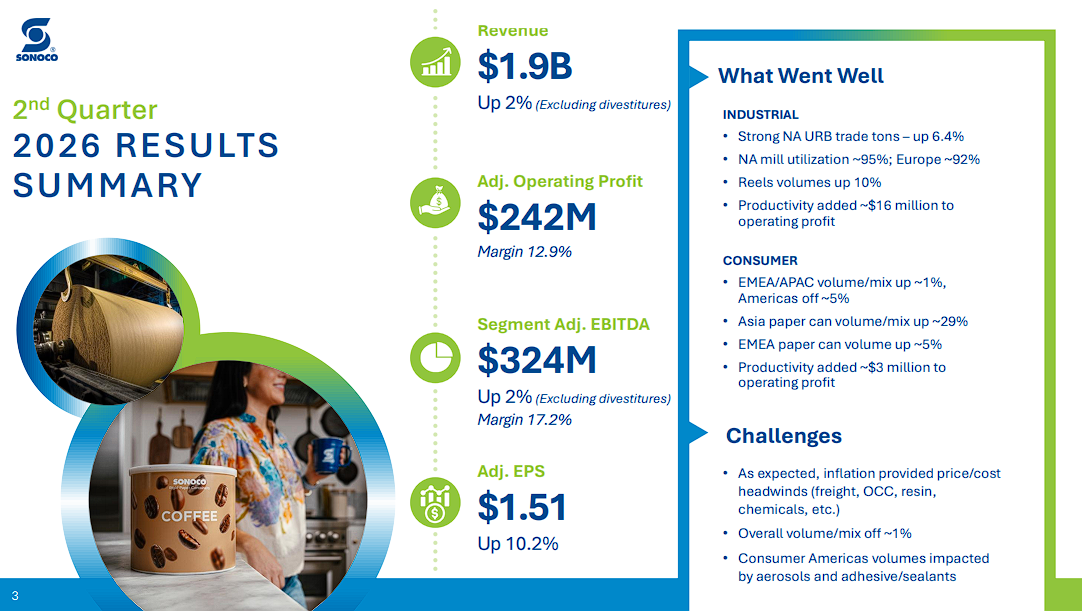
Consumer Packaging sales increased 1.2%, and Industrial Paper Packaging sales rose 4.2%, although softer volumes and tariff-related costs continued to pressure parts of the portfolio.
Operating cash flow reached a second-quarter record of $301 million, with free cash flow of $237 million, giving Sonoco additional capacity to reduce debt after its acquisition-led portfolio transformation.
The company continues integrating Eviosys after divesting its Thermoformed and Flexibles Packaging and ThermoSafe operations, leaving a more focused business but also meaningful execution and leverage considerations.
Management maintained its 2026 adjusted earnings guidance of $5.80 to $6.20 per share, while indicating results may finish near the lower end of that range.
Sonoco raised its quarterly dividend 1.9% to $0.54 in April, extending its dividend-growth streak to 50 consecutive years, and its $2.16 annualized payout yields 4.4%.
The low payout ratio, resilient packaging demand, and improving cash generation support the income case, while Eviosys integration, debt reduction, and volume trends remain the main items to watch.
High Dividend Stock For The Long Run: Portland General Electric Company (POR)
- Dividend Yield: 4.6%
Portland General Electric Company is a regulated electric utility serving Oregon, where electrification and data-center development are supporting power demand and infrastructure investment.
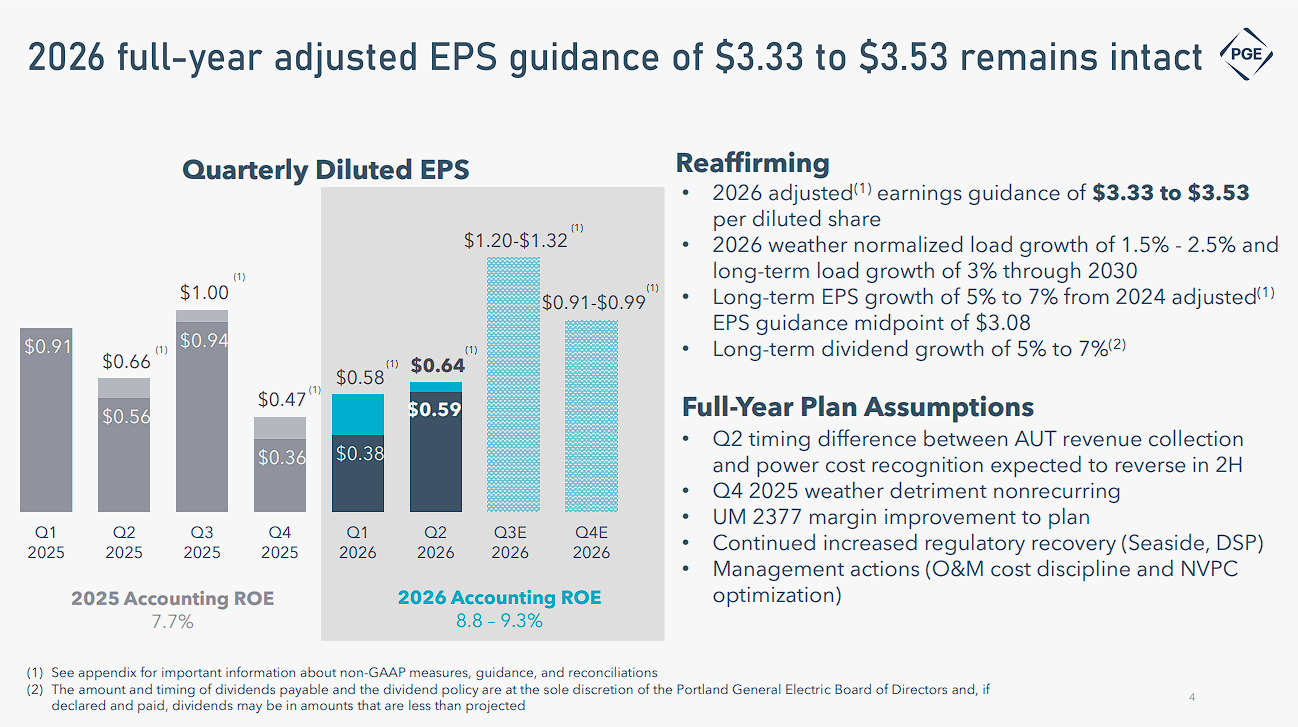
Second-quarter 2026 net income was $68 million, or $0.59 per diluted share, compared with $62 million, or $0.56 per share, one year earlier.
Adjusted earnings were $74 million, or $0.64 per share, versus $73 million, or $0.66 per share, as a larger share count offset modest income growth.
Industrial demand increased 11.2%, led by high-tech and data-center customers, highlighting a source of long-term growth.
The company reaffirmed adjusted 2026 earnings guidance of $3.33 to $3.53 per share.
A new large-load tariff took effect in July and is designed to assign more of the infrastructure costs and risks created by very large customers to those customers, while lowering rates for other groups.
Portland General is also advancing its proposed acquisition of utility operations and selected assets in Washington, which could expand its customer base but will require regulatory approval and financing.
The quarterly dividend is $0.55125 per share, or $2.205 annually, for a 4.6% yield, and the company has increased its dividend for 20 consecutive years.
Its regulated model and demand growth support the income thesis, while wildfire exposure, capital needs, dilution, and regulatory outcomes remain key risks.
High Dividend Stock For The Long Run: Comcast Corporation (CMCSA)
- Dividend Yield: 5.7%
Comcast Corporation combines broadband, wireless, business connectivity, media, studios, streaming, and theme parks, giving it several sources of cash flow despite continuing pressure on traditional cable products.
Second-quarter 2026 revenue declined 1.2% to $29.94 billion, while adjusted earnings per share fell 16.7% to $1.04 and adjusted EBITDA decreased 13.4% to $8.9 billion.
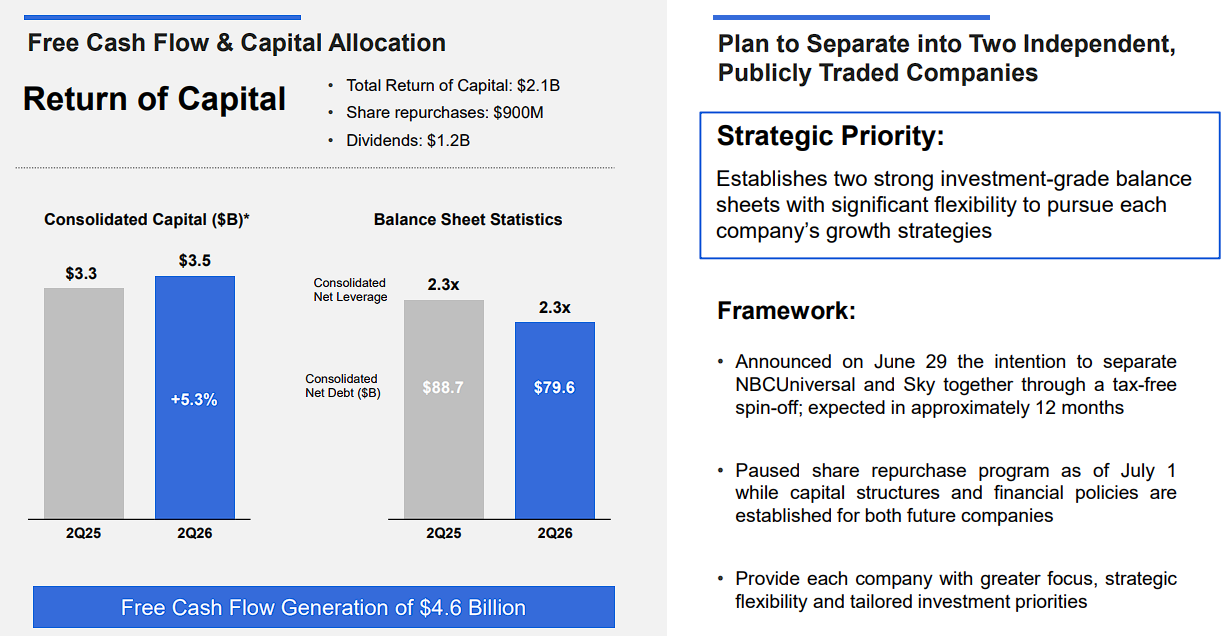
The quarter nevertheless produced $4.6 billion of free cash flow, and Comcast returned $2.1 billion to shareholders through $1.2 billion of dividends and $900 million of share repurchases.
Domestic broadband customers declined by 167,000, but wireless additions reached a record 448,000 and total wireless lines surpassed 10 million, showing progress in Comcast’s strategy of bundling connectivity services.
Peacock achieved quarterly profitability for the first time, generating $189 million of EBITDA as paid subscribers reached 48 million.
The completed Versant separation and the planned separation of NBCUniversal and Sky represent major strategic changes, while Comcast has paused repurchases as it works through the next transaction.
Comcast has increased its dividend for 17 consecutive years, and the $1.32 annualized payout yields 5.7% while consuming only about 38% of our 2026 earnings estimate.
The low payout ratio and free cash flow protect the dividend, but broadband competition, business separation execution, and the future earnings base require close attention.
High Dividend Stock For The Long Run: Eversource Energy (ES)
- Dividend Yield: 4.6%
Eversource Energy is a regulated utility serving electric and natural-gas customers across New England, with earnings primarily supported by rate-regulated transmission and distribution investment.
Second-quarter 2026 GAAP earnings were $53.7 million, or $0.14 per share, compared with $352.7 million, or $0.96 per share, in the prior-year period.
The decline largely reflected special items, including an after-tax charge tied to the completed Aquarion Water sale and an offshore-wind contingent liability.
Excluding those items, recurring earnings were $329.1 million, or $0.87 per share, and recurring first-half earnings reached $2.60 per share.
Eversource reaffirmed 2026 recurring earnings guidance of $4.57 to $4.72 per share and continues to target 5% to 7% annual recurring earnings growth through 2030.
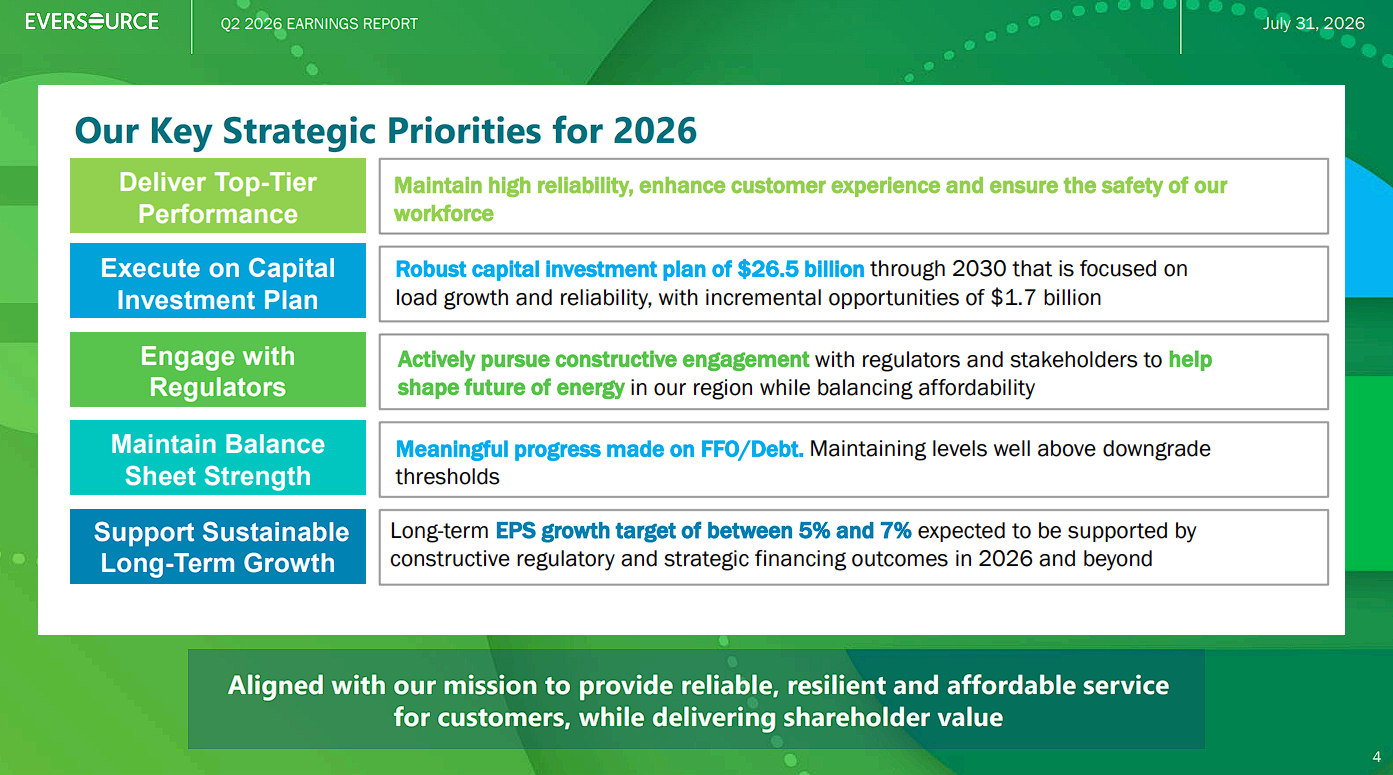
Completing the Aquarion sale simplifies Eversource into a more focused regulated electric-and-gas delivery company and supplies capital for its sizable infrastructure program.
Distribution earnings benefited from rate increases and investment, although lower transmission returns and interest expense remain headwinds.
Eversource pays $3.15 per share annually, yields 4.6%, and has increased its dividend for 28 consecutive years.
The regulated asset base and growth plan support long-term income, while regulatory decisions, financing costs, and capital-plan execution will shape future dividend growth.
Deep Dive: Click here to download (for free) our most recent 3-Page Sure Analysis PDF report on Eversource Energy (ES).
High Dividend Stock For The Long Run: The Clorox Company (CLX)
- Dividend Yield: 5.9%
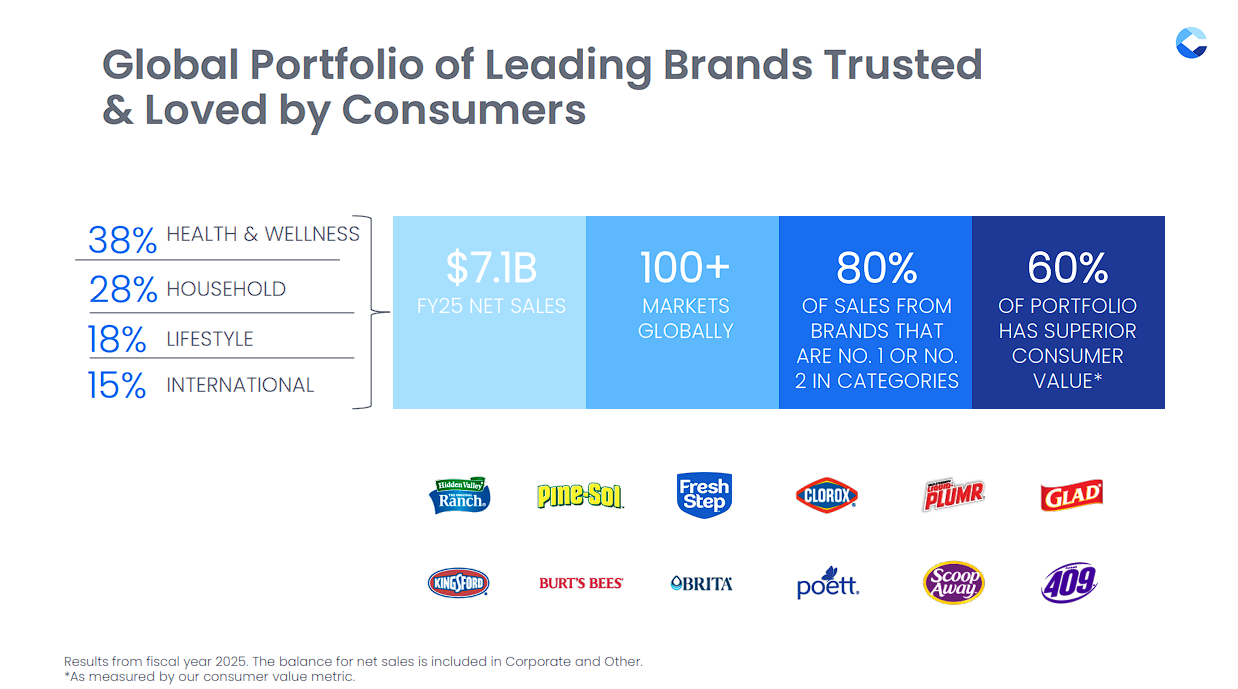
The Clorox Company owns a portfolio of household and professional brands, including Clorox, Pine-Sol, Glad, Kingsford, Brita, Hidden Valley, Burt’s Bees, and Purell.
Fiscal fourth-quarter 2026 sales declined 2% to $1.95 billion, while organic sales fell 13% because the prior-year quarter included substantial retailer inventory shipments ahead of the enterprise-resource-planning transition.
Adjusted earnings per share fell 42% to $1.66, and gross margin contracted 520 basis points to 41.3% as unfavorable comparisons, costs, and business disruption weighed on results.
For the full year, sales declined 5% to $6.72 billion and adjusted earnings were $5.53 per share, although operating cash flow remained positive at $612 million.
Clorox completed its U.S. ERP implementation and closed the acquisition of GOJO Industries, which now operates as Clorox Purell and adds a portfolio of health-and-hygiene products.
Management expects fiscal 2027 sales to grow 13% to 14%, organic sales to rise 3.5% to 4.5%, and adjusted earnings to reach $5.70 to $6.00 per share as comparisons normalize and GOJO contributes.
Clorox lifted its quarterly dividend to $1.25, extending its growth streak to 49 years, and the $5.00 annualized payout yields 5.9%.
The brands are defensive, but investors should monitor the elevated payout ratio, GOJO integration, cost pressures, and the durability of the earnings recovery.
Final Thoughts
These 10 companies offer yields between 4.4% and 5.9%, but their long-term appeal rests on more than today’s income.
PepsiCo, Kimberly-Clark, Hormel, Sonoco, and Clorox have dividend records spanning roughly five decades or more.
Meanwhile, Portland General Electric and Eversource provide regulated-utility exposure, while T. Rowe Price, Fidelity National Financial, and Comcast add financial and communication-services diversification.
The list also shows why company-specific risks still matter, as Kimberly-Clark must execute a transformative acquisition, Comcast is reshaping its portfolio, and Hormel and Clorox are working through earnings-recovery periods.
At reasonable valuations, businesses that can protect their competitive positions, cover their payouts, and keep earnings moving higher have a better chance of turning an elevated starting yield into attractive income and total returns over the next decade.
Additional Reading
If you are interested in finding high-quality dividend growth stocks and/or other high-yield securities and income securities, the following Sure Dividend resources will be useful:
Other Sure Dividend Resources
- Dividend Kings: 50+ years of rising dividends
- Dividend Champions: 25+ years of rising dividends
- Dividend Aristocrats: 25+ years of rising dividends and in the S&P 500
- High Dividend Stocks: 4%+ dividend yields
- Monthly Dividend Stocks: Individual securities that pay out every month
- MLPs: List of MLPs and more
- REITs: List of REITs and more
- BDCs: List of BDCs and more