Updated on September 9th, 2026 by Nikolaos Sismanis
Water is one of the basic necessities of human life. Life as we know it cannot exist without water. This makes water truly essential.
It is only natural for investors to consider purchasing water stocks.
In all, we have compiled a list of over 40 stocks that are in the business of water. The list is derived from the holdings of of the top water industry exchange-traded funds:
You can download a spreadsheet with all 43 water stocks (along with metrics that matter like price-to-earnings ratios and dividend yields) by clicking on the link below:
This research report covers our top 10 water stocks today. The criteria are as follows:
- Is in the water stocks spreadsheet
- Is in the Sure Analysis Research Database
- Sort by expected total returns
Top 10 Water Stocks Rankings
Table Of Contents
- Water Stock #10: A.O. Smith (AOS)
- Water Stock #9: Masco Corporation (MAS)
- Water Stock #8: Jacobs Solutions (J)
- Water Stock #7: Xylem Inc. (XYL)
- Water Stock #6: Pentair plc (PNR)
- Water Stock #5: Tetra Tech (TTEK)
- Water Stock #4: Advanced Drainage Systems (WMS)
- Water Stock #3: H2O America (HTO)
- Water Stock #2: Badger Meter (BMI)
- Water Stock #1: Stantec Inc. (STN)
Water Stock #10: A.O. Smith (AOS)
- 5-year expected annual returns: 11.7%
A.O. Smith is a leading manufacturer of residential and commercial water heaters, boilers, and water-treatment products.
North America supplies most of its earnings and benefits from replacement demand, while China, India, and other international markets provide longer-term growth opportunities but add more volatility.
Second-quarter 2026 sales slipped 1% to $1.00 billion.
Adjusted earnings per share declined 4% to $1.03.
North American sales increased 5% to $820.5 million, supported by the Leonard Valve acquisition, 21% boiler growth, and pricing, partly offset by softer residential water-heater volumes.
Rest of World sales fell 19%, including a 28% local-currency decline in China, where consumer demand remained weak.
A.O. Smith is restructuring its North American water-treatment operations through footprint optimization and brand rationalization.
The company recorded $22.6 million of related second-quarter charges and expects $6 million to $8 million of annual savings beginning in 2027.
Management narrowed 2026 adjusted earnings-per-share guidance to $3.70 to $3.85.
Management also increased the share-repurchase target to $300 million after first-half free cash flow rose 67% to $233 million.
The quarterly dividend is $0.36 per share, and A.O. Smith has increased its payout for 32 consecutive years.
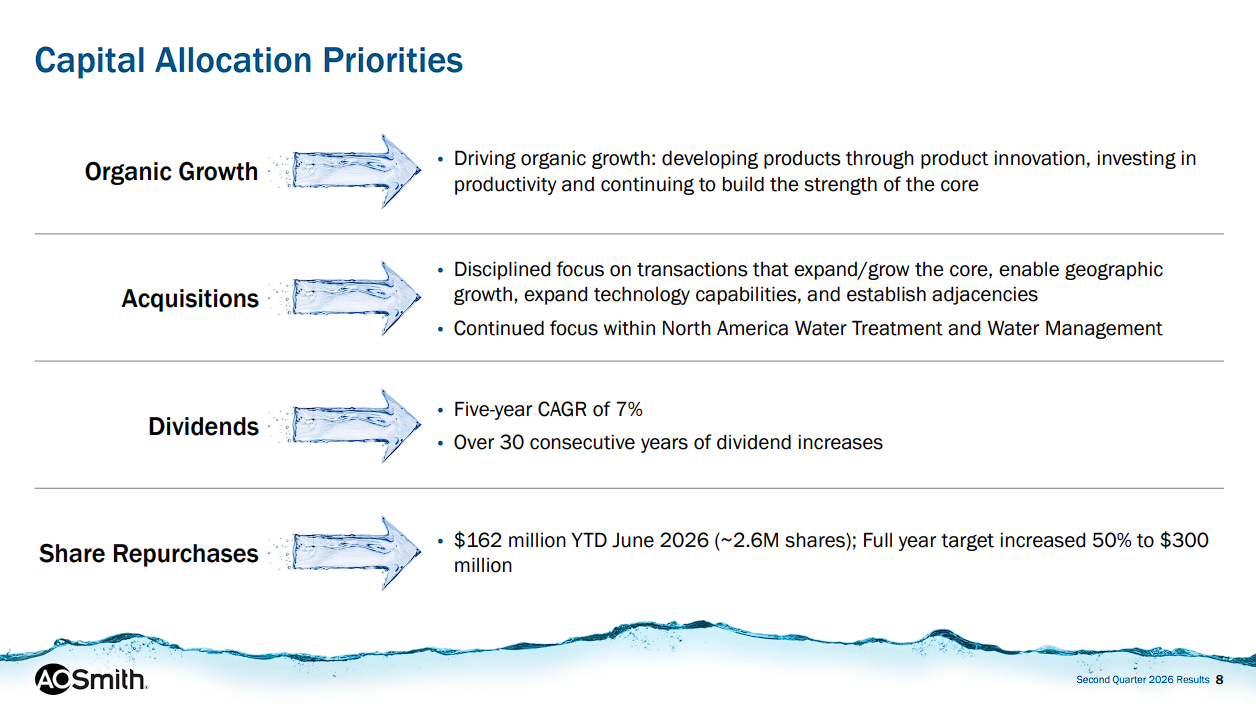
With a payout ratio near 37%, the dividend remains well covered despite current demand pressure.
Deep Dive: Click here to download (for free) our most recent 3-Page Sure Analysis PDF report on A.O. Smith (AOS).
Water Stock #9: Masco Corporation (MAS)
- 5-year expected annual returns: 12.1%
Masco Corporation manufactures branded home-improvement and building products.
Its water exposure comes primarily from plumbing brands such as Delta and hansgrohe, while Behr paint and other decorative products broaden the portfolio.
Demand is tied largely to repair-and-remodel activity, giving Masco attractive replacement exposure but also some sensitivity to housing conditions.
Masco reported second-quarter 2026 net sales of $1.99 billion, down 3% year-over-year.
Plumbing Products sales declined 3%, while Decorative Architectural Products sales fell 4%.
Profitability was much stronger, as adjusted operating margin expanded 410 basis points to 24.2%, and adjusted earnings per share increased 26% to $1.64.
A roughly $95 million net benefit from tariff refunds contributed to the improvement, alongside disciplined execution and cost control.
Management raised its 2026 adjusted earnings-per-share outlook to $4.40 to $4.60, reflecting an expected full-year tariff-refund benefit of about $85 million.
The underlying operating outlook was largely unchanged, so investors should distinguish this temporary benefit from sustainable earnings growth.
Masco nevertheless has powerful brands, ample liquidity, and a shareholder-friendly capital-allocation policy.
It returned $454 million through dividends and repurchases during the quarter.
The $0.32 quarterly dividend represents a 13-year growth streak, while the payout ratio of roughly 30% leaves room for further increases.
Deep Dive: Click here to download (for free) our most recent 3-Page Sure Analysis PDF report on Masco Corporation (MAS).
Water Stock #8: Jacobs Solutions (J)
- 5-year expected annual returns: 12.7%
Jacobs Solutions is a global consulting and engineering company serving infrastructure, advanced manufacturing, energy, environmental, transportation, and water markets.
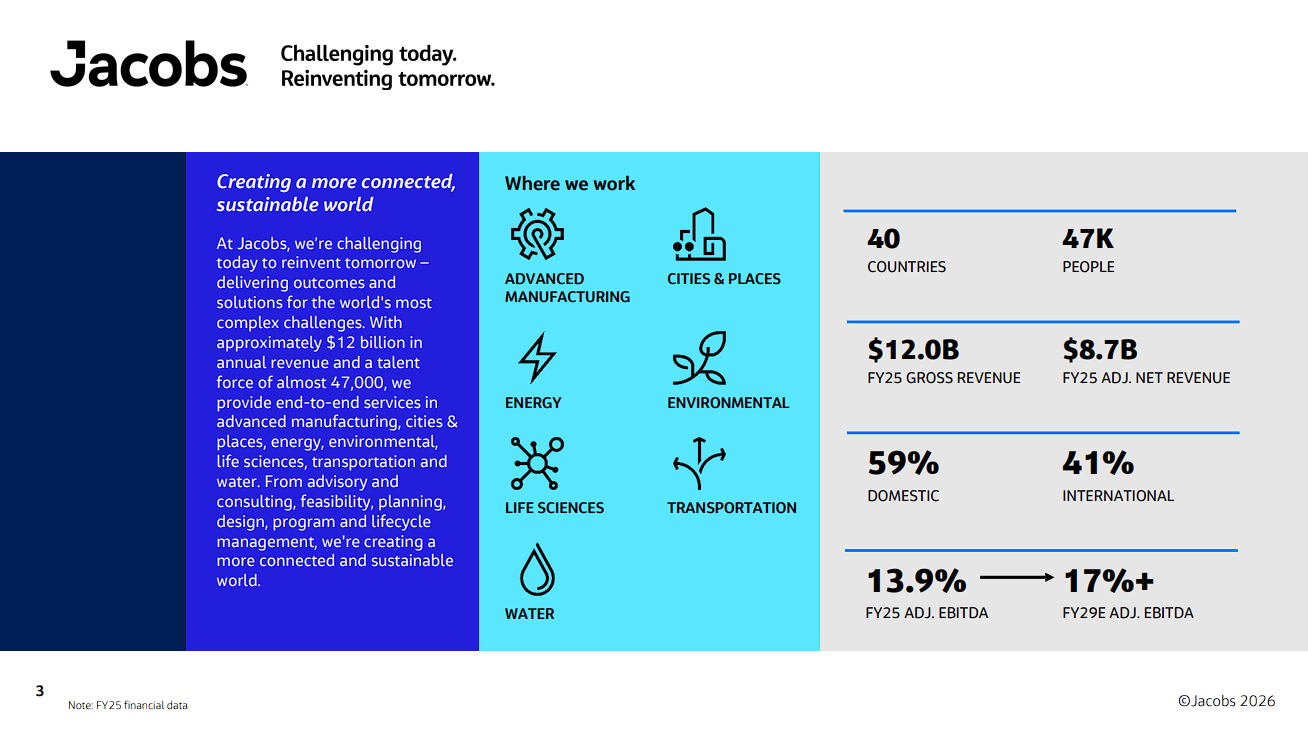
The company combines technical design and program management through Infrastructure & Advanced Facilities with higher-value advisory and digital capabilities from PA Consulting.
In the fiscal third quarter ended June 26, 2026, gross revenue rose 34.5% to $4.08 billion and adjusted net revenue increased 8.3% to $2.42 billion.
Adjusted earnings-per-share grew 13.6% to $1.84, while backlog reached a record $28.9 billion, up 27% year-over-year.
Growth in Infrastructure & Advanced Facilities was broad-based, with data centers, semiconductors, energy and power, transportation, and water among the leading end markets.
Jacobs raised its fiscal 2026 outlook for the third consecutive quarter.
It now expects adjusted net revenue growth of 9.5% to 10.0% and adjusted earnings-per-share of $7.20 to $7.30.
The integration of the remaining PA Consulting stake is strengthening the company’s consulting mix.
Also, $456 million of quarterly operating cash flow helped reduce leverage and supported $142 million of share repurchases.
Jacobs pays a $0.36 quarterly dividend and has increased its annual payout for eight consecutive years.
Its payout ratio is about 20%, leaving substantial capacity for dividend growth while the company funds expansion.
Deep Dive: Click here to download (for free) our most recent 3-Page Sure Analysis PDF report on Jacobs Solutions (J).
Water Stock #7: Xylem Inc. (XYL)
- 5-year expected annual returns: 12.8%
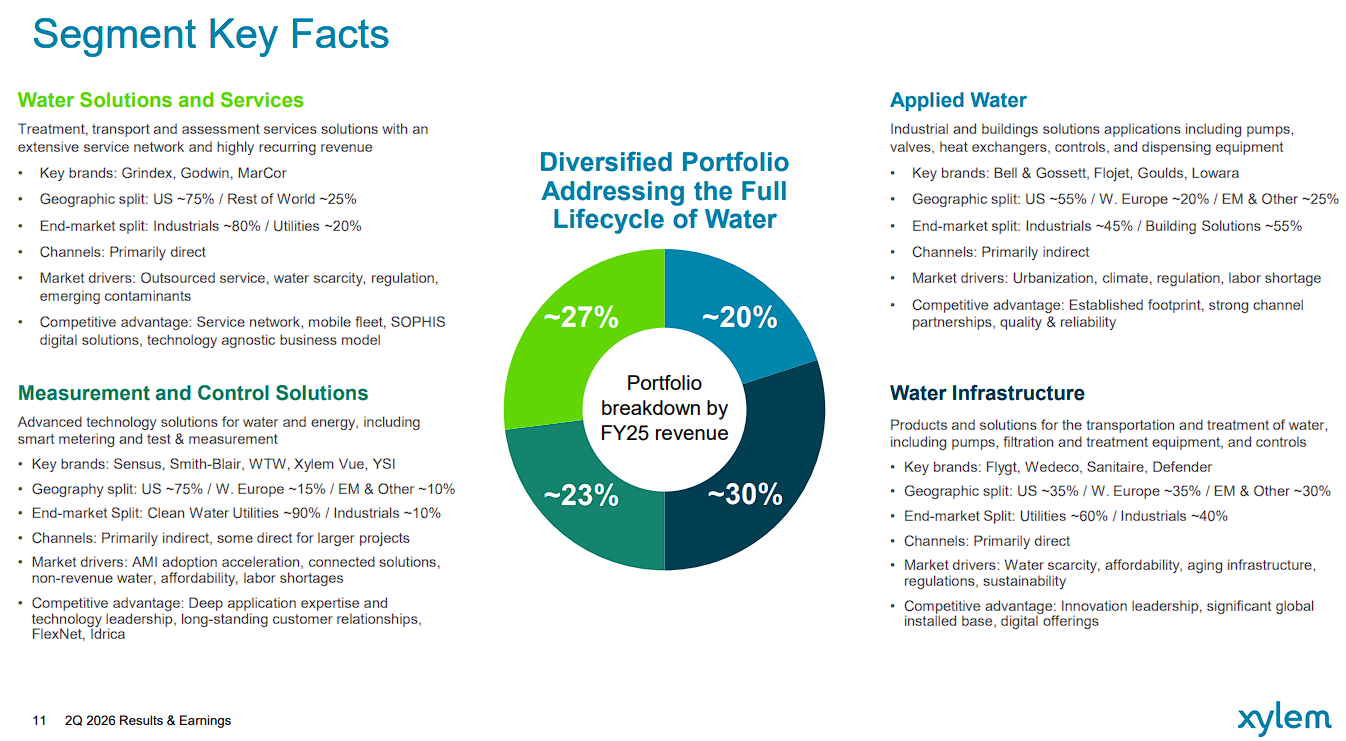
Xylem provides water and wastewater equipment, measurement systems, treatment technologies, software, and services to utilities and industrial customers worldwide.
Its portfolio includes pumps, smart meters, analytics, filtration, disinfection, and high-purity water solutions, giving it broad exposure to water scarcity, aging infrastructure, and stricter quality standards.
Second-quarter 2026 revenue increased 2% to $2.34 billion, including 1% organic growth.
Orders surged 42% to $3.1 billion, while adjusted earnings-per-share increased 16% to $1.46.
Adjusted EBITDA margin expanded 150 basis points to 23.3%, as productivity, pricing, and mix more than offset inflation and lower volumes.
Demand remains healthy across municipal markets and water-intensive industries, including semiconductors, power generation, mining, food and beverage, and life sciences.
Management now expects approximately $9.2 billion of 2026 revenue and raised adjusted earnings-per-share guidance to $5.55 to $5.70.
The company also expects an adjusted EBITDA margin of 23.1% to 23.5% and free cash flow equal to 10.2% to 11.0% of revenue.
Xylem pays a $0.43 quarterly dividend, or $1.72 annually, and has increased its annual payout for 15 consecutive years.
The payout ratio is approximately 31%, leaving room for continued dividend growth while management invests in innovation and bolt-on acquisitions.
The main risks are valuation, project timing, industrial cyclicality, and the challenge of converting unusually strong orders into profitable revenue.
Deep Dive: Click here to download (for free) our most recent 3-Page Sure Analysis PDF report on Xylem Inc. (XYL).
Water Stock #6: Pentair plc (PNR)
- 5-year expected annual returns: 13.1%
Pentair is a pure-play water solutions company operating through Flow, Water Solutions, and Pool.
Its products move, treat, and improve water for residential, commercial, industrial, and municipal customers.
The portfolio benefits from replacement demand and long-term water-efficiency needs, although Pool can experience meaningful channel-inventory swings.
Second-quarter 2026 sales fell 17% to $933 million, largely because Pool customers reduced inventory by about $170 million.
Adjusted earnings-per-share declined to $1.14 from $1.39, and adjusted operating margin was 25.4%.
Flow sales increased 5%, and segment income rose 27%, while Water Solutions sales fell 5% but segment income increased 17%.
Pool sales declined 42%, driving most of the consolidated weakness.
Pentair revised its 2026 outlook to adjusted earnings-per-share of $4.60 to $4.80 and sales down 4% to 7%.
At the same time, it agreed to acquire Taco Group Holdings for approximately $1.4 billion.
Taco generates about $540 million of annual sales and should broaden Pentair’s hydronic heating, cooling, and data-center water capabilities.
Management expects $30 million of run-rate synergies and $0.10 to $0.15 of earnings accretion in 2027, with closing targeted for the fourth quarter.
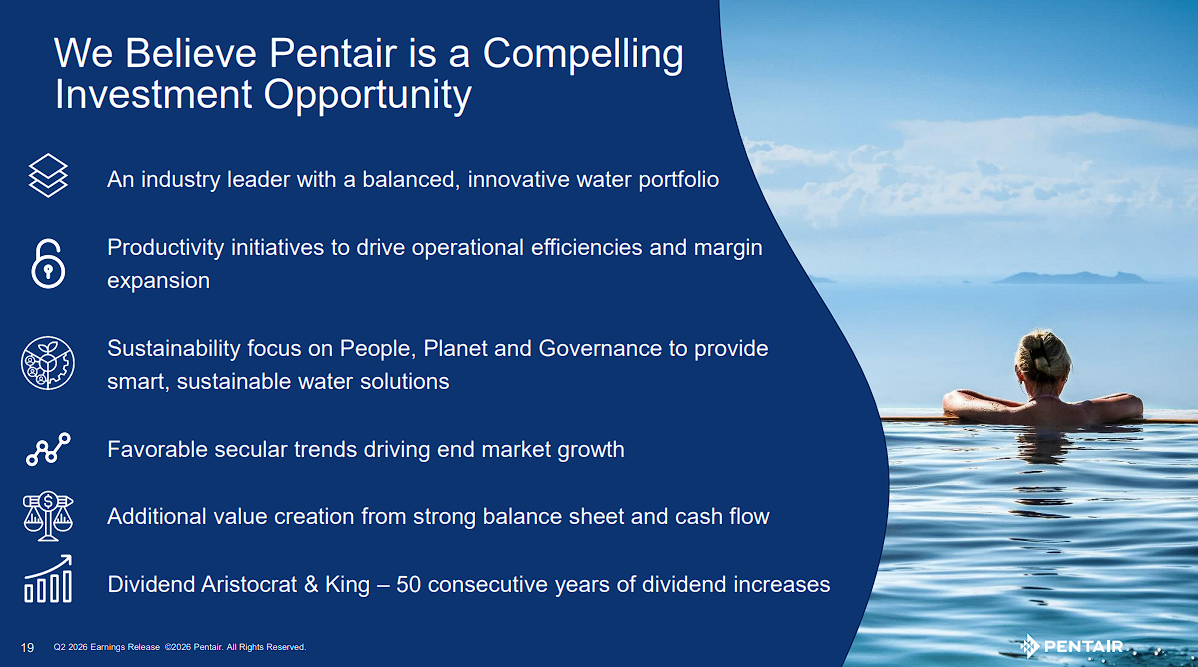
Pentair’s $0.27 quarterly dividend marks its 50th consecutive year of increases, and its payout ratio is only about 20%.
Deep Dive: Click here to download (for free) our most recent 3-Page Sure Analysis PDF report on Pentair plc (PNR).
Water Stock #5: Tetra Tech (TTEK)
- 5-year expected annual returns: 14.0%
Tetra Tech provides high-end consulting and engineering services focused on water, the environment, and sustainable infrastructure.
Its roughly 25,000 employees support government and commercial clients worldwide, giving the company exposure to long-duration spending on water quality, treatment, climate resilience, and infrastructure modernization.
In the fiscal third quarter ended June 28, 2026, revenue was $1.31 billion and net revenue was $1.11 billion.
Excluding USAID, Department of State, and episodic disaster-response work, net revenue increased 8% year-over-year.
Operating income totaled $158 million, EBITDA was $173 million, and earnings-per-share were $0.42.
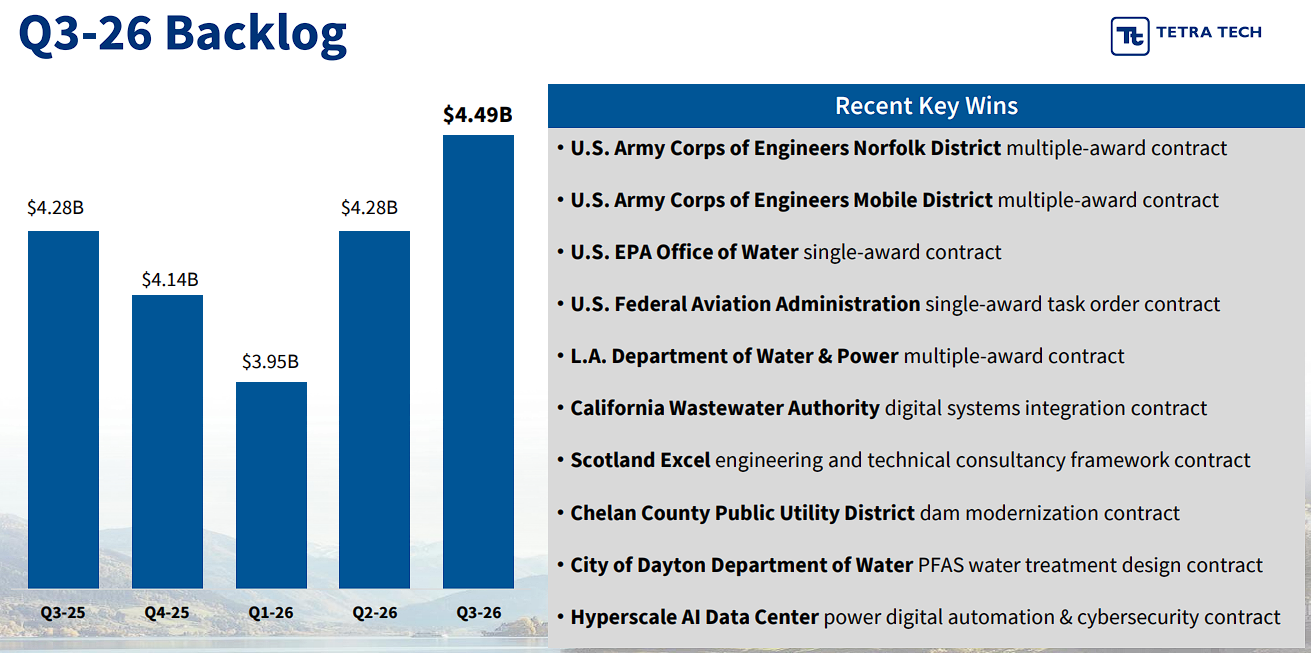
Backlog increased 5% sequentially to $4.49 billion, while quarterly operating cash flow reached $229 million.
Demand was led by double-digit growth in U.S. federal and international markets.
Recent wins included water-infrastructure work for the U.S. Army Corps of Engineers, EPA water-quality monitoring, PFAS treatment design, and digital water-system projects.
This momentum prompted Tetra Tech to raise fiscal 2026 adjusted earnings-per-share guidance to $1.56 to $1.59 and narrow net-revenue guidance to $4.315 billion to $4.365 billion.
The board declared a $0.072 quarterly dividend, up 11% year-over-year and the company’s 45th consecutive double-digit quarterly increase.
Tetra Tech has raised its annual dividend for 12 consecutive years, with a payout ratio below 20%.
Deep Dive: Click here to download (for free) our most recent 3-Page Sure Analysis PDF report on Tetra Tech (TTEK).
Water Stock #4: Advanced Drainage Systems (WMS)
- 5-year expected annual returns: 14.3%
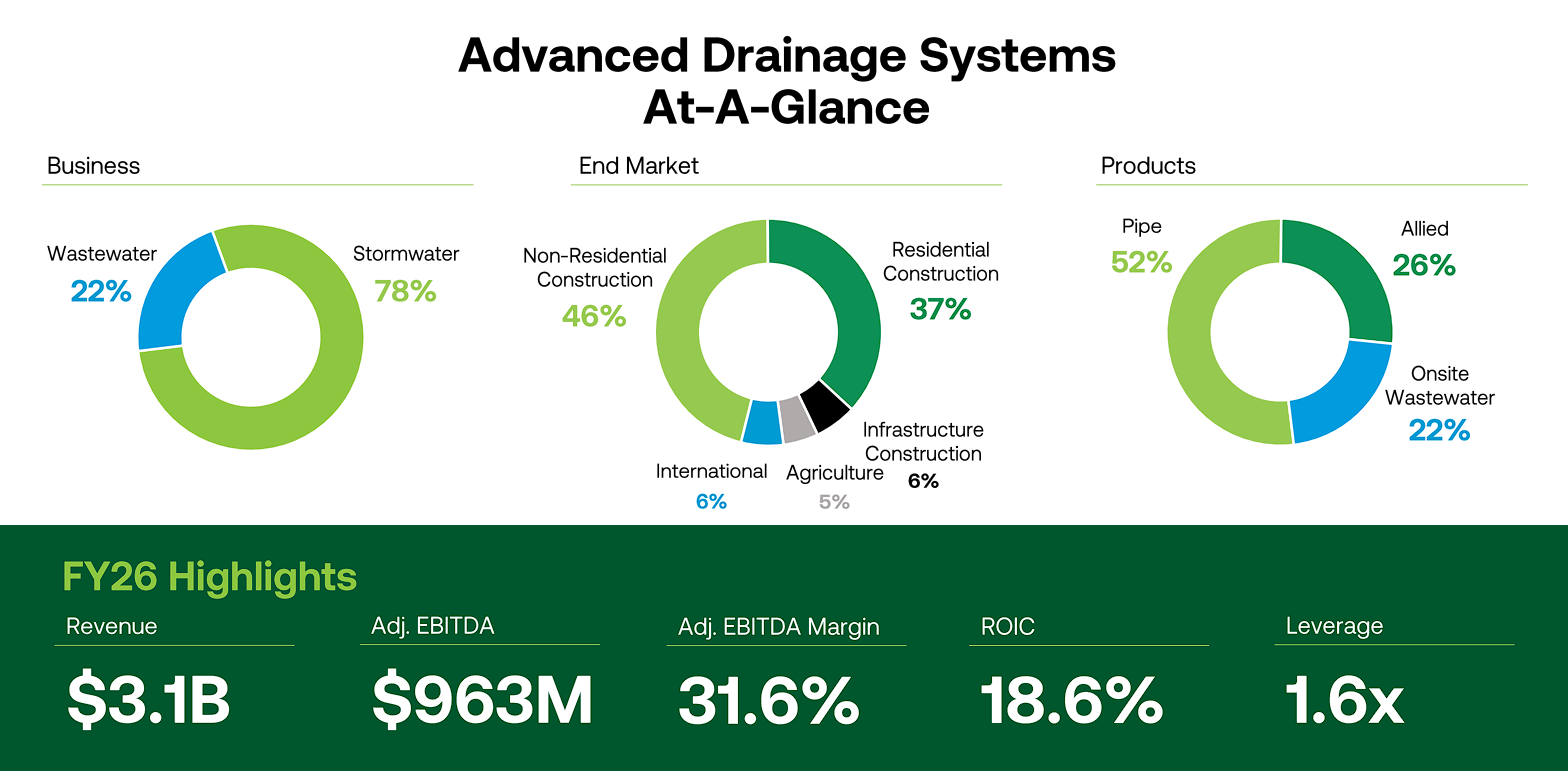
Advanced Drainage Systems manufactures thermoplastic pipe, chambers, tanks, and related products used to manage stormwater and onsite wastewater.
Its portfolio includes Infiltrator Water Technologies and the recently acquired NDS business.
The company is also one of North America’s largest plastics recyclers, which supports its cost position and environmental value proposition.
For the fiscal first quarter ended June 30, 2026, net sales increased 20.6% to $1.00 billion, including 9.2% organic growth.
Stormwater sales rose 24.2%, helped by $94.7 million from NDS, while Wastewater sales increased 7.5%.
Adjusted EBITDA grew 28.8% to $358.3 million, and margin expanded 230 basis points to 35.8%.
Diluted earnings-per-share from continuing operations increased 22.8% to $2.26.
Some demand was pulled forward ahead of price increases, and management remains cautious about the broader construction environment.
Even so, Advanced Drainage Systems reaffirmed fiscal 2027 targets of $3.35 billion to $3.55 billion in sales and $1.00 billion to $1.05 billion in adjusted EBITDA.
NDS expands the company’s reach in residential stormwater management and landscape irrigation, complementing its core pipe and allied-products platform.
The quarterly dividend rose to $0.20 from $0.18 a year earlier, extending its dividend-growth record to six years.
The payout ratio near 12% is very healthy.
Water Stock #3: H2O America (HTO)
- 5-year expected annual returns: 15.0%
H2O America is a regulated water and wastewater utility serving approximately 407,000 connections across California, Texas, Connecticut, and Maine.
Its earnings are driven mainly by approved rate increases and investment in essential infrastructure, making the business relatively predictable but capital intensive.
Second-quarter 2026 revenue increased 6% to $210.5 million, helped by $14.5 million of rate increases.
GAAP net income rose 8% to $26.6 million, while adjusted net income increased 17% to $30.7 million.
Adjusted earnings-per-share declined to $0.72 from $0.75 because the average share count increased following equity financing.
Management reiterated standalone 2026 adjusted earnings-per-share guidance of $3.08 to $3.18.
H2O America invested $206.9 million during the first half and expects approximately $483 million of capital spending in 2026.
Its five-year plan totals roughly $2.7 billion, including the pending $540 million Quadvest acquisition and planned investment in that system.
Quadvest would expand the company into greater Houston and add a sizable pipeline of contracted connections; closing is expected in the late third or early fourth quarter, subject to approvals.
The quarterly dividend is $0.44 per share.
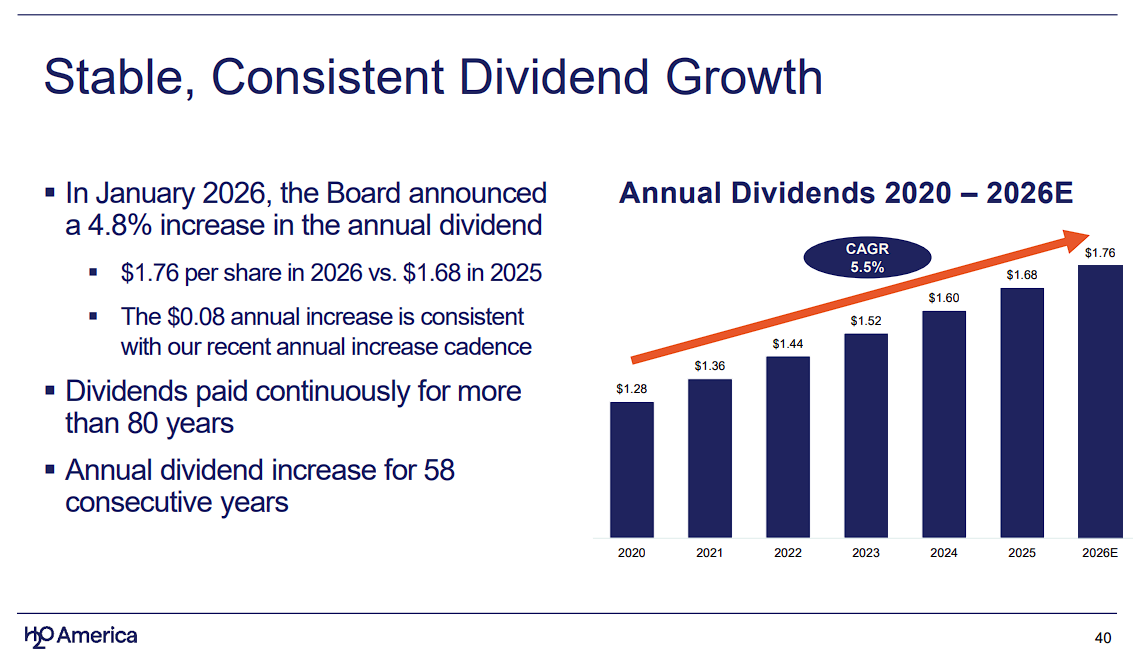
H2O America has paid dividends for more than 80 consecutive years and raised the annual payout for 58 straight years, one of the longest records in the water-utility industry.
Deep Dive: Click here to download (for free) our most recent 3-Page Sure Analysis PDF report on H2O America (HTO).
Water Stock #2: Badger Meter (BMI)
- 5-year expected annual returns: 20.1%
Badger Meter provides smart water metering, communications, monitoring, and analytics solutions through its BlueEdge platform.
Utilities use its meters, ORION cellular endpoints, BEACON software, and related technologies to improve billing accuracy, detect leaks, and reduce non-revenue water.
Software and connected devices are steadily increasing the recurring component of revenue.
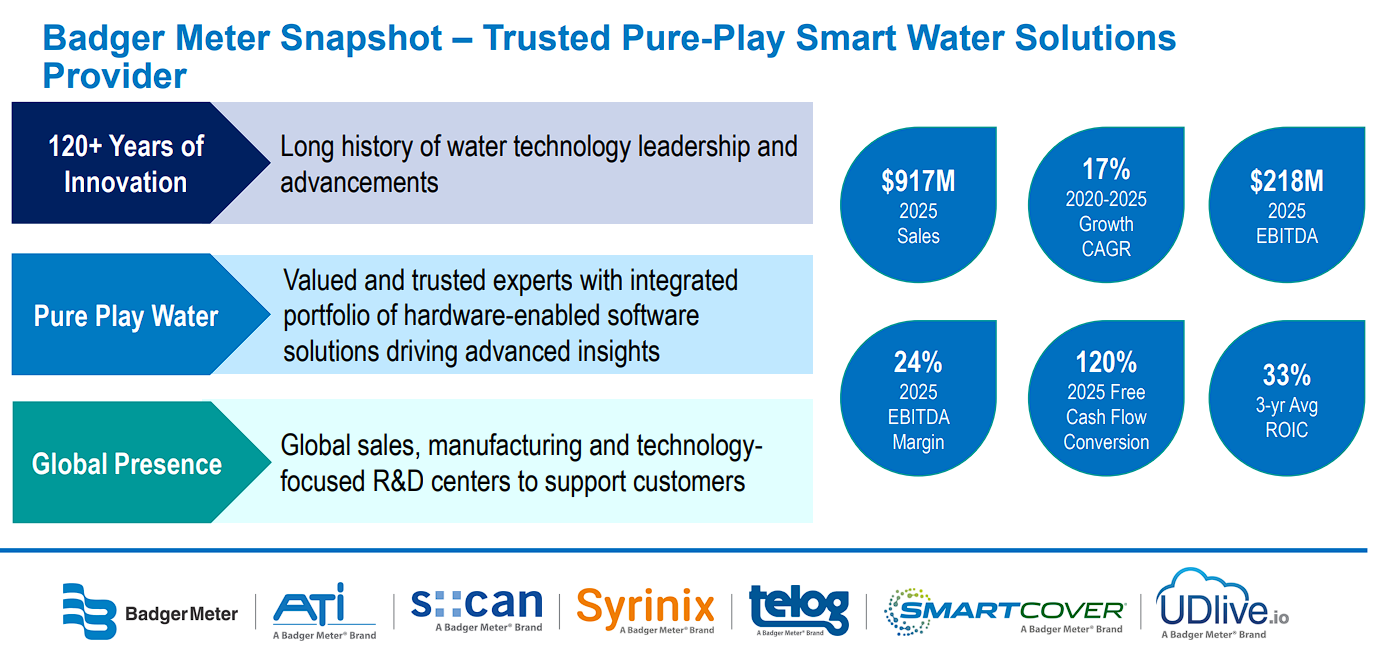
Second-quarter 2026 sales were $222.3 million, up 10% sequentially but down 7% from a particularly strong prior-year period.
Operating earnings declined 12% to $39.4 million, and earnings-per-share fell to $1.02 from $1.17.
Utility-water sales decreased 8% year-over-year as advanced-metering projects continued to phase unevenly, while flow-instrumentation sales increased 6%.
Management expects awarded projects to ramp further during the second half and projects roughly flat full-year base revenue versus 2025.
Badger Meter completed the acquisition of UDlive on May 1, adding sewer-monitoring technology and broader international capabilities to BlueEdge.
Early commercial interest has been encouraging, while the company’s recently renewed, undrawn $150 million credit facility preserves flexibility for growth investments and additional acquisitions.
In August, Badger Meter raised its quarterly dividend 10% to $0.44 per share, equal to $1.76 annually.
The increase marked its 34th consecutive year of annual dividend growth, while the payout ratio of roughly 39% indicates that the payout remains well supported despite near-term project timing variability.
Deep Dive: Click here to download (for free) our most recent 3-Page Sure Analysis PDF report on Badger Meter (BMI).
Water Stock #1: Stantec Inc. (STN)
- 5-year expected annual returns: 21.3%
Stantec is a global engineering, architecture, and environmental consulting company.
Water is one of its most important business lines, alongside buildings, infrastructure, environmental services, and energy and resources.
The company benefits from long-term spending on water security, resilience, aging infrastructure, and sustainable design, supplemented by targeted acquisitions.
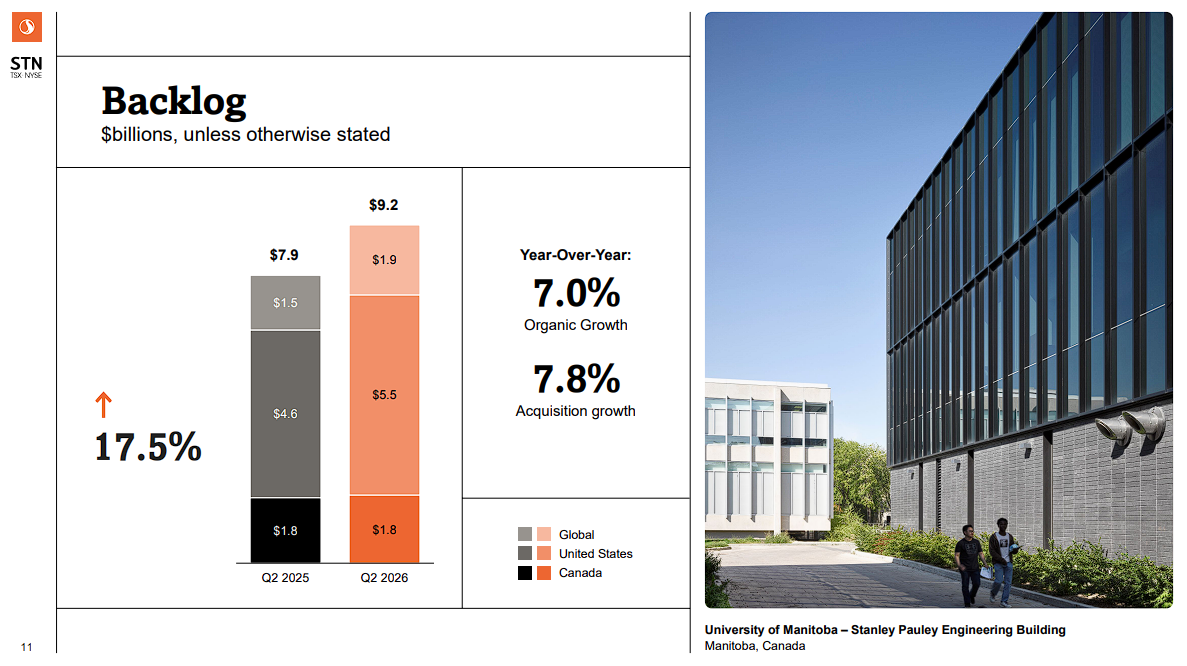
Second-quarter 2026 net revenue increased 11.5% to C$1.8 billion, driven by 3.7% organic growth and 7.1% acquisition growth.
Adjusted EBITDA rose 17.1% to C$332.9 million, while margin expanded 90 basis points to 18.7%.
Adjusted earnings-per-share increased 18.4% to C$1.61.
Contract backlog reached C$9.2 billion, up 17.5% year-over-year, with organic backlog growth of 7.0% and more than 10% growth in Water.
Management maintained its 2026 net-revenue growth target of 8.5% to 11.5% and adjusted earnings-per-share growth outlook of 15% to 18%.
It also raised adjusted EBITDA margin guidance to 17.8% to 18.3%.
Stantec pays a C$0.245 quarterly dividend and has increased its annual payout for 14 consecutive years.
Its payout ratio is below 20%, leaving substantial room for continued dividend growth and reinvestment.
Susan Reisbord is scheduled to become chief executive officer on October 1, providing a planned internal succession from outgoing CEO Gord Johnston.
Investors should monitor acquisition integration, currency movements, public-project timing, and whether the company can convert its record backlog while sustaining recent margin gains.
Deep Dive: Click here to download (for free) our most recent 3-Page Sure Analysis PDF report on Stantec Inc. (STN).
Final Thoughts
Aging infrastructure, population growth, water scarcity, and tighter quality standards should support sustained investment across the water economy.
The Top 10 offers several ways to participate, from regulated utility H2O America to equipment specialists Xylem, Badger Meter, Pentair, A.O. Smith, Masco, and Advanced Drainage Systems.
Stantec, Tetra Tech, and Jacobs add engineering and consulting exposure tied to long-duration public and private projects.
Stantec and Badger Meter currently lead the ranking by expected total return, while H2O America combines the group’s highest yield with a 58-year dividend-growth record.
Those projections rely on different drivers, including earnings growth, valuation changes, and dividends, so the headline return figures should not be viewed as equally certain.
We recommend weighing each company’s valuation, balance sheet, end-market sensitivity, and dividend profile alongside its expected return.
Additional Resources
It may be useful to browse through the following databases of dividend growth stocks:
- The Dividend Aristocrats List: S&P 500 stocks with 25+ years of dividend increases.
- The Dividend Kings List is even more exclusive than the Dividend Aristocrats. It is comprised of stocks with 50+ years of consecutive dividend increases.
- The High Dividend Stocks List: stocks that appeal to investors interested in the highest yields of 4% or more.
- The Monthly Dividend Stocks List: stocks that pay dividends every month, for 12 dividend payments per year.