Updated on November 1st, 2026 by Nikolaos Sismanis
Dividend Kings are stocks with an incredible 50 or more consecutive years of dividend increases. They are the best-of-the-best in dividend longevity.
This research report includes the following valuable free Dividend Kings resources.
Resource #1: The Dividend Kings Spreadsheet List
This spreadsheet contains important metrics, including: years of dividend growth, dividend yields, payout ratios, buy/hold/sell ratings, fair value prices, expected total returns, and much more.
Resource #2: The 10 Best Dividend Kings Today
This research report analyzes the 10 best Dividend Kings now as ranked by expected total return. Expected total returns include estimated earnings-per-share growth, dividends, and the impact of any valuation multiple changes.
This ranking is best used as a research shortlist rather than an automatic buy list.
Rankings and bullet-point metrics use the October 30th, 2026 Sure Analysis spreadsheet. Company developments are current through October 30th, 2026.
- #10: Sonoco Products (SON)
- #9: PPG Industries (PPG)
- #8: H.B. Fuller (FUL)
- #7: Hormel Foods (HRL)
- #6: RPM International (RPM)
- #5: Automatic Data Processing (ADP)
- #4: The Marzetti Company (MZTI)
- #3: PepsiCo (PEP)
- #2: Stepan Company (SCL)
- #1: H2O America (HTO)
Resource #3: Sure Analysis Reports On All Dividend Kings
We cover all 60 Dividend Kings in the Sure Analysis Research Database. All are updated quarterly. This resource has links to our most recent stand-alone analysis on each of the Dividend Kings.
Dividend King #10: Sonoco Products (SON)
- 5-Year Expected Total Return: 13.4%
- Dividend Yield: 4.3%
Sonoco Products manufactures metal and paper packaging for consumer and industrial customers, including food cans, paper containers, tubes, and protective packaging products.
Its scale and established customer relationships support recurring demand, although manufacturing volumes, raw-material costs, and acquisition integration can affect profitability.
Sure Analysis classifies Sonoco as a Dividend King. Its quarterly dividend is $0.54 per share, equivalent to $2.16 annually.
In its third-quarter 2026 results, Sonoco reported sales of $2.04 billion, down 4.2%, mainly reflecting the ThermoSafe divestiture.
Adjusted earnings per share fell 13% to $1.67 as inflation and weaker volume and mix outweighed productivity savings.
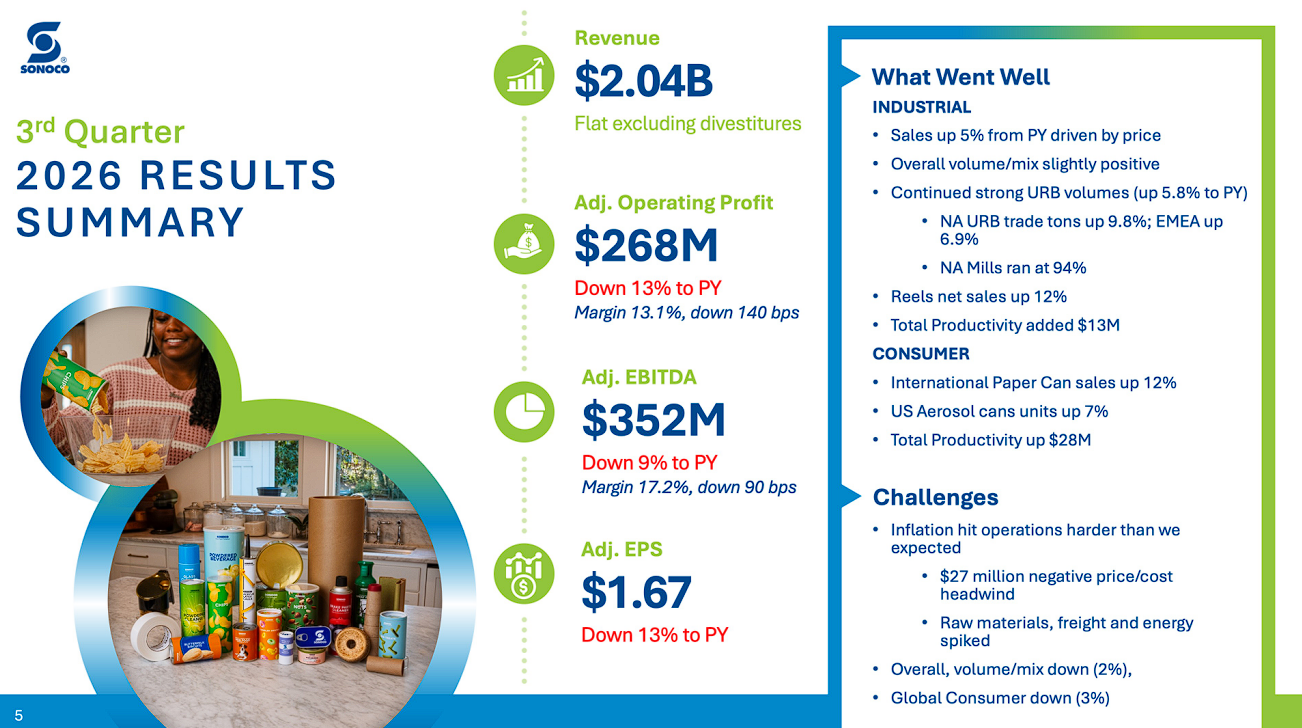
An $829 million noncash goodwill impairment drove a GAAP loss of $7.36 per share, highlighting pressure in its overseas packaging operations.
Management reduced full-year adjusted earnings-per-share guidance to $5.30 to $5.50, compared with $5.80 to $6.20 previously.
Operating cash flow reached $285 million during the quarter, but debt reduction, cost recovery, and the Eviosys integration remain central priorities.
The dividend yield and potential valuation recovery support the expected return, while the weaker outlook makes execution particularly important.
Deep Dive: Click here to download (for free) our most recent 3-Page Sure Analysis PDF report on Sonoco Products (SON).
Dividend King #9: PPG Industries (PPG)
- 5-Year Expected Total Return: 13.7%
- Dividend Yield: 2.5%
PPG Industries is one of the world’s largest coatings companies, serving aerospace, automotive, industrial, packaging, and architectural customers.
Its technology, customer relationships, and global manufacturing footprint provide competitive advantages, although results remain exposed to industrial activity and raw-material costs.
PPG has increased its dividend for 55 consecutive years. In July, the board raised the quarterly payout by $0.03 to $0.74.
In its third-quarter 2026 results, net sales increased 7% to $4.35 billion, including 5% organic growth.
Adjusted earnings per share rose 6% to $2.25, supported by aerospace, Latin American architectural coatings, pricing, and productivity improvements.
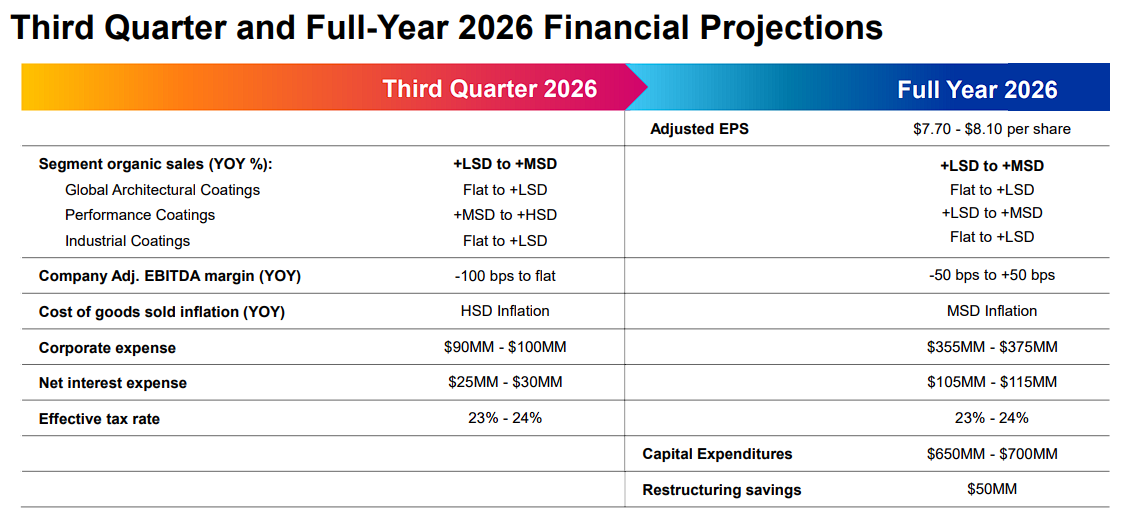
The company’s commercial actions fully offset cost-of-goods-sold inflation during the quarter, an improvement from the incomplete recovery reported earlier in the year.
PPG raised the midpoint of its full-year adjusted earnings-per-share outlook and narrowed the range to $7.90 to $8.10.
Year-to-date operating cash flow reached about $1.2 billion, while third-quarter repurchases totaled $150 million.
The moderate payout ratio, continued dividend growth, and potential valuation expansion support the investment case, although industrial demand and input costs remain important risks.
Deep Dive: Click here to download (for free) our most recent 3-Page Sure Analysis PDF report on PPG Industries (PPG).
Dividend King #8: H.B. Fuller (FUL)
- 5-Year Expected Total Return: 13.9%
- Dividend Yield: 2.0%
H.B. Fuller manufactures adhesives, sealants, and specialty chemical products for packaging, hygiene, construction, electronics, and other industrial applications.
Its technical expertise and customer-specific formulations can create durable relationships, while exposure to many end markets provides diversification.
The company has increased its dividend for 57 consecutive years. Its quarterly payout is $0.245 per share, or $0.98 annualized.
For the third quarter of fiscal 2026, revenue increased 5.2% to $938 million and organic revenue grew 4.4%.
Pricing more than offset lower volume, while restructuring savings helped adjusted EBITDA rise 9% to $187 million.
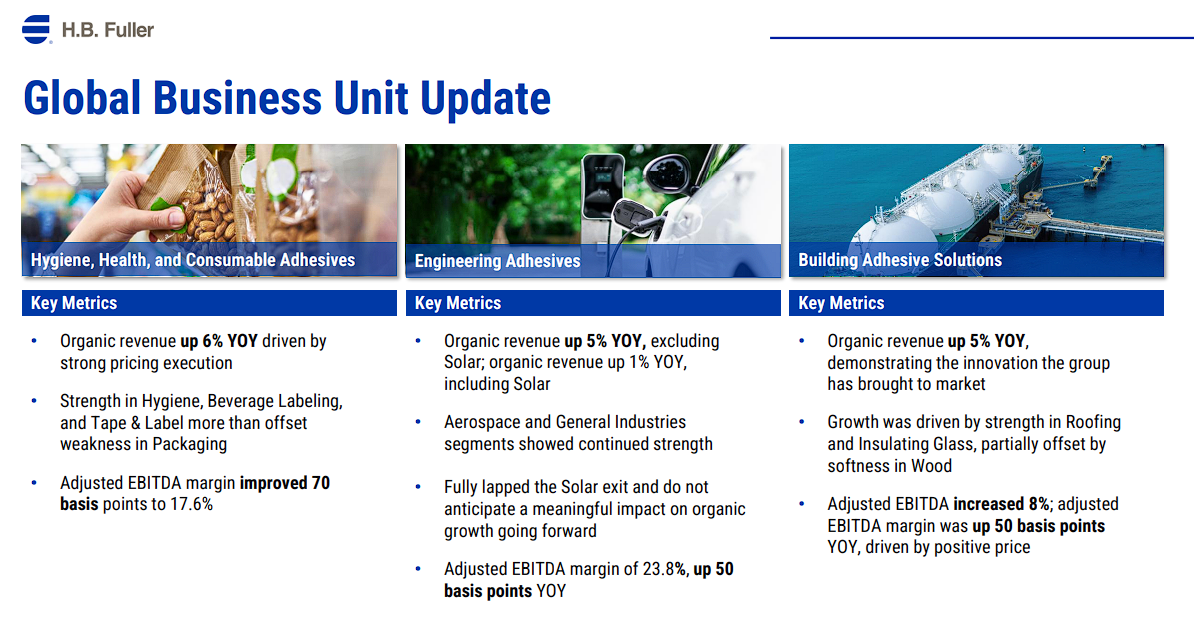
Adjusted EBITDA margin expanded 80 basis points to 19.9%, and adjusted earnings per share increased 21% to $1.52.
Management expects full-year adjusted earnings per share of $4.70 to $4.85 and operating cash flow of $300 million to $325 million, excluding AMS-related items.
The proposed acquisition of Advanced Medical Solutions expands Fuller’s higher-value medical adhesives business and remains expected to close by year-end, subject to remaining conditions.
However, the financing adds risk to a balance sheet already carrying net debt of about three times adjusted EBITDA.
A payout ratio near 21% provides dividend coverage, but the return case also depends on margin gains, successful integration, and eventual debt reduction.
Deep Dive: Click here to download (for free) our most recent 3-Page Sure Analysis PDF report on H.B. Fuller (FUL).
Dividend King #7: Hormel Foods (HRL)
- 5-Year Expected Total Return: 14.2%
- Dividend Yield: 5.6%
Hormel Foods owns a broad collection of branded food products, including SPAM, Planters, Skippy, Applegate, Jennie-O, and Hormel Natural Choice.
Its brands and foodservice relationships provide durable demand, although commodity costs, consumer pressure, and retailer competition can weigh on margins.
Hormel has increased its dividend for 60 consecutive years. The quarterly payout is $0.2925 per share, or $1.17 annually.
Fiscal third-quarter 2026 net sales were $2.96 billion, while organic net sales declined 2%.
Adjusted operating income increased to $266 million, adjusted earnings per share rose to $0.37 from $0.35, and cash flow from operations climbed 54% to $241 million.
Foodservice remained the strongest segment, with organic sales up 2% and segment profit up 3%, while Retail organic sales fell 3%.
Management raised and narrowed full-year adjusted earnings-per-share guidance to $1.45 to $1.51, while reducing the net-sales outlook to $12.1 billion to $12.2 billion.
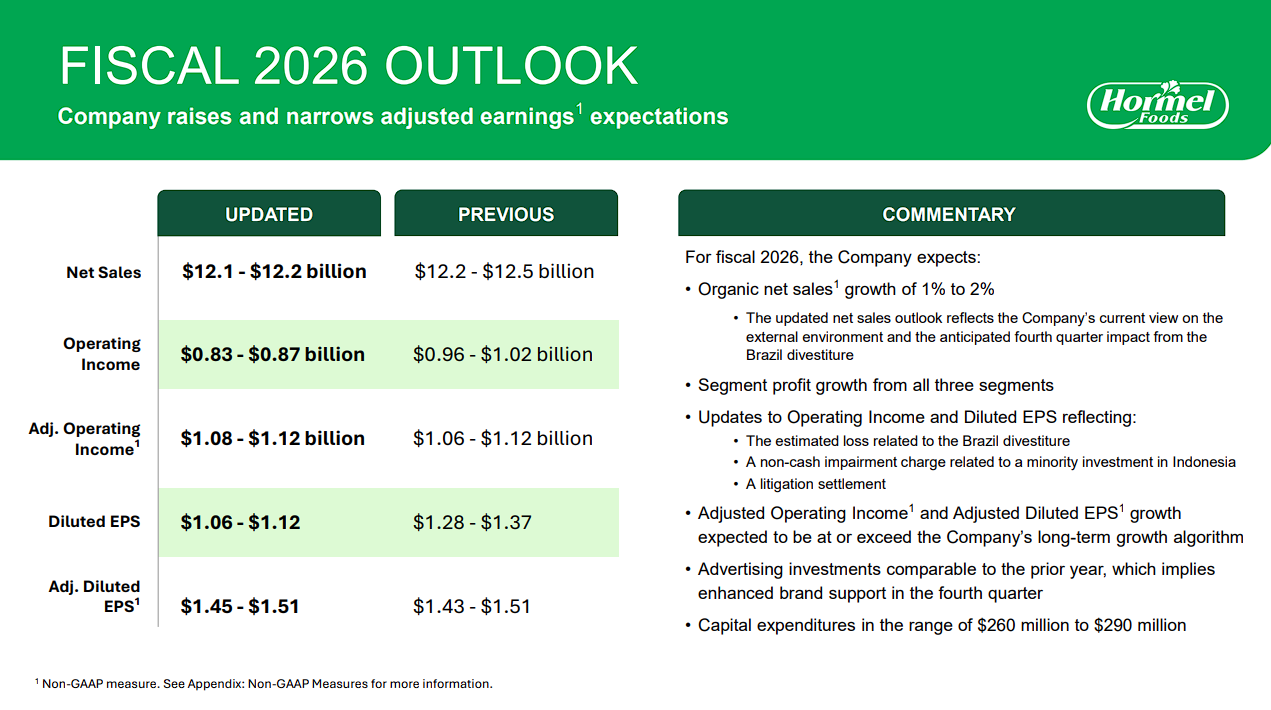
Hormel completed the sale of its Brazil operations early in the fourth quarter, simplifying the portfolio but creating one-time GAAP charges.
On September 30th, Hormel agreed to acquire Brakebush Brothers for $1.055 billion.
The chicken business strengthens Foodservice, but closing is expected in fiscal 2027’s first quarter and adjusted EPS accretion is not expected until fiscal 2028.
The roughly 78% payout ratio and acquisition funding requirements make improving cash flow and disciplined execution important to sustaining dividend growth.
Deep Dive: Click here to download (for free) our most recent 3-Page Sure Analysis PDF report on Hormel Foods (HRL).
Dividend King #6: RPM International (RPM)
- 5-Year Expected Total Return: 14.2%
- Dividend Yield: 2.2%
RPM International manufactures specialty coatings, sealants, and building materials for industrial, professional, and consumer customers.
Its portfolio includes Rust-Oleum, DAP, Tremco, and other established brands, while repair, maintenance, and renovation spending support recurring demand.
On October 8th, RPM raised its quarterly dividend 5.6% to $0.57, marking its 53rd consecutive year of increases.
In its first quarter of fiscal 2027, sales increased 4.8% to a record $2.22 billion, including 3.1% organic growth.
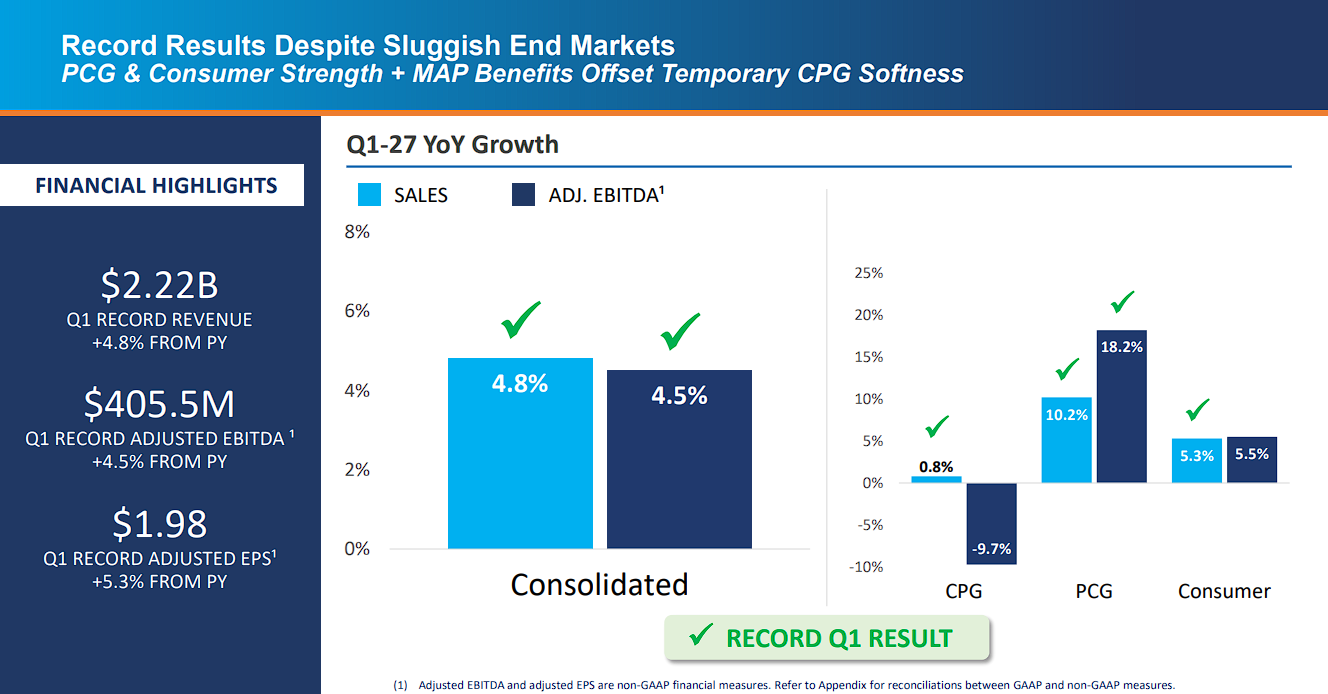
Adjusted earnings per share increased 5.3% to $1.98, while adjusted EBITDA grew 4.5% to $405.5 million.
Performance Coatings and Consumer growth, pricing, and operational improvements offset a softer Construction Products quarter and higher raw-material costs.
Operating cash flow increased to $263.9 million from $237.5 million, supporting investment, dividends, and share repurchases.
Management expects fiscal 2027 sales and adjusted EBITDA to increase at mid-single-digit rates, with low- to mid-single-digit growth expected in the second quarter.
RPM’s margin initiatives and niche brands should support long-term earnings growth, although construction demand and inflation can affect near-term results.
The expected return combines the dividend, earnings growth, and potential valuation expansion from the current discounted multiple.
Deep Dive: Click here to download (for free) our most recent 3-Page Sure Analysis PDF report on RPM International (RPM).
Dividend King #5: Automatic Data Processing (ADP)
- 5-Year Expected Total Return: 14.4%
- Dividend Yield: 2.3%
Automatic Data Processing is a leading provider of payroll, human-capital management, benefits, and compliance solutions.
Its software and services are embedded in customers’ daily operations, supporting recurring revenue, high retention, and substantial free cash flow.
More than 1.1 million clients across over 140 countries use ADP’s platforms.
The company has raised its dividend for 51 consecutive years. Its quarterly payout is $1.70 per share, or $6.80 annualized.
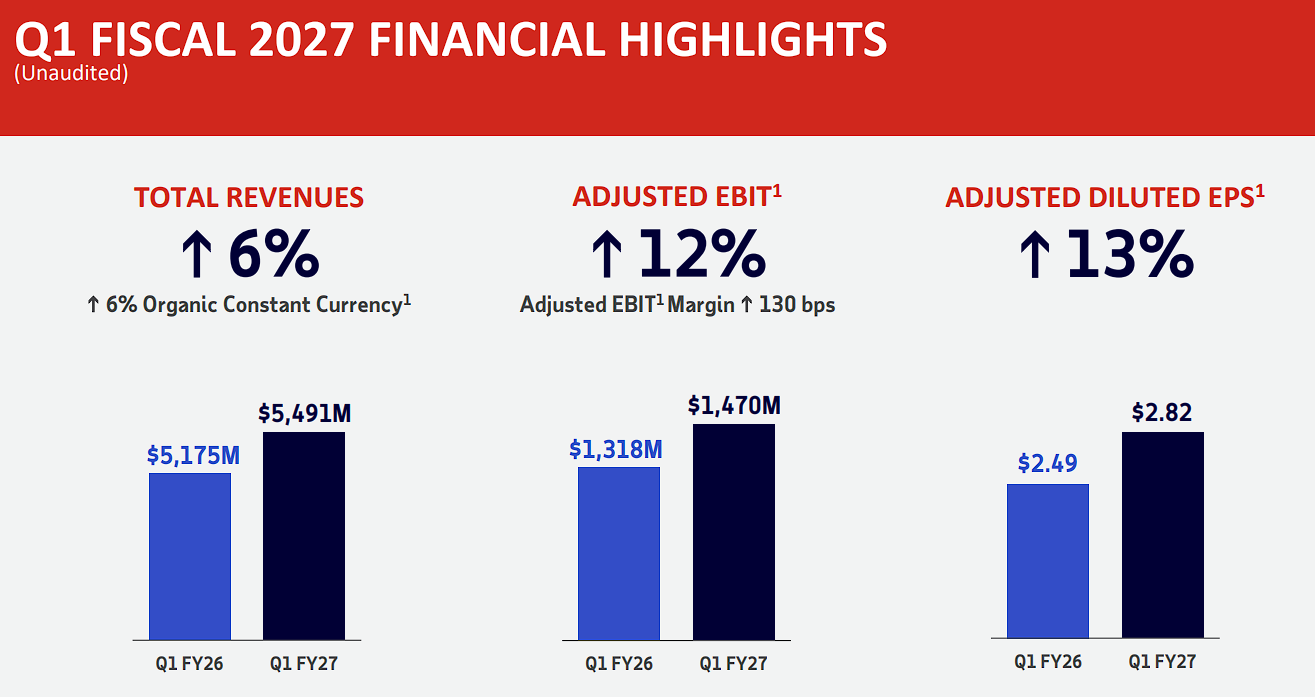
For the first quarter of fiscal 2027, revenue increased 6% to $5.49 billion and adjusted earnings per share rose 13% to $2.82.
Adjusted EBIT margin expanded 130 basis points to 26.8%, while U.S. pays per control increased 2%.
Interest on client funds grew 15% to $329 million as both balances and investment yields increased.
Management raised its full-year outlook to about 6% revenue growth and 10% to 12% adjusted earnings-per-share growth, while maintaining its 70- to 90-basis-point margin-expansion target.
Product development increasingly centers on AI-enabled insights and the ADP Lyric platform, while WorkForce Software expands global workforce-management capabilities.
Employment levels and interest rates affect results, but recurring revenue, earnings growth, and a lower valuation than ADP has often carried support the projected return.
Dividend King #4: The Marzetti Company (MZTI)
- 5-Year Expected Total Return: 14.5%
- Dividend Yield: 3.6%
The Marzetti Company, formerly Lancaster Colony, manufactures specialty food products for retail and foodservice customers.
Its portfolio includes Marzetti dressings, New York Bakery products, Sister Schubert’s rolls, licensed restaurant sauces, and the recently acquired Bachan’s brand.
The company increased its regular cash dividend for the 63rd consecutive year in fiscal 2026, and the current quarterly payout is $1.00 per share.
Fiscal fourth-quarter sales declined 2.2% to $465.0 million, but increased 0.4% after excluding non-core temporary supply-agreement revenue from the comparison.
Retail sales rose 0.9%, including $15.4 million from Bachan’s, while adjusted Foodservice sales were nearly flat.
Gross profit reached a fourth-quarter record of $114.0 million, gross margin expanded 220 basis points to 24.5%, and adjusted earnings per share increased 9% to $1.46.
For fiscal 2026, sales rose 1.1% to $1.93 billion, adjusted earnings per share increased to $6.83 from $6.72, and operating cash flow reached a record $283.8 million.
The $400 million Bachan’s acquisition adds a growing sauce platform but also introduced a $200 million term loan and integration risk.
First-quarter fiscal 2027 results are scheduled for November 3rd.
With modest earnings growth assumed in our model, the expected return depends substantially on the dividend and a recovery in the valuation multiple, making customer demand and acquisition execution important.
Dividend King #3: PepsiCo (PEP)
- 5-Year Expected Total Return: 15.6%
- Dividend Yield: 4.3%
PepsiCo owns a diversified portfolio of global snack and beverage brands, including Pepsi, Gatorade, Doritos, Lay’s, Quaker, and Cheetos.
Its brand strength, distribution network, and geographic reach have produced durable cash flow across economic cycles.
PepsiCo has paid consecutive quarterly dividends since 1965 and marked its 54th consecutive annual increase in 2026.
The quarterly dividend is $1.48, or $5.92 annualized, following a 4% increase.
In its third-quarter 2026 results, revenue rose 5.6% to $25.27 billion, organic revenue grew 3.1%, and core earnings per share increased 2% to $2.34.
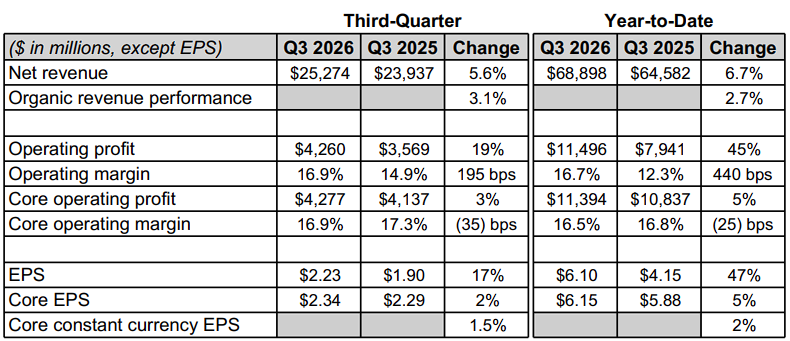
International operations provided growth, while North American organic revenue remained flat and beverage volumes declined 2%.
Core operating margin contracted 35 basis points despite productivity savings and a favorable tariff-refund benefit.
Management now expects about 3% organic revenue growth and 1% to 2% core constant-currency EPS growth, below the prior profit-growth outlook.
Including currency effects, core EPS is expected to increase 2.5% to 3.5%.
The company still plans $7.9 billion in dividends and $1.0 billion in repurchases for 2026.
The yield provides meaningful income, but realizing the projected return also requires better volume trends, margin recovery, and disciplined cost management.
Deep Dive: Click here to download (for free) our most recent 3-Page Sure Analysis PDF report on PepsiCo (PEP).
Dividend King #2: Stepan Company (SCL)
- 5-Year Expected Total Return: 16.6%
- Dividend Yield: 2.3%
Stepan Company manufactures surfactants, polymers, and specialty products used in cleaning, agriculture, oilfield services, insulation, construction, food, and pharmaceutical applications.
Its broad end markets provide diversification, but earnings remain sensitive to raw-material costs, industrial demand, and capacity utilization.
On October 28th, Stepan raised its quarterly dividend from $0.395 to $0.405 per share, marking its 59th consecutive year of increases.
In its third-quarter 2026 results, sales increased 17% to $692.2 million, global volume rose 3%, and organic volume increased 7%.
Adjusted net income increased 98% to $21.7 million, while adjusted EBITDA rose 18% to $66.3 million.
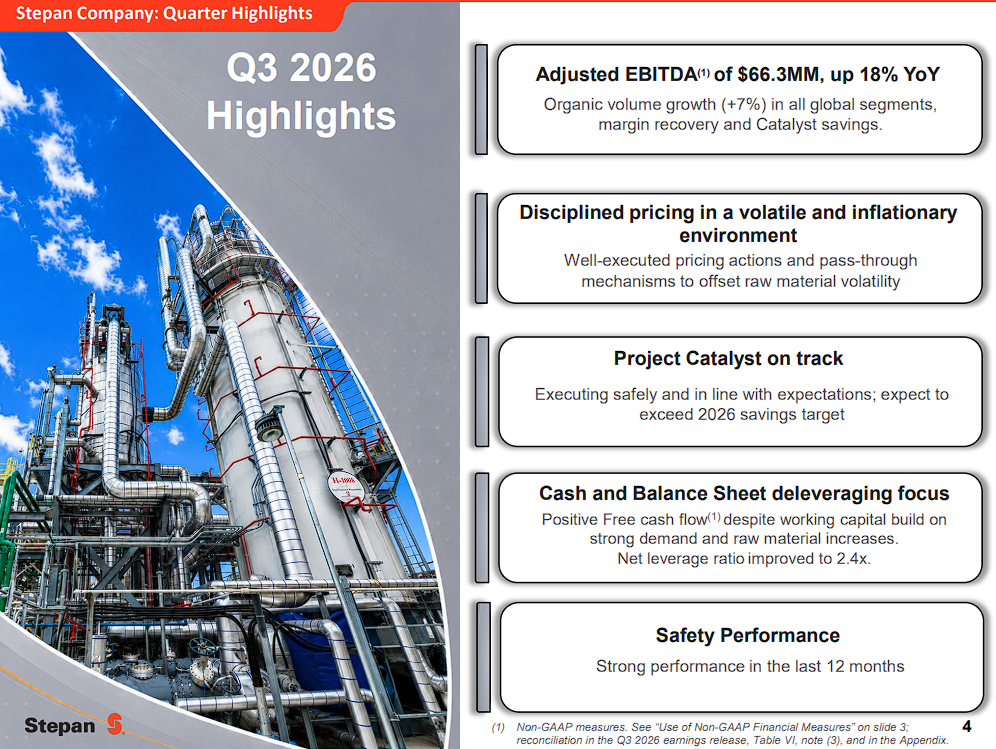
Free cash flow improved to positive $8.2 million, although higher working-capital needs continued to limit cash generation.
Project Catalyst savings and margin recovery supported all three operating segments. The organizational redesign included about 100 salaried job reductions during the quarter.
Stepan also completed a $28.5 million land sale in October, with proceeds designated for debt repayment.
The expected return depends heavily on earnings recovery rather than valuation expansion: the spreadsheet price exceeds our current fair-value estimate.
The A Dividend Risk Score offers some support, but the aggressive growth assumption, restructuring costs, and cyclical demand make execution important.
Deep Dive: Click here to download (for free) our most recent 3-Page Sure Analysis PDF report on Stepan Company (SCL).
Dividend King #1: H2O America (HTO)
- 5-Year Expected Total Return: 17.2%
- Dividend Yield: 3.0%
H2O America is a regulated water utility serving customers in California, Connecticut, Maine, and Texas.
The essential nature of water service, regulated rate recovery, and long-lived infrastructure make its earnings relatively predictable.
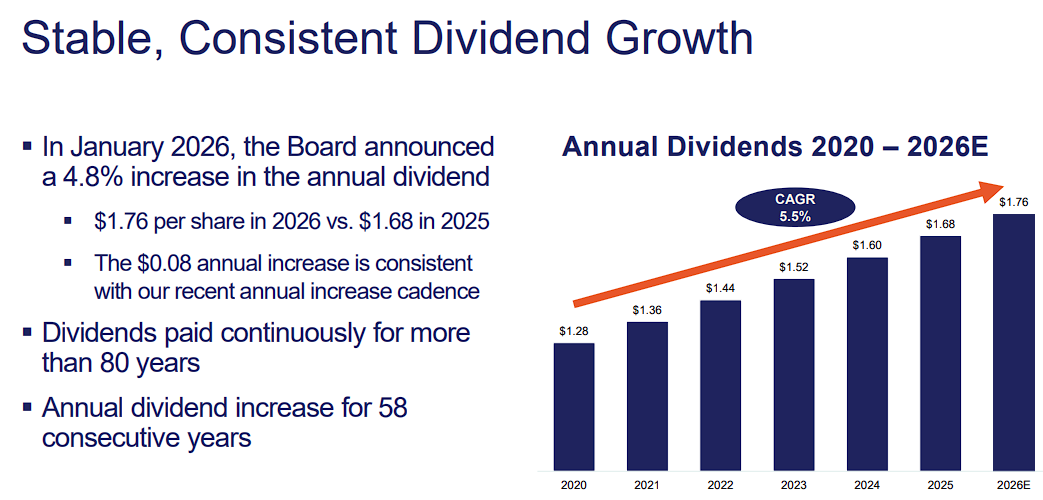
H2O America has paid dividends for more than 80 years and has increased the payout for 58 consecutive years.
Its quarterly dividend is $0.44, equivalent to $1.76 annually.
In its third-quarter 2026 results, revenue increased 4% to $250.2 million, supported by $16.2 million in rate increases.
Adjusted net income declined 1% to $45.2 million, while adjusted earnings per share fell to $1.04 from $1.27, mainly because of the higher share count.
The Quadvest acquisition closed on October 1st for $542.7 million in cash consideration, expanding the company’s Houston-area operations.
Management narrowed standalone adjusted EPS guidance to $3.10 to $3.16, but its acquisition-inclusive outlook is lower at $2.91 to $2.97 because of near-term financing and rate-recovery dilution.
The company now targets about $465 million in 2026 company-funded infrastructure investment while retaining its $2.7 billion capital plan through 2030.
Regulated investment and Texas customer growth support the longer-term outlook, but the high modeled return depends on successful integration, timely rate recovery, and sustained earnings growth.
Deep Dive: Click here to download (for free) our most recent 3-Page Sure Analysis PDF report on H2O America (HTO).
Detailed Analysis On All 60 Dividend Kings
You can download (for free) the most recent 3-page PDF Sure Analysis Research Database report for every Dividend King at the links below. The Dividend Kings are organized by sector for easy access.
Consumer Staples
- Altria Group (MO)
- Archer-Daniels-Midland (ADM)
- Colgate-Palmolive (CL)
- Coca-Cola (KO)
- Hormel Foods (HRL)
- Kimberly-Clark (KMB)
- The Marzetti Company (MZTI)
- PepsiCo (PEP)
- Procter & Gamble (PG)
- Sysco Corporation (SYY)
- Target Corporation (TGT)
- Tootsie Roll Industries (TR)
- Universal Corporation (UVV)
- Walmart (WMT)
Industrials
- ABM Industries (ABM)
- Automatic Data Processing (ADP)
- Carlisle Companies (CSL)
- Dover (DOV)
- Emerson Electric (EMR)
- Gorman-Rupp Co. (GRC)
- Illinois Tool Works (ITW)
- MSA Safety (MSA)
- Nordson Corporation (NDSN)
- Parker-Hannifin (PH)
- Pentair (PNR)
- Stanley Black & Decker (SWK)
- Tennant Co. (TNC)
- W.W. Grainger (GWW)
Health Care
- Abbott Laboratories (ABT)
- AbbVie Inc. (ABBV)
- Becton, Dickinson & Company (BDX)
- Johnson & Johnson (JNJ)
- Kenvue Inc. (KVUE)
Consumer Discretionary
Financials
- Commerce Bancshares Inc. (CBSH)
- Cincinnati Financial (CINF)
- Farmers & Merchants Bancorp (FMCB)
- RLI Corp. (RLI)
- S&P Global (SPGI)
- United Bankshares (UBSI)
Materials
- H.B. Fuller (FUL)
- PPG Industries (PPG)
- Nucor (NUE)
- RPM International (RPM)
- Sonoco Products (SON)
- Stepan Co. (SCL)
Energy
Real Estate
Utilities
- American States Water (AWR)
- Black Hills Corp. (BKH)
- California Water Service Group (CWT)
- Canadian Utilities (CDUAF)
- Consolidated Edison (ED)
- Fortis Inc. (FTS)
- MGE Energy (MGEE)
- Middlesex Water Company (MSEX)
- Northwest Natural Holding (NWN)
- H2O America (HTO)
Final Thoughts
The Dividend Kings are already a highly selective group.
Each company has raised its dividend for at least 50 consecutive years, navigating recessions, inflation, rising interest rates, and major changes within its industry.
Dividend Kings satisfy the 25+ years dividend-increase requirement for a Dividend Aristocrat twice over.
Note: Not all Dividend Kings are Dividend Aristocrats because Dividend Aristocrats must also belong to the S&P 500 and meet minimum size and liquidity requirements.
The ten stocks highlighted above pair exceptional dividend longevity with the highest expected returns in the current Dividend Kings universe.
However, the return drivers differ considerably.
- Hormel Foods offers the highest starting yield, while PepsiCo and Sonoco also provide substantial income but face demand and cost pressures.
- ADP benefits from recurring revenue and earnings growth, while The Marzetti Company relies more heavily on dividends and valuation recovery.
- Stepan, PPG Industries, RPM International, and H.B. Fuller offer exposure to margin improvement, specialty materials, and potential valuation recovery.
- H2O America adds regulated utility exposure, with Texas customer growth balanced against acquisition financing and delayed rate recovery.
The unusually high projected returns should not be interpreted as equal risk across the group.
Stepan’s estimate depends on restructuring success, Hormel’s high yield comes with an elevated payout ratio and a pending acquisition, and H2O America faces near-term acquisition dilution.
Sonoco and PepsiCo have lowered their earnings outlooks, while RPM International and H.B. Fuller remain exposed to industrial demand and acquisition execution, so a discounted valuation alone does not guarantee a favorable outcome.
As a result, the ranking is most useful as a starting point for further research, with investors matching each company’s income, growth, and risk profile to their own objectives.
Other Sure Dividend Resources
- Dividend Champions: 25+ years of rising dividends
- Dividend Aristocrats: 25+ years of rising dividends and in the S&P 500
- High Dividend Stocks: 4%+ dividend yields
- Monthly Dividend Stocks: Individual securities that pay out every month
- Royalty Stocks: Detailed royalty stocks list
- MLPs: Detailed MLP list
- REITs: Detailed REIT list
- BDCs: Detailed BDC list